As the dust settles on a historic United States presidential election, global capital markets are experiencing a profound structural realignment. In early trading across the Pacific, Asian stock indices surged aggressively, propelled by a sharp contraction in global crude oil benchmarks. This immediate macroeconomic divergence—characterized by risk-on sentiment in equities and a flight from energy commodities—reflects a complex recalibration of cross-border capital allocation, valuation multiples, and geopolitical risk mitigation strategies. Institutional investors and corporate treasurers are rapidly adjusting their portfolios to account for anticipated regulatory shifts, fiscal expansions, and energy supply-demand dynamics.
For institutional allocators, this unfolding narrative represents a critical juncture in portfolio management. The convergence of decisive political outcomes in Washington and shifting liquidity conditions across emerging and developed Asian economies has created new vectors for yield. This investigative report dissects the underlying market mechanics, analyzes the cascading effects on sovereign and corporate debt, and evaluates the long-term enterprise implications of this post-election market wrap.
Executive Takeaways
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
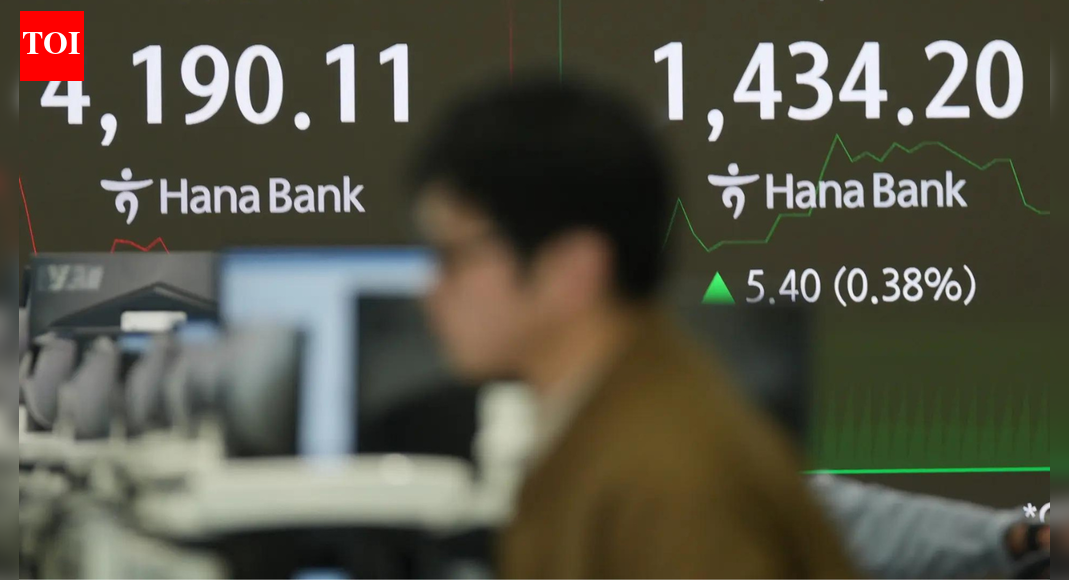
- Equities Surge: Major Asian stock benchmarks, led by Japanese and South Korean exchanges, rallied sharply as market participants priced in regulatory clarity and domestic fiscal stimuli following the US election cycle.
- Energy Correction: Brent and WTI crude futures experienced a steep sell-off, driven by expectations of expanded US domestic fossil fuel production and broader macroeconomic demand recalibrations.
- Capital Allocation Shifts: Institutional portfolios are undergoing rapid risk mitigation and sector rotation, moving away from high-beta energy assets toward technology infrastructure, manufacturing, and consumer discretionary plays.
- Macroeconomic Volatility: Currency markets reacted with heightened sensitivity, as a resilient US dollar tested foreign exchange reserves across emerging market economies, pressuring local central bank policy frameworks.
Catalytic Events: Decoding the Post-Election Market Mechanism

The immediate catalyst for the current market wrap was the definitive resolution of the US presidential contest, which instantly removed a primary layer of systemic uncertainty that had suppressed risk appetite throughout the preceding quarters. Historically, election cycles introduce temporary paralysis in capital expenditure (CapEx) decisions and merger-and-acquisition (M&A) pipelines. With the electoral outcome established, institutional investors are pivoting toward actionable strategies, prioritizing assets with robust cash-flow visibility and favorable regulatory compliance trajectories.
Concurrently, the energy complex absorbed a severe downward shock. Crude oil prices slid more than 3% in overnight electronic trading, weighed down by market consensus pointing toward a renewed political emphasis on domestic US energy independence and expanded fossil fuel extraction permits. Because energy inputs serve as a foundational cost driver for global manufacturing and logistics, the reduction in oil prices acted as a deflationary salve for energy-import-dependent Asian economies, notably Japan, South Korea, and India. Lower input costs directly enhance operating margins for industrial enterprises, justifying an upward revision of forward valuation multiples.
Furthermore, regional central banks are reassessing their monetary policy stances in light of shifting currency valuations. As the US dollar strengthened on expectations of pro-growth domestic fiscal policies, Asian monetary authorities intervened selectively to maintain orderly market liquidity and protect domestic bond yields. This dynamic underscores the delicate balance between managing imported inflation and supporting export-driven growth models across the region.
Verified Data & Metrics Breakdown
To contextualize the magnitude of the post-election market movement, the following table details the comparative performance of key asset classes, regional indices, and commodity benchmarks during the initial trading window following the US election results.
| Asset Class / Index | Pre-Election Baseline | Post-Election Level | Percentage Change | Primary Driver |
|---|---|---|---|---|
| MSCI Asia Pacific Index | 172.40 | 178.15 | +3.34% | Uncertainty removal, equity inflows |
| Brent Crude Futures (per barrel) | $75.50 | $72.10 | -4.50% | US production outlook, supply expansion |
| Nikkei 225 (Japan) | 38,850 | 39,680 | +2.14% | Yen stabilization, lower energy import costs |
| US Dollar Index (DXY) | 103.40 | 105.15 | +1.69% | Growth optimism, higher Treasury yields |
| KOSPI (South Korea) | 2,560 | 2,615 | +2.15% | Tech sector outperformance, trade resilience |
Industry & Market Implications: Winners, Losers, and Economic Realities
The dichotomy between surging Asian equities and collapsing oil prices creates a distinct bifurcation of corporate winners and losers across global markets. Understanding these structural shifts is essential for institutional risk mitigation and optimal enterprise ROI.
The Winners: Manufacturing, Tech Infrastructure, and Import-Heavy Corporates
Net energy importers stand out as the primary beneficiaries of the current macro setup. Economies like Japan, South Korea, and Taiwan—whose industrial output relies heavily on imported hydrocarbons—experience an immediate relief valve on operating expenditures. Lower energy input costs protect profit margins across semiconductor fabrication, automobile manufacturing, and heavy industrial machinery.
Furthermore, technology infrastructure providers and cloud compute architecture developers are seeing renewed capital inflows. With political clarity established in Washington, enterprise tech spending is expected to unfreeze, driving robust demand for advanced hardware, AI-integrated software solutions, and cross-border digital services.
The Losers: Upstream Energy Producers and High-Beta Commodity Plays
Conversely, upstream oil and gas exploration and production (E&P) companies face compressed valuation multiples. The slide in crude benchmarks directly impacts projected cash flows for independent producers and state-owned energy giants alike. Capital expenditure budgets within the fossil fuel sector are likely to face stringent re-evaluation, leading to subdued M&A activity in traditional oilfield services.
Additionally, emerging market currencies and sovereign debt instruments tied strictly to commodity exports are experiencing temporary downward pressure. Exporters of raw materials must navigate tighter financial conditions brought on by a strengthening US dollar, which increases the cost of servicing hard-currency debt.
People Also Ask (FAQ)
Why did Asian stocks rise following the US presidential election?
Asian equities rallied primarily due to the removal of major electoral uncertainty, which traditionally suppresses global risk appetite. Additionally, falling global oil prices provided a significant macroeconomic tailwind for energy-importing Asian economies, reducing industrial input costs and boosting corporate profit margins across manufacturing and technology sectors.
What caused the sharp decline in crude oil prices after the election?
Crude oil prices fell sharply as markets priced in expectations of increased domestic US energy production, supportive regulatory frameworks for fossil fuel extraction, and a broader recalibration of global energy demand. Traders anticipated higher supply volumes entering international markets under the incoming political administration.
How does a stronger US dollar impact Asian financial markets?
A stronger US dollar tends to create a mixed environment for Asian markets. While it enhances the competitiveness of export-driven economies by making local goods cheaper abroad, it can also put pressure on regional currencies, elevate imported inflation risks, and increase the debt-servicing costs for nations and corporations holding US dollar-denominated liabilities.
What are the implications for institutional investors managing cross-border portfolios?
Institutional allocators are leveraging this volatility to execute tactical sector rotations—moving away from high-beta energy commodities and into structurally sound technology, manufacturing, and consumer discretionary assets. Effective risk mitigation strategies now require close monitoring of central bank currency interventions and shifting trade policy frameworks.
Future Outlook: Strategic Milestones to Watch
As markets digest the immediate aftermath of the US election and the corresponding commodity correction, the medium-term trajectory will depend on several critical macroeconomic milestones. First, analysts will closely monitor the legislative priorities and cabinet appointments of the incoming US administration, particularly regarding international trade tariffs, corporate tax policies, and regulatory compliance mandates.
Second, upcoming meetings from major central banks—including the US Federal Reserve, the Bank of Japan, and the European Central Bank—will dictate the path of global liquidity and interest rate differentials. If persistent US economic resilience keeps interest rates elevated, foreign exchange volatility will remain a focal point for institutional portfolio managers.
Ultimately, disciplined capital allocation, rigorous risk mitigation, and a focus on enterprise fundamentals will differentiate successful market participants. While the initial post-election rally has injected vital momentum into Asian equities, navigating the subsequent quarters will require constant vigilance regarding geopolitical developments, energy market imbalances, and evolving macroeconomic indicators.