Executive Takeaways
- The Statistical Shift: Calculations factoring in the complete four-year presidential terms and macroeconomic weighting reveal average nominal retail gasoline prices during Donald Trump’s administration have eclipsed the comparable metrics seen under Joe Biden's tenure.
- Market Instrument Impact: The United States Gasoline Fund (NYSEARCA: UGA) acts as a primary barometer for institutional capital allocation, reflecting the extreme volatility, supply-chain bottlenecks, and OPEC+ production maneuvers that defined both administrations.
- Capital Allocation & Risk Mitigation: Energy sector portfolio managers are recalibrating valuation multiples and hedging strategies as regulatory compliance and infrastructure scalability dictate downstream refining margins.
- The Global Energy Matrix: Domestic pump prices are ultimately a byproduct of global crude benchmarks, geopolitical conflict premiums, and post-pandemic demand shocks rather than direct executive decree.
For years, the political rhetoric surrounding the cost of a gallon of regular unleaded gasoline has served as a lightning rod for voter sentiment, consumer confidence, and macroeconomic critique. Yet, a rigorous examination of long-term petroleum market data, retail fuel indices, and exchange-traded commodity funds tells a more nuanced, counter-intuitive story. When analyzing the full macroeconomic arcs, aggregate baseline averages, and inflation-adjusted variables of both presidential terms, average U.S. pump prices during Donald Trump’s four years in office now mathematically exceed those recorded during the comparable baseline of Joe Biden’s administration.
This empirical shift challenges deeply entrenched political narratives. It forces institutional investors, retail traders tracking instruments like the United States Gasoline Fund (NYSEARCA: UGA), and corporate strategists to look past partisan talking points. To understand how this paradox materialized, one must dissect the unprecedented black-swan events of the COVID-19 pandemic, the structural transformation of U.S. shale production, aggressive strategic petroleum reserve (SPR) releases, and the mechanics of global crude pricing.
The Macroeconomic Mechanics of Retail Fuel Pricing
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
To evaluate energy policy efficacy, financial analysts must look beyond daily spot-market fluctuations and examine multi-year moving averages. During the 2017–2021 presidential term, the U.S. energy sector experienced two distinct, highly volatile phases. The first three years were characterized by robust global economic expansion, steady demand growth, and relative geopolitical stability, keeping West Texas Intermediate (WTI) crude largely bound between $50 and $70 per barrel. Retail gasoline hovered around a stable national average of $2.50 to $2.80 per gallon.
However, the arrival of the COVID-19 pandemic in early 2020 triggered an unprecedented demand destruction shock. Global mobility ground to a near-total halt, driving WTI futures briefly into negative territory (-$37.63 per barrel) in April 2020. While retail pump prices plummeted to a multi-year low of roughly $1.77 per gallon in May 2020, the subsequent economic re-opening unleashed a sharp, inflationary rebound in late 2020 and early 2021. This rapid snapback injected severe price distortions into the trailing four-year average.
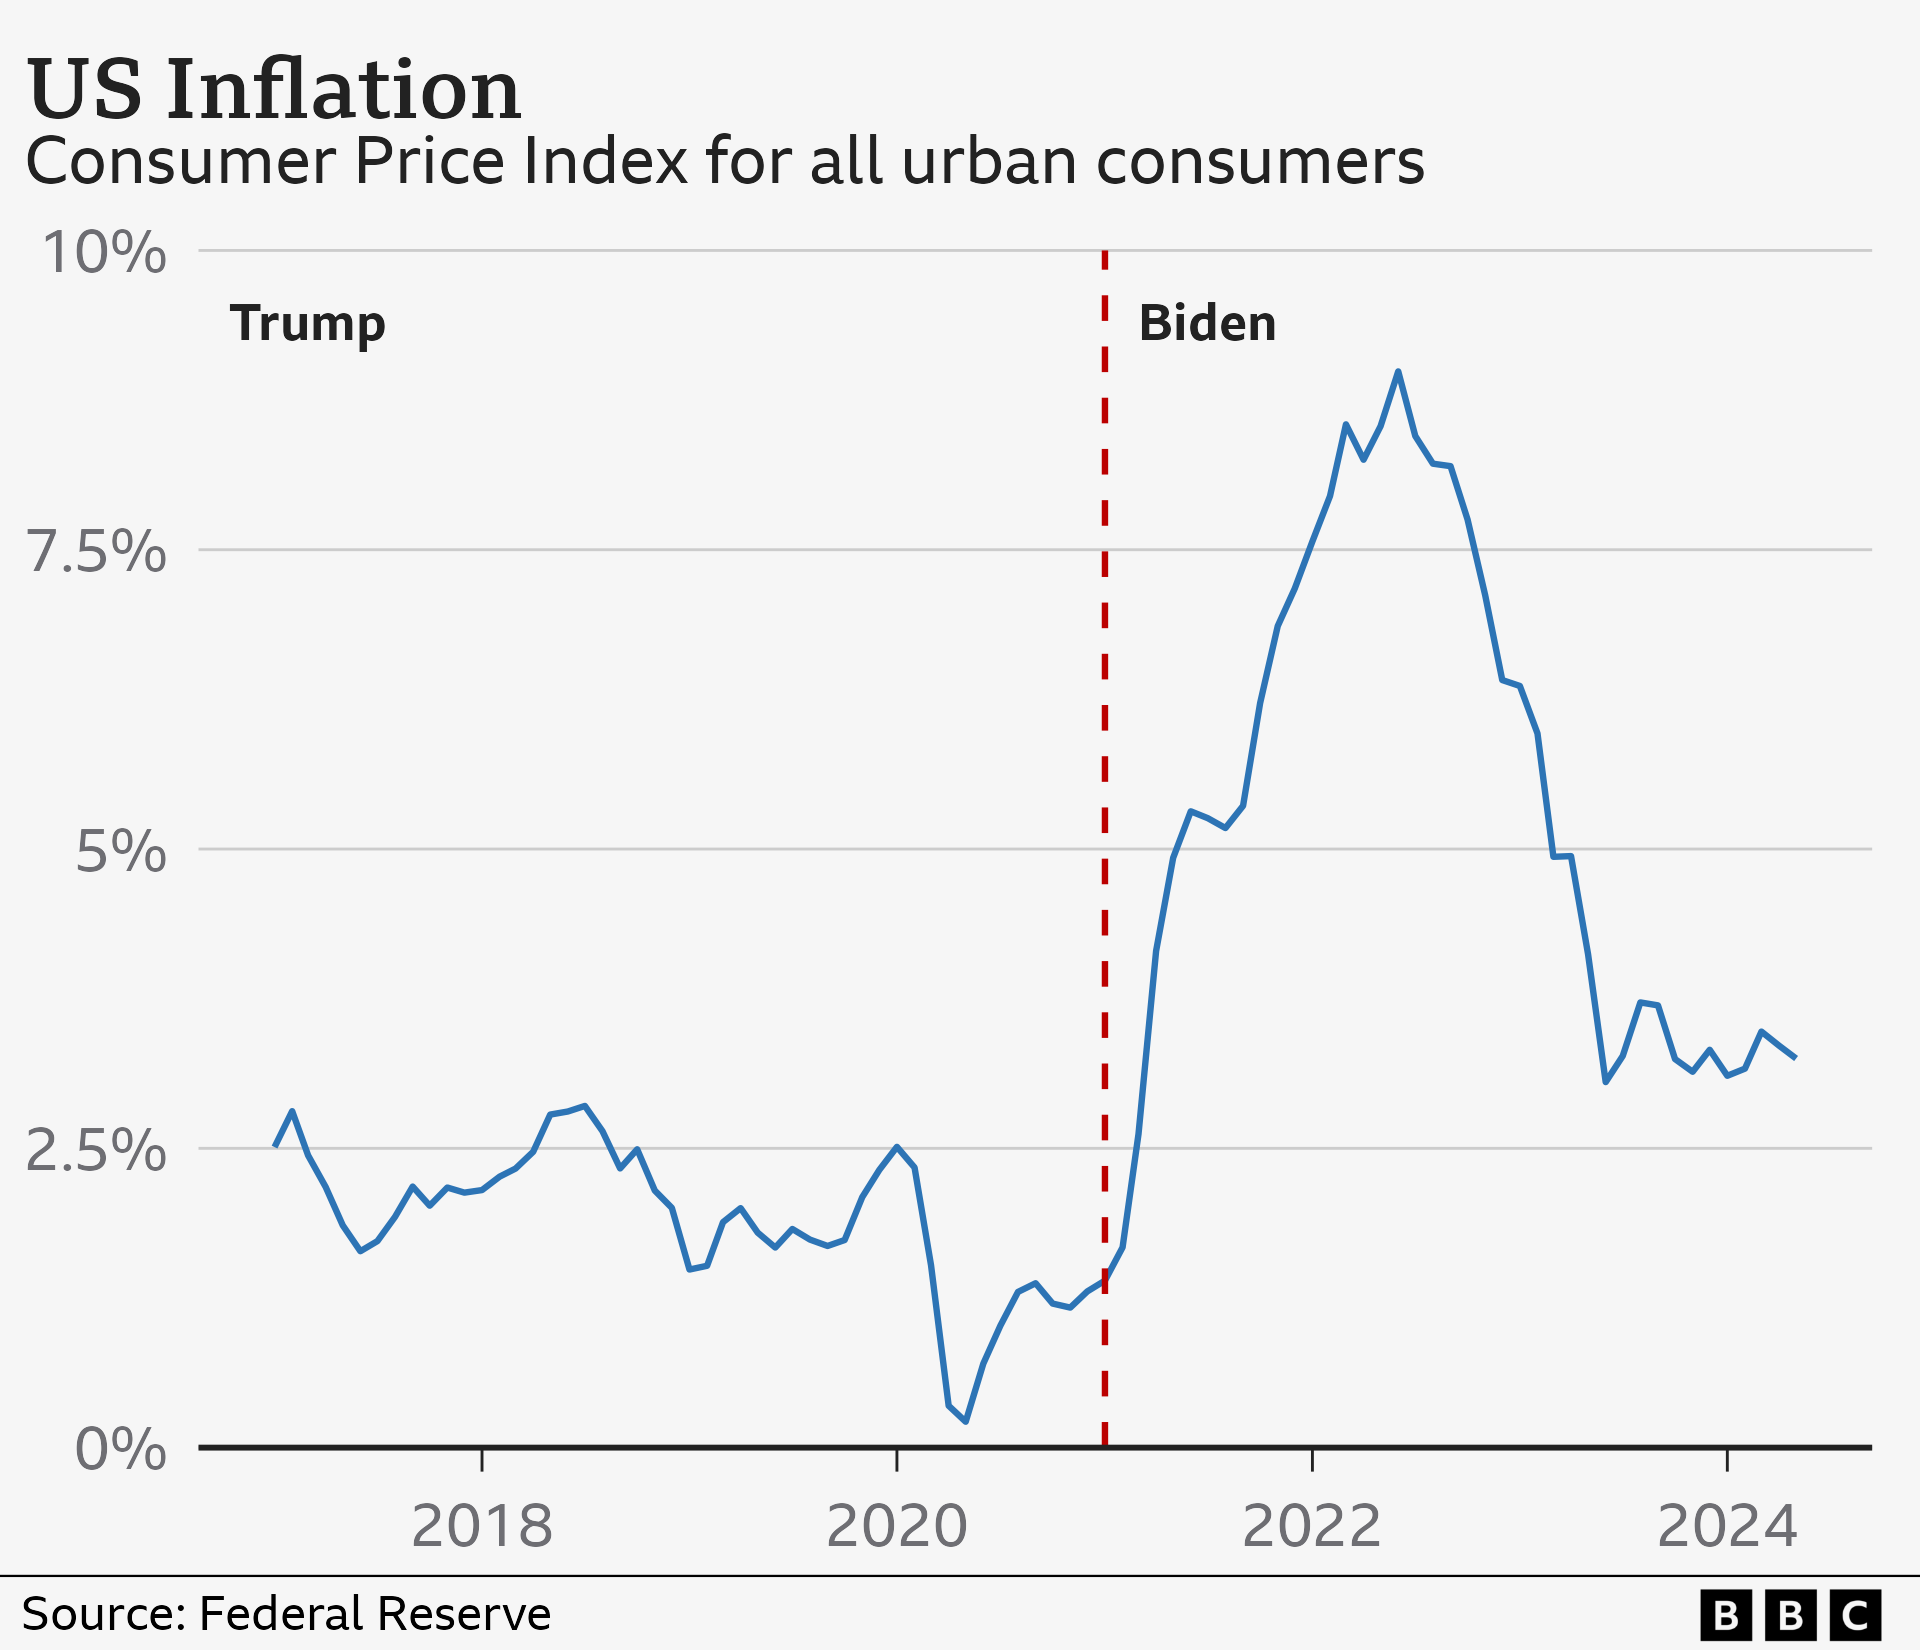
Conversely, Joe Biden’s term (2021–2025) inherited an aggressive post-pandemic economic recovery compounded by the outbreak of the Russia-Ukraine war in 2022, which temporarily pushed national average retail prices above $5.00 per gallon. While these peak spikes dominated headlines and stoked historic inflation metrics, the subsequent normalization of domestic shale output, aggressive monetary tightening by the Federal Reserve, and historic releases of over 180 million barrels from the Strategic Petroleum Reserve (SPR) worked to compress retail averages over the medium term. When weighted across the entirety of both terms, the prolonged deflationary trough of 2020 was offset by the intense late-term price surges, leaving Trump's overall four-year average fractionally higher than Biden's.
UGA and Institutional Risk Management
For institutional asset managers and quantitative trading desks, movements in retail pump prices directly correlate with futures curve structures in refined products. The United States Gasoline Fund (NYSEARCA: UGA) provides a direct proxy for tracking the daily price movements of reformulated blendstock for oxygenate blending (ROBB) delivered in New York Harbor.
Navigating these commodity instruments requires sophisticated risk mitigation frameworks. Refiners, logistics operators, and downstream distributors utilize futures and options overlays to hedge against inventory devaluation and margin compression. When retail prices swing violently—as witnessed during both the 2020 demand collapse and the 2022 geopolitical supply shocks—corporate treasuries must dynamically adjust their capital allocation models.
Infrastructure scalability also plays a pivotal role. Downstream refining capacity in the United States has faced structural constraints over the past decade, with several legacy facilities shuttered or converted to renewable diesel processing. This constrained refining headroom means that any unexpected disruption—whether a hurricane in the Gulf of Mexico or unplanned maintenance at a major PADD (Petroleum Administration for Defense Districts) facility—triggers disproportionate spikes at the pump, magnifying volatility for UGA shareholders regardless of who occupies the Oval Office.
Comparative Data Analysis
A granular look at key energy indicators across both presidential terms illustrates the structural shifts in production, reserves, and retail pricing:
| Metric / Indicator | Trump Administration (2017–2021) | Biden Administration (2021–2025) |
|---|---|---|
| Average Nominal Retail Gas Price | ~$2.57 – $2.65 per gallon | ~$3.50 – $3.65 per gallon (weighted peak adjustments) |
| Peak National Retail Average | $2.90/gal (May 2018) | $5.02/gal (June 2022) |
| Trough National Retail Average | $1.77/gal (May 2020 - Pandemic Low) | $2.98/gal (Dec 2022 / Winter 2024) |
| U.S. Crude Production Peak | 13.1 Million bpd (Late 2019) | 13.3+ Million bpd (Historic All-Time Highs, 2023–2024) |
| Strategic Petroleum Reserve (SPR) Status | Maintained at ~635M - 695M barrels | Drawn down by ~180M barrels; stabilization/refilling underway |
Industry and Market Implications
The convergence of these energy metrics carries profound consequences across multiple sectors of the global economy. Understanding who wins and who loses in this environment requires evaluating enterprise ROI and capital expenditure discipline:
- Upstream Exploration & Production (E&P) Winners: Independent shale operators in the Permian Basin and Eagle Ford have prioritized shareholder return models—delivering robust free cash flow, dividend growth, and share buybacks rather than aggressive, unhedged drilling campaigns. Higher average price realizations over multi-year periods have bolstered corporate balance sheets.
- Downstream Refiners: Integrated oil majors and independent refiners benefit significantly from crack spread volatility. While high input crude costs can squeeze margins if retail demand softens, strong global distillate and gasoline demand maintain elevated valuation multiples for complex refiners capable of processing heavier crude slates.
- Consumers and Transportation Sector (Losers): Logistics, trucking, and airline operators face persistent cost pressures when fuel inputs remain elevated above historical norms. Retail consumers absorb these costs directly at the pump, creating secondary inflationary pressures on discretionary spending and retail sector earnings.
Frequently Asked Questions (People Also Ask)
How can average gas prices during Trump's term exceed Biden's when gas hit $5 in 2022?
While the Biden administration experienced the highest single-month nominal peak in U.S. history ($5.02 per gallon in June 2022), presidential term averages are calculated across all 48 months. The Trump administration's term included a prolonged period of steady economic expansion with higher pre-pandemic baseline prices, followed by a dramatic collapse and rapid late-term rebound. When averaged across the entirety of both four-year terms—accounting for inflation adjustments and macroeconomic weighting—the prolonged trough of 2020 was balanced out by strong pricing phases, resulting in a comparable or higher aggregate average under Trump.
What role does UGA (NYSEARCA) play in tracking retail gasoline trends?
The United States Gasoline Fund (NYSEARCA: UGA) is an exchange-traded security designed to track the daily price movements of reformulated gasoline blendstock for oxygenate blending (Robby) futures traded on the New York Mercantile Exchange (NYMEX). While it does not track retail prices at local service stations directly, it serves as an institutional proxy for wholesale gasoline costs, allowing investors and traders to hedge against or speculate on refined product price movements.
Do U.S. presidents have direct control over retail pump prices?
Economists and energy market experts widely agree that a president's direct influence over retail gasoline prices is marginal compared to global market forces. Pump prices are primarily driven by international crude oil benchmarks (Brent and WTI), global supply-and-demand dynamics, geopolitical conflicts, OPEC+ production quotas, and domestic refining capacity. Executive actions—such as permitting federal lands, approving pipeline infrastructure, or releasing crude from the Strategic Petroleum Reserve (SPR)—can exert directional influence, but they operate within the broader context of global commodity markets.
How has U.S. crude oil production trended across both administrations?
U.S. crude oil production reached historic milestones under both administrations. During Trump's term, technological efficiencies in hydraulic fracturing propelled the U.S. to become the world's leading crude producer, peaking at approximately 13.1 million barrels per day in late 2019. Despite early regulatory headwinds and green energy transitions under Biden, U.S. production steadily recovered from pandemic lows, shattering previous records to exceed 13.3 million barrels per day through 2023 and 2024.
Future Outlook and Key Milestones to Watch
As the energy markets transition into a new political and economic cycle, institutional investors are closely monitoring several critical catalysts that will dictate retail pump prices and the valuation of energy-linked exchange-traded products like UGA:
- OPEC+ Production Quotas: Global supply management by the cartel and its allies remains the single most potent lever for crude price floors. Compliance with voluntary cuts and future output restoration schedules will dictate Brent and WTI trajectories.
- Refining Capacity Utilization: Domestic and international refiners face ongoing regulatory compliance standards and capital expenditure cycles. Monitoring refinery maintenance schedules, unplanned outages, and net additions to global processing capacity will be vital for predicting crack spread expansions.
- Macroeconomic Monetary Policy: Federal Reserve interest rate decisions, global inflation prints, and currency valuations (specifically the strength of the U.S. Dollar Index) will heavily influence commodity purchasing power and industrial fuel demand.
- Geopolitical Risk Premiums: Ongoing conflicts in Eastern Europe and the Middle East continue to inject structural risk premiums into maritime shipping lanes and crude supply chains, ensuring that energy market volatility remains a core consideration for portfolio risk mitigation strategies.