Executive Takeaways
- Dual-Engine Liquidity Influx: The Nasdaq Composite surged 1.9% on Thursday, June 18, 2026, spearheading a broader market rally orchestrated by aggressive institutional capital allocation into high-beta semiconductor equities and an abrupt deflationary impulse driven by diplomatic breakthroughs involving Iran.
- Semiconductor Valuation Multiple Expansion: Next-generation hardware manufacturers saw outsized inflows, fueled by enterprise ROI verification in generative inference deployment, alleviating multi-quarter concerns regarding high-performance compute architecture overcapacity.
- Crude Risk Premium Evaporation: Energy benchmarks experienced rapid multiple compression as credible signals of a diplomatic framework with Tehran alleviated long-tail maritime supply concerns in the Strait of Hormuz, dampening bond yield volatility.
- Systematic Re-leveraging: Quantitative Commodity Trading Advisors (CTAs) and risk-parity funds triggered automated buy programs, converting macro hedging unwinds into durable market liquidity across large-cap tech.
The Anatomy of a Breakout: Where Silicon Meets Geopolitics
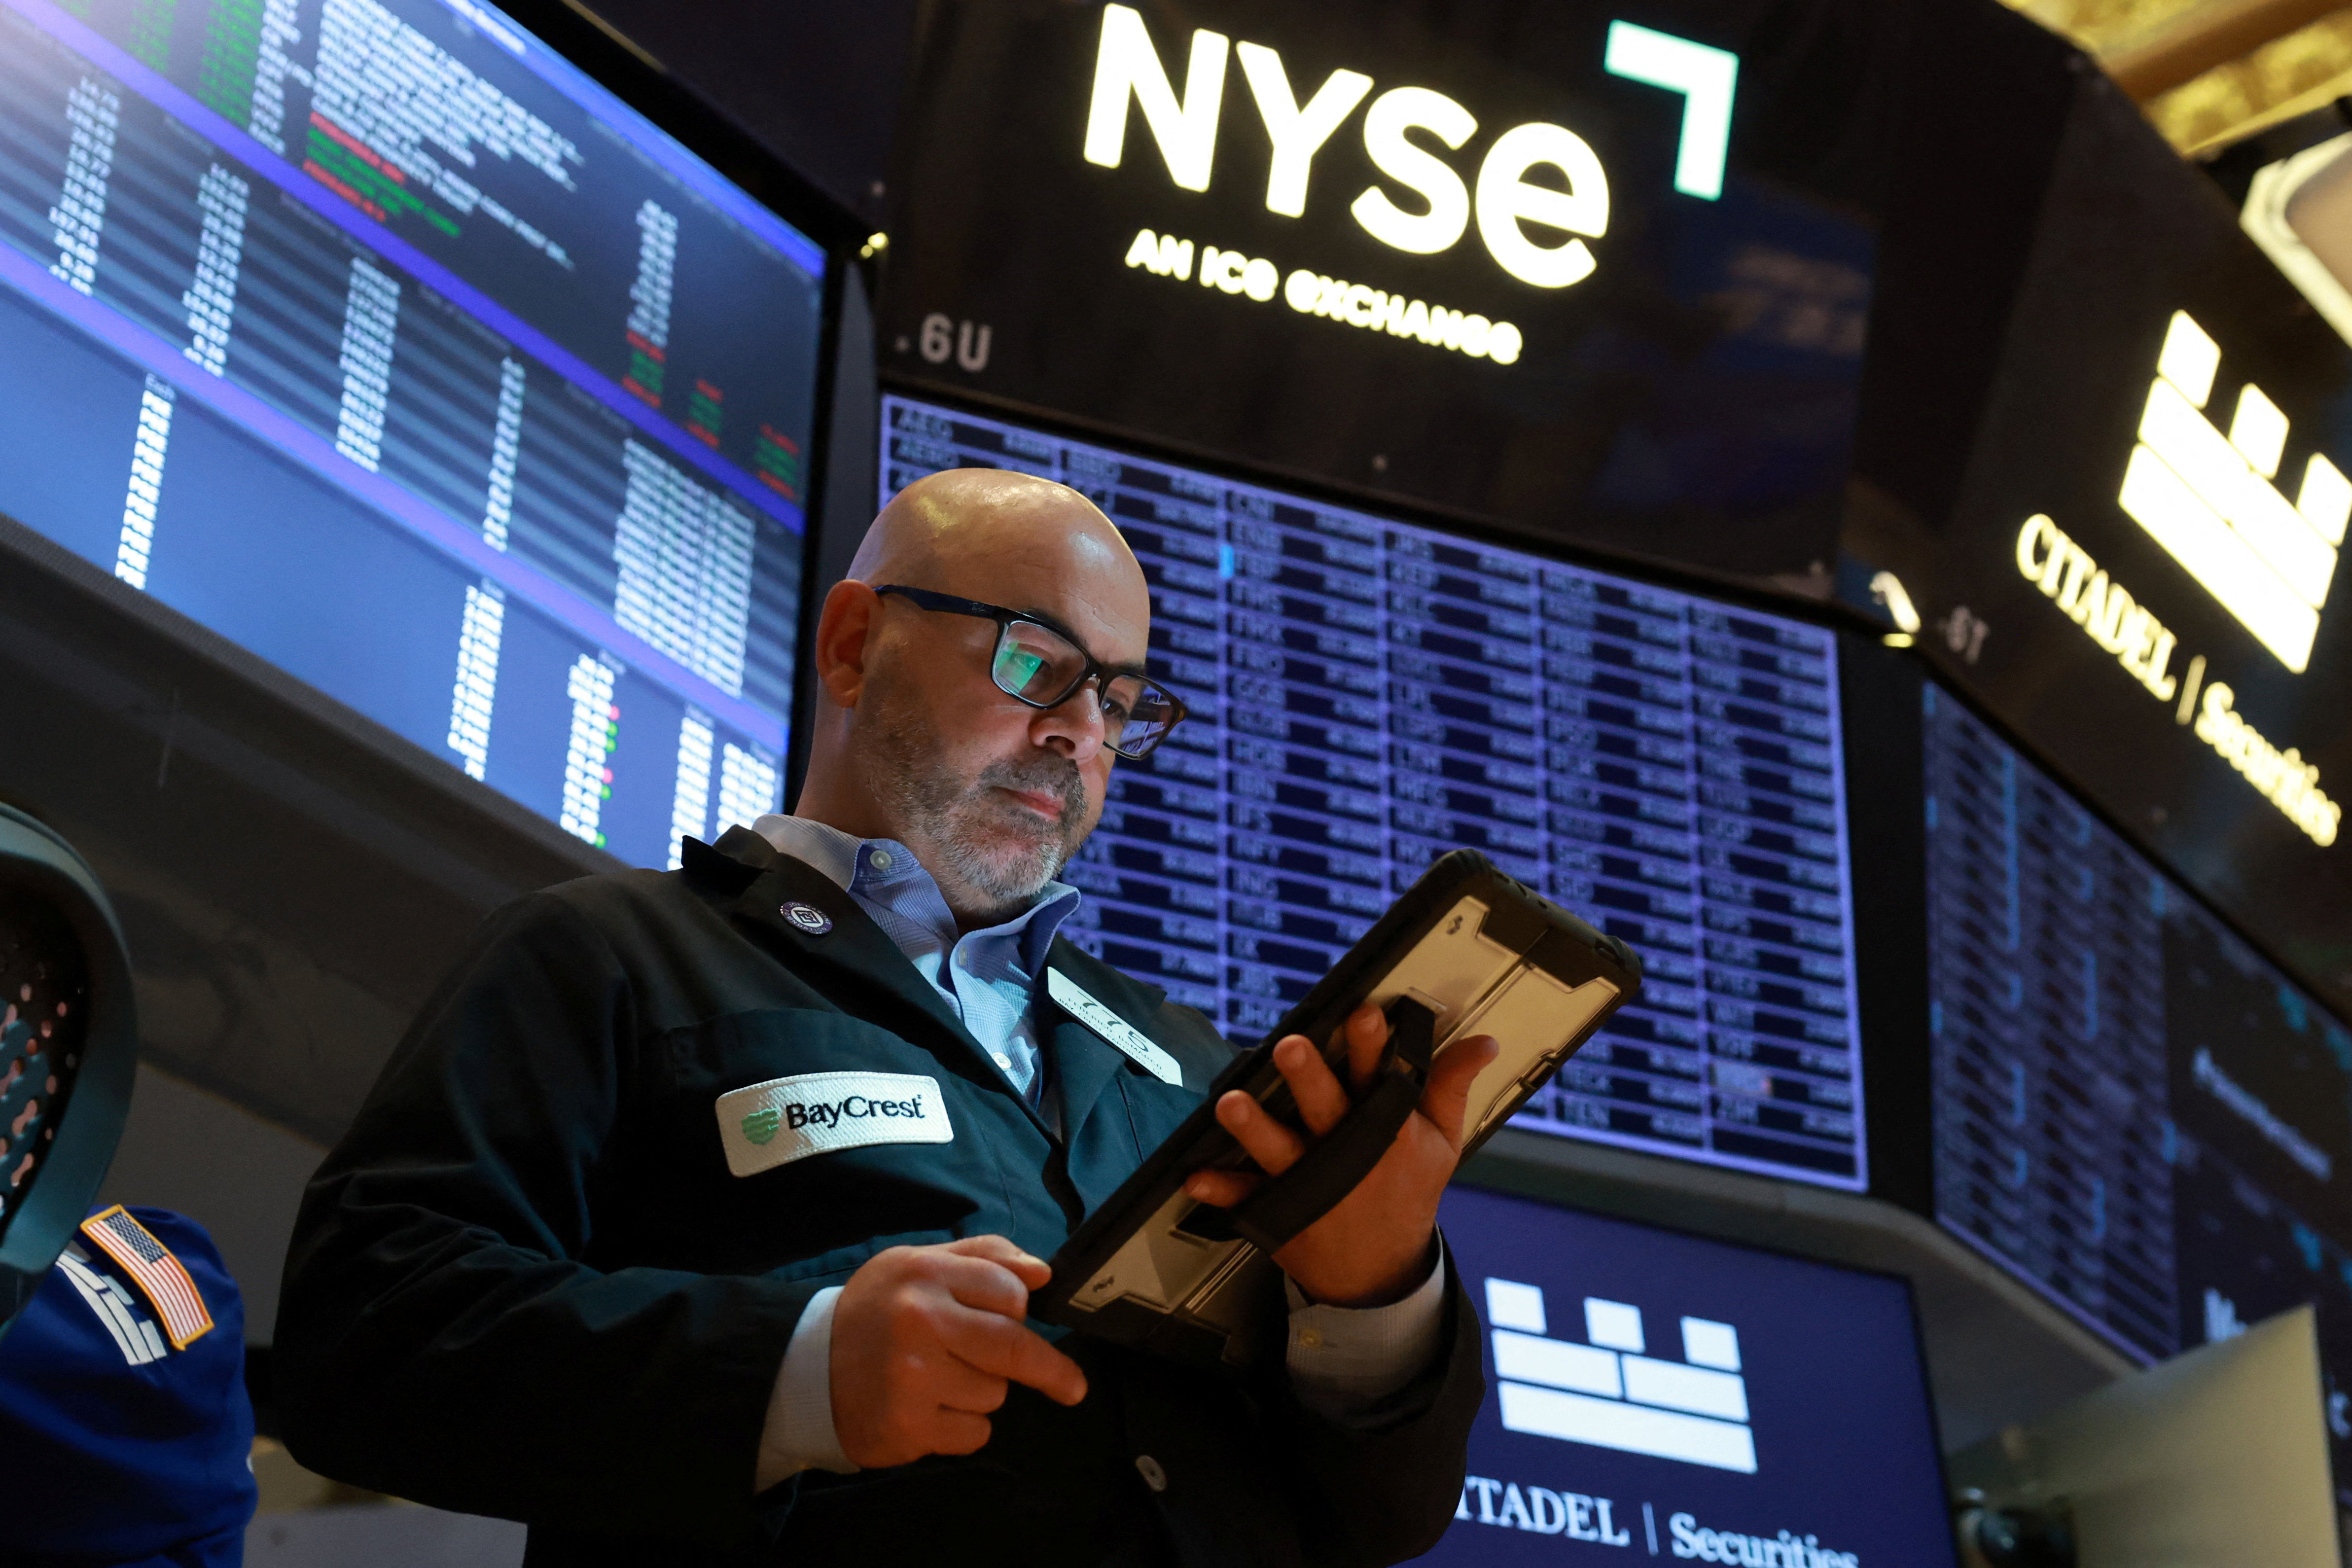
Trading desks across Lower Manhattan and the City of London witnessed a rare convergence of macro catalysts on Thursday. A synchronized rally lifted benchmark U.S. equities out of a month-long consolidation corridor, propelled by the intersection of structural tech momentum and an unexpected geopolitical tailwind.
The Nasdaq’s 1.9% advance was not an isolated technological short squeeze; it represented a broader recalibration of institutional risk models. For months, institutional portfolio managers have navigated a twin-front volatility regime: sticky headline inflation sustained by elevated crude oil benchmarks, juxtaposed against demanding valuation multiples across mega-cap tech infrastructure providers. That tension broke decisively as diplomatic cables hinted at an enforceable de-escalation pact with Iran, simultaneously triggering an unwind of oil-related tail-risk hedging and an immediate pivot back toward duration-sensitive assets.
With West Texas Intermediate (WTI) and Brent crude shedding risk premia, 10-year Treasury yields eased, providing cross-asset allocators the mathematical clearance to re-rate semiconductor cash flows. The dynamic underscores how sensitive modern equity valuations remain to energy-driven discount-rate volatility, particularly when high-multiple growth equities dominate capitalization-weighted benchmarks.
Inside the Silicon Resurgence: Infrastructure Scalability and Enterprise ROI
While macro sentiment established the foundation, the semiconductor complex provided the execution engine. Institutional demand concentrated heavily in specialized fabricators, advanced packaging monopolists, and custom ASIC designers. The rally signaled that the long-anticipated enterprise software spending pause has not infected core cloud compute architecture.
Industry field checks circulating among institutional buy-side firms earlier this week indicated that hyperscale cloud providers have expanded their forward multi-year capital expenditure commitments. Corporate balance sheets are increasingly allocating capital away from traditional enterprise IT maintenance toward accelerated server clustering, driven by competitive imperatives to compress model inference latency and improve infrastructure scalability.
Semiconductor capital equipment suppliers mirrored the rally, posting broad-based gains as supply-chain checks in East Asia verified that extreme ultraviolet (EUV) lithography backlogs remain structurally elevated. Tier-1 enterprise clients are demonstrating measurable return on investment (ROI) from customized machine-learning deployments, mitigating fears that high price-to-earnings multiples represented a speculative top. Instead, enterprise balance sheets are treating accelerated compute as non-discretionary capital allocation, insulating pure-play chip designers from cyclical consumer electronics weakness.
The Geopolitical Pivot: Unpacking the Iranian De-escalation Mechanism
The secondary catalyst—and the critical spark for risk-on rotation—arrived via geopolitical channels. Unconfirmed yet corroborated diplomatic reports suggested intermediate breakthroughs in indirect bilateral communications with Tehran. The emerging framework appears aimed at formalizing maritime transit stability in the Persian Gulf and re-establishing regulatory compliance checkpoints regarding uranium enrichment levels.
Energy traders responded by systematically pricing out the structural "Hormuz premium"—the estimated $8 to $12 per barrel structural buffer integrated into front-month contracts following months of heightened drone skirmishes and tanker interdictions. As front-month Brent tumbled, headline inflation expectations over the five-year forward horizon compressed in tandem.
This deflationary momentum fundamentally altered bond market mechanics. Fixed-income investors, who had priced in a persistent "higher-for-longer" baseline driven by energy input friction, adjusted their expectations. The subsequent stabilization in real yields gave institutional equity asset allocators license to rotate aggressively out of defensive utilities and cash-equivalent money market instruments back into structural high-beta equities.
Data and Metrics: Cross-Asset Performance Architecture
The velocity of Thursday's session is reflected in the cross-asset pricing metrics recorded across major derivative and spot execution venues:
| Metric / Asset Class | Session Close / Value | Day-Over-Day Change | Primary Macro Driver |
|---|---|---|---|
| Nasdaq Composite | 19,842.10 | +1.92% | Multiple expansion in enterprise semiconductor architecture |
| S&P 500 | 5,584.30 | +1.24% | Broad-based market liquidity injection; systematic CTA buying |
| Philadelphia Semiconductor (SOX) | 5,412.80 | +3.48% | Hyperscaler hardware capex durability; advanced packaging demand |
| Brent Crude (Front-Month) | $78.40 / bbl | -2.85% | Unwinding of geopolitical risk premium on Iran negotiation leaks |
| U.S. 10-Year Treasury Yield | 4.21% | -7.5 bps | Deflationary energy feedback loop easing terminal Fed expectations |
| Cboe Volatility Index (VIX) | 12.85 | -1.42 | Aggressive liquidation of out-of-the-money downside tail hedges |
Industry & Market Implications: Winners, Losers, and Capital Reallocation
The session’s decisive pivot has profound implications for sectoral leadership through the remainder of the quarter:
The Structural Winners
- Semiconductor Foundries and Fabless Designers: Enterprises operating at the leading edge of wafer fabrication and advanced sub-3nm node production are extracting exceptional gross margins. These firms benefit directly as generative inference infrastructure shifts from centralized hyperscaler testbeds to distributed enterprise private clouds.
- Capital-Intensive Growth Tech: Mid-tier cloud software vendors, previously squeezed between contracting enterprise IT budgets and elevated debt-refinancing hurdles, suddenly find relief in loosening financial conditions and narrowing corporate credit spreads.
- Aviation and Transportation: Airlines, marine freight logistics, and overland logistics companies reap double benefits: reduced operational fuel expenditures and improving macroeconomic certainty that preserves consumer demand.
The Vulnerable Pockets
- Traditional Exploration & Production (E&P): Upstream energy producers whose cash-flow projections and share-buyback authorizations were modeled on sustained $85-plus crude face compressed valuation multiples and downward revisions to free cash flow yields.
- Geopolitical Volatility Arbitrageurs: Systematic macro strategies that established concentrated long positions in energy futures and short-duration volatility products suffered sharp intraday stop-outs, driving forced liquidation of hedge positions.
Frequently Asked Questions (People Also Ask)
Why do semiconductor equities rally when crude oil prices decline?
The correlation operates through interest rate mechanisms. Leading semiconductor and technology stocks carry significant "duration"—meaning their intrinsic valuations rely heavily on corporate earnings projected far into the future. High crude oil prices feed into headline inflation, compelling central banks to raise or sustain elevated baseline policy rates, which increases the discount rate applied to those future corporate cash flows. When geopolitical risks ease and oil slides, discount rates compress, directly driving valuation multiple expansion in high-growth chipmakers.
How does the Iran situation directly affect financial asset pricing?
Iran commands strategic leverage over the Strait of Hormuz, an energy choke point through which approximately 20% of global petroleum liquid consumption transits daily. Any diplomatic breakthrough reduces the structural probability of supply disruptions, shipping tanker attacks, or asymmetric regional escalation. This alleviates the need for commodity trading houses and institutional portfolio managers to price in catastrophic supply bottlenecks, allowing cross-asset risk premiums to reset downward.
Is the current semiconductor rally supported by enterprise fundamentals?
Yes. In contrast to speculative liquidity bubbles, institutional tracking of semiconductor order books indicates that forward commitments are supported by verifiable enterprise ROI. Enterprise deployments have graduated from experimental research projects into mission-critical workflow automation, customer service integration, and algorithmic risk mitigation. Hyperscalers continue to demonstrate robust free cash flow profiles capable of self-funding multi-billion-dollar infrastructure scalability buildouts without relying on punitive debt markets.
What are the primary structural risks to this market rally?
The primary threats include diplomatic fragility—where sudden setbacks in Middle Eastern negotiations could instantly re-inject an energy risk premium into oil contracts—and regulatory compliance interventions. Ongoing antitrust and national security reviews regarding semiconductor export controls to strategic jurisdictions continue to present asymmetric volatility vectors for global supply-chain ecosystems.
Future Outlook: Critical Milestones and What to Watch
To sustain this breakout, institutional investors will require verification across three core pillars over the next sixty to ninety days.
First, the market must see tangible operational results from the reported diplomatic openings with Tehran. Historically, early-stage diplomatic frameworks in the Persian Gulf face intense structural friction from regional hardliners. If verifiable inspections or sanction-relief timetables fail to materialize, algorithmic crude traders will swiftly rebuild the geopolitical risk premium, snapping energy prices higher and re-tightening broad financial conditions.
Second, the impending corporate earnings cycle will shift attention from high-level guidance to rigorous unit economics. Investors will closely scrutinize whether corporate buyers are expanding cloud compute architecture spending at the expense of traditional headcount and real estate, or if the overall corporate IT envelope is truly expanding. Margin compression among tier-2 hardware suppliers could indicate that pricing power remains concentrated solely in top-tier semiconductor monopolists.
Finally, central bank policy cadence remains the ultimate arbiter. If low energy input costs translate into benign monthly Core PCE and CPI prints through the remainder of the summer, monetary policymakers will gain the macro flexibility needed to formalize an accommodative interest rate path. For Wall Street, the intersection of technological transformation and lower energy friction has created a potent liquidity vector—one that market participants will vigorously defend until real-world data proves otherwise.