Executive Takeaways
- The Seismic Shift: Internal telemetry and independent traffic analytics indicate OpenAI’s ChatGPT has captured approximately 20% of Google’s legacy search volume, transforming consumer discovery from keyword queries to generative dialogue.
- Capital Allocation & Infrastructure: The staggering computational demand of real-time LLM inference has forced hyperscalers to reallocate tens of billions in capital expenditures, pressuring near-term cloud operating margins.
- Monetization Realities: While Google protects its moat via high-margin programmatic auction architecture, OpenAI faces acute pressure to prove enterprise ROI through subscription models and impending native advertising integrations.
- Market Revaluation: Wall Street valuation multiples for Alphabet (NASDAQ: GOOGL) are undergoing rigorous stress-testing as institutional investors price in long-term risk to search-engine-result-page (SERP) duopoly economics.
For more than two decades, the modern internet economy has operated under an immutable law of digital gravity: web traffic begins and ends with Google. Mountain View’s search engine has acted as the ultimate gatekeeper of global commerce, capturing trillions of intent-driven queries and converting them into a high-margin advertising engine of unprecedented proportions. Today, that foundational architecture is experiencing its most aggressive structural challenge since the dot-com era.
According to emerging telemetry, proprietary data models, and industry insights, OpenAI’s ChatGPT has effectively captured roughly 20% of Google’s traditional search volume. What began as a parlor trick of predictive text has matured into a formidable intent-aggregation platform. For enterprise strategists, institutional investors, and cloud compute architects, this milestone is not merely a vanity metric; it represents a tectonic redistribution of digital attention, user intent, and capital allocation.
The Anatomy of the Disruption: From Blue Links to Conversational Synthesis
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
To understand the gravity of a 20% market share erosion, one must dissect the mechanics of modern information discovery. Google’s enduring dominance rested on the Search Engine Results Page (SERP)—a meticulously optimized marketplace of blue hyperlinks, sponsored ads, and algorithmic rankings. Users exchanged precision of intent for a list of disparate sources, navigating multiple tabs to synthesize answers themselves.
ChatGPT short-circuits this friction-heavy workflow entirely. By leveraging advanced transformer architectures, reinforcement learning from human feedback (RLHF), and real-time web grounding, OpenAI delivers synthesized answers instantly. When a user bypasses Google to ask ChatGPT for complex medical differential diagnoses, comparative software evaluations, or multi-step travel itineraries, they are executing a structural migration away from keyword-based indexing toward cognitive computing.
This shift introduces profound risk mitigation challenges for legacy publishers and brands. When an LLM directly answers a query rather than directing traffic downstream via a link, publisher referral models collapse. Consequently, media conglomerates and e-commerce giants are forced to re-evaluate their digital strategies, weighing the necessity of AI bot-scraping allowances against the loss of direct-to-consumer monetization.
The Infrastructure Bottleneck and Capital Expenditure Super-Cycle
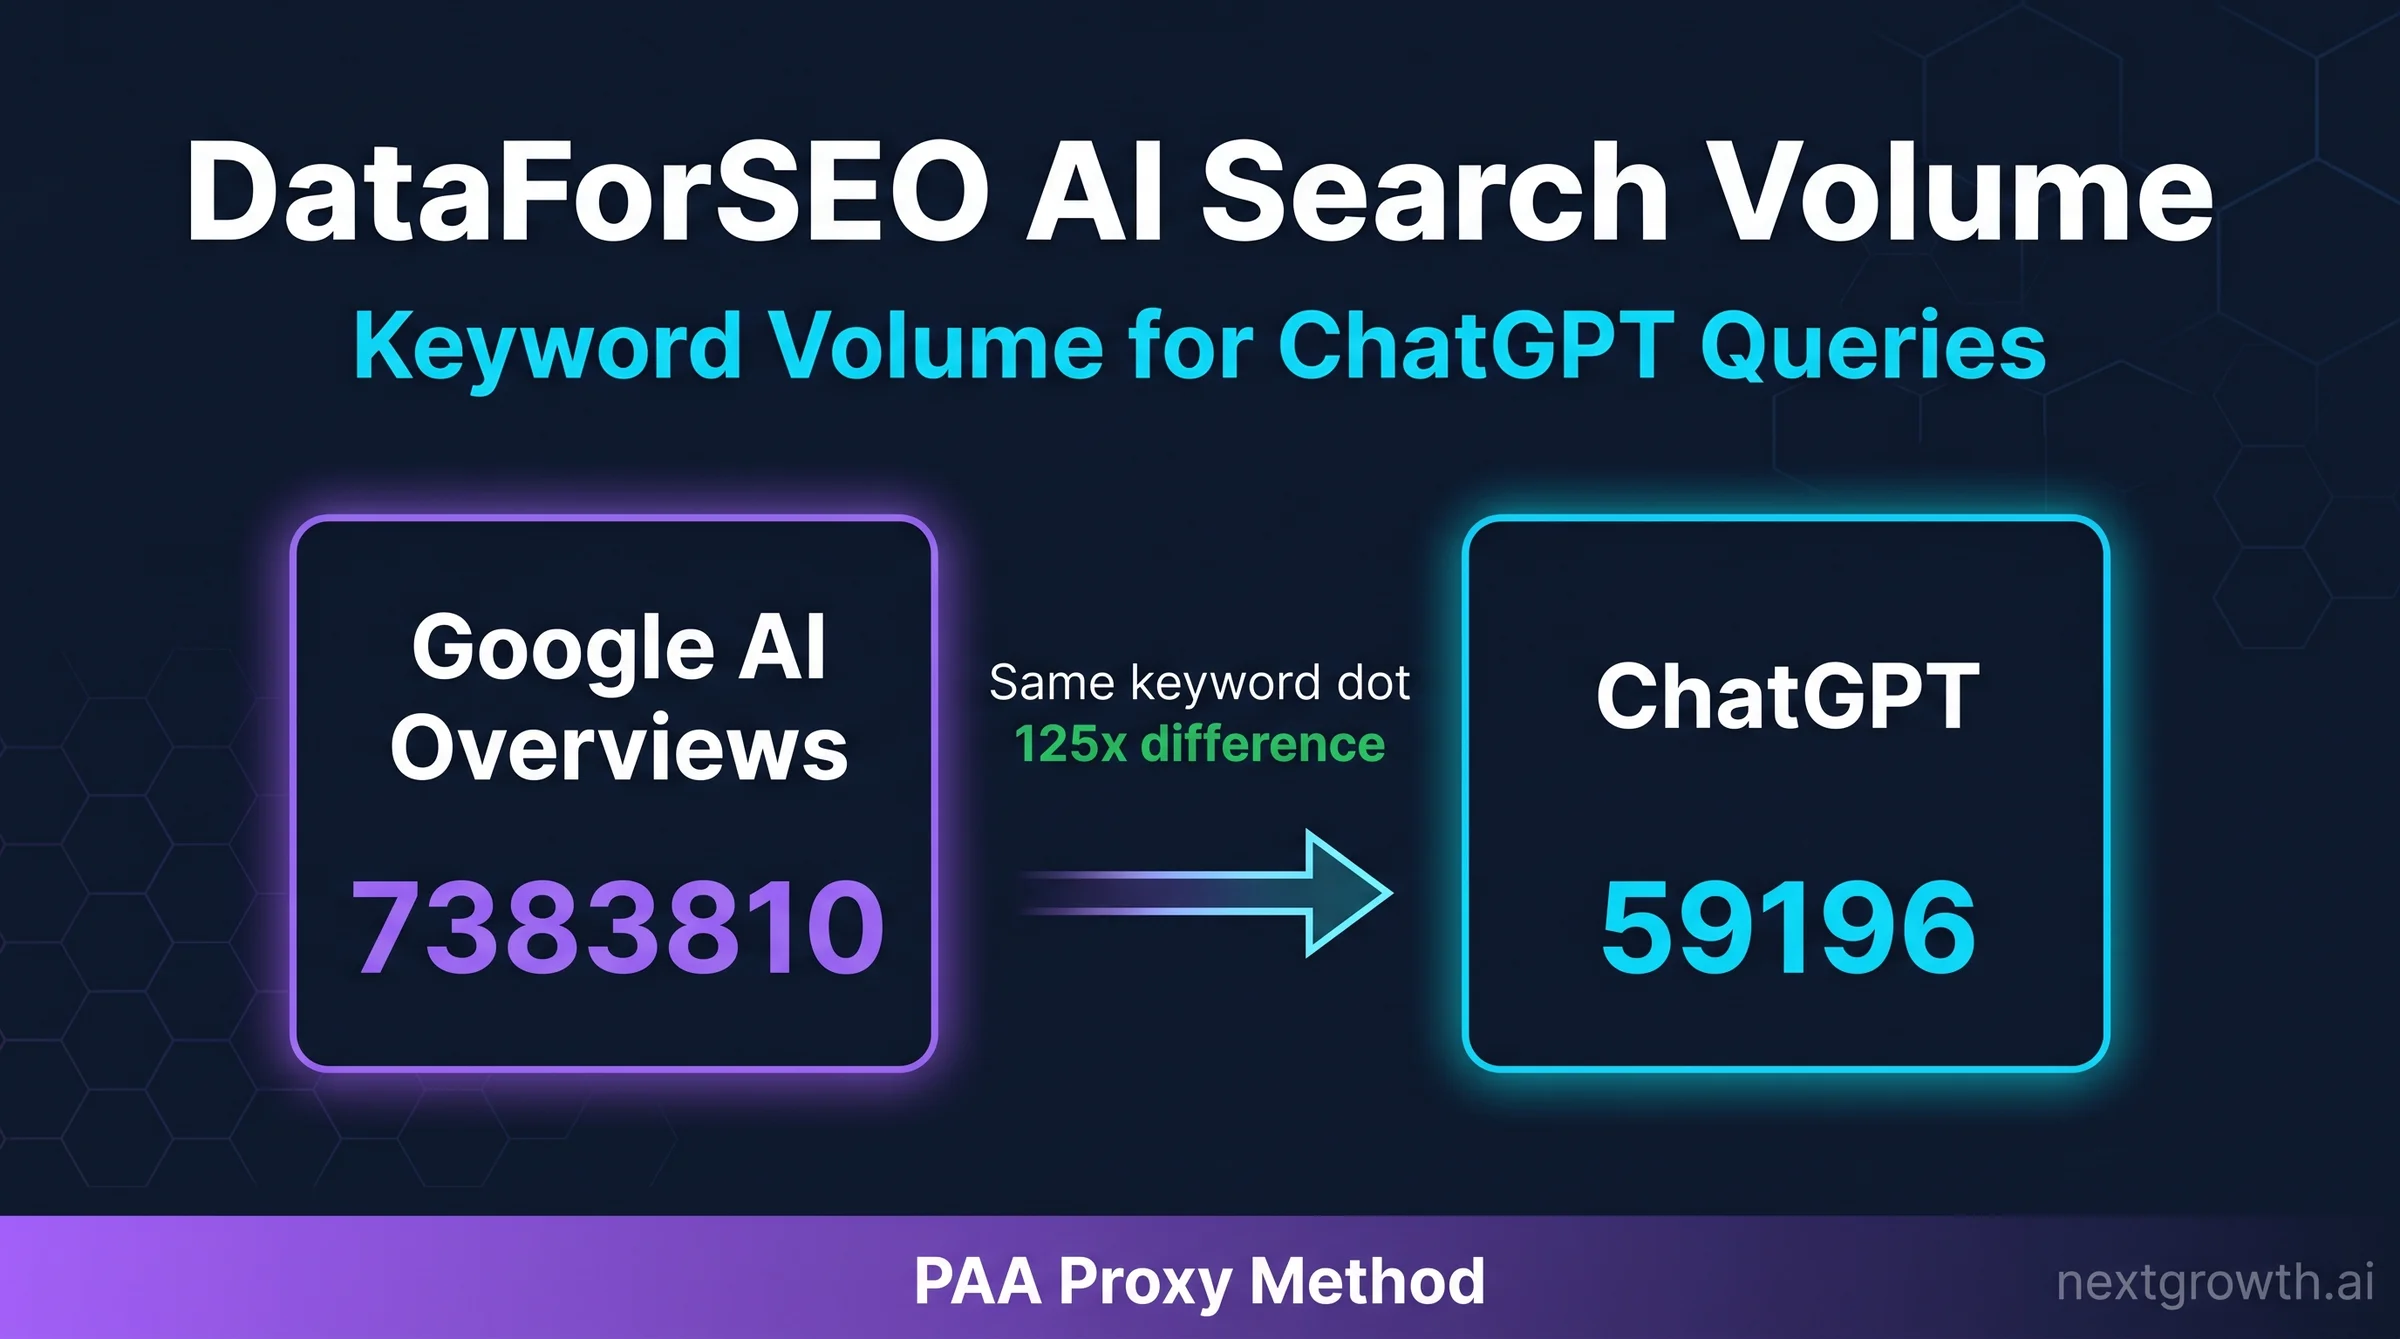
Capturing one-fifth of Google’s search volume is an extraordinary triumph of product-market fit, but it exposes OpenAI and its primary infrastructure backer, Microsoft, to unprecedented operational hurdles. Unlike static web indexing—which relies on pre-computed inverted indices that scale with low marginal cost—generative AI inference requires massive, continuous GPU compute cycles for every single user query.
The capital expenditure (CapEx) required to sustain this level of throughput is staggering. Industry analysts estimate that servicing billions of conversational queries daily demands multi-gigawatt data center footprints, specialized silicon (such as NVIDIA’s Hopper and Blackwell architectures), and sophisticated liquid-cooling topologies. This dynamic has triggered a massive capital allocation race across Wall Street:
- Cloud Compute Architecture: Hyperscalers are dedicating historic portions of their operational budgets to secure proprietary silicon and construct dedicated power grids.
- Energy Infrastructure Constraints: The race for clean, uninterrupted baseload power to feed AI data centers has forced tech conglomerates to invest directly in nuclear and renewable energy facilities.
- Margin Compression: Unlike Google’s hyper-efficient query-serving infrastructure, LLM inference currently operates at significantly lower gross margins, pressing executive teams to justify near-term cash burn against long-term market capture.
Comparative Market Dynamics: OpenAI vs. Alphabet
To contextualize the magnitude of this technological face-off, the following matrix details the fundamental operational, financial, and structural divergences between Alphabet’s search empire and OpenAI’s generative ecosystem.
| Metric / Dimension | Alphabet (Google Search) | OpenAI (ChatGPT Ecosystem) |
|---|---|---|
| Core Interaction Model | Keyword indexing & programmatic SERP | Conversational synthesis & multi-modal reasoning |
| Monetization Engine | High-margin programmatic auction ads (Google Ads) | Tiered SaaS subscriptions & emerging enterprise APIs |
| Infrastructure Cost Structure | Mature, highly optimized, low marginal cost per query | Intensive GPU inference, high capital expenditure |
| Regulatory & Compliance Exposure | Antitrust scrutiny, monopoly investigations | Copyright disputes, data privacy, AI safety legislation |
| Estimated Search / Intent Volume Share | ~80% Global Dominance | ~20% and rapidly expanding in high-intent cohorts |
Industry & Market Implications: Who Wins, Who Loses
The erosion of Google’s volume exclusivity by 20 percentage points has immediate macroeconomic consequences across global technology and financial markets.
The Winners: Enterprise software integrators, specialized AI infrastructure providers, and hardware manufacturers sit squarely in the benefactor seat. Companies building domain-specific retrieval-augmented generation (RAG) systems are experiencing record venture inflows and enterprise adoption. Furthermore, consumers benefit from hyper-personalized, zero-friction synthesis that eliminates the cognitive fatigue of traditional web trawling.
The Losers: Traditional digital marketing agencies heavily reliant on Search Engine Optimization (SEO) and programmatic keyword bidding face an existential identity crisis. As zero-click searches increase and conversational interfaces intermediate the consumer journey, legacy customer acquisition funnels are losing efficacy. Additionally, Alphabet faces sustained valuation multiple compression as institutional investors price in a structural ceiling on future advertising revenue growth.
Regulatory compliance also enters a volatile new phase. As OpenAI absorbs an increasing share of global information synthesis, antitrust regulators in the European Union and the United States are pivoting their crosshairs from Mountain View to San Francisco, scrutinizing data acquisition practices, model transparency, and monopolistic tendencies in foundational AI.
Frequently Asked Questions (People Also Ask)
How is ChatGPT’s search volume share calculated?
Market research firms, web telemetry providers, and internal server-load analytics estimate ChatGPT’s market share by measuring active daily conversational queries, unique user retention, and browser extension bypass rates relative to total global search engine queries logged by comScore, StatCounter, and internal industry benchmarks.
Does ChatGPT feature advertising like Google Search?
Currently, ChatGPT operates primarily on a subscription revenue model (ChatGPT Plus, Team, and Enterprise) alongside developer API usage fees. However, industry insiders widely anticipate the introduction of native, contextual product recommendations and sponsored conversational placements as OpenAI seeks to match Google’s formidable advertising monetization efficiency.
What are the primary technical bottlenecks preventing ChatGPT from capturing 50% or more of search volume?
The primary constraints are raw compute capacity, server-side inference costs, latency limitations, and hallucination mitigation. Scaling generative AI to handle 100% of global daily queries requires unprecedented silicon manufacturing output, multi-billion-dollar power infrastructure investments, and algorithmic breakthroughs to reduce the cost-per-query.
How is Google responding to this competitive threat?
Google has aggressively integrated generative AI into its core SERP via AI Overviews, optimized its proprietary Gemini model family across Android and Workspace ecosystems, and accelerated hardware cost-efficiencies through custom Tensor Processing Units (TPUs) designed to defend its advertising moat.
Future Outlook: Milestones and Strategic Horizons
As the technological landscape barrels toward the next fiscal cycle, industry stakeholders must monitor several critical inflection points. The 20% threshold is not a static ceiling; it is a bridgehead in a multi-front war for digital dominance. Watch for the following key catalysts over the next twelve to twenty-four months:
- Monetization Evolution: Watch for OpenAI to roll out structured, performance-based advertising or transactional e-commerce checkout frameworks directly within conversational threads.
- Silicon Independence: Look for strategic shifts in hardware partnerships as both OpenAI and Alphabet develop proprietary silicon to bypass NVIDIA’s pricing power and reduce inference overhead.
- Regulatory Interventions: Anticipate stricter legislative frameworks governing AI data ingestion, copyright indemnification, and algorithmic bias, which could fundamentally alter the cost structure of training and deploying large language models.
Ultimately, the era of unmitigated keyword search dominance has officially drawn to a close. The battle for the digital mindshare of humanity is no longer fought with blue links and auction bids, but with predictive intelligence, computational supremacy, and conversational trust.