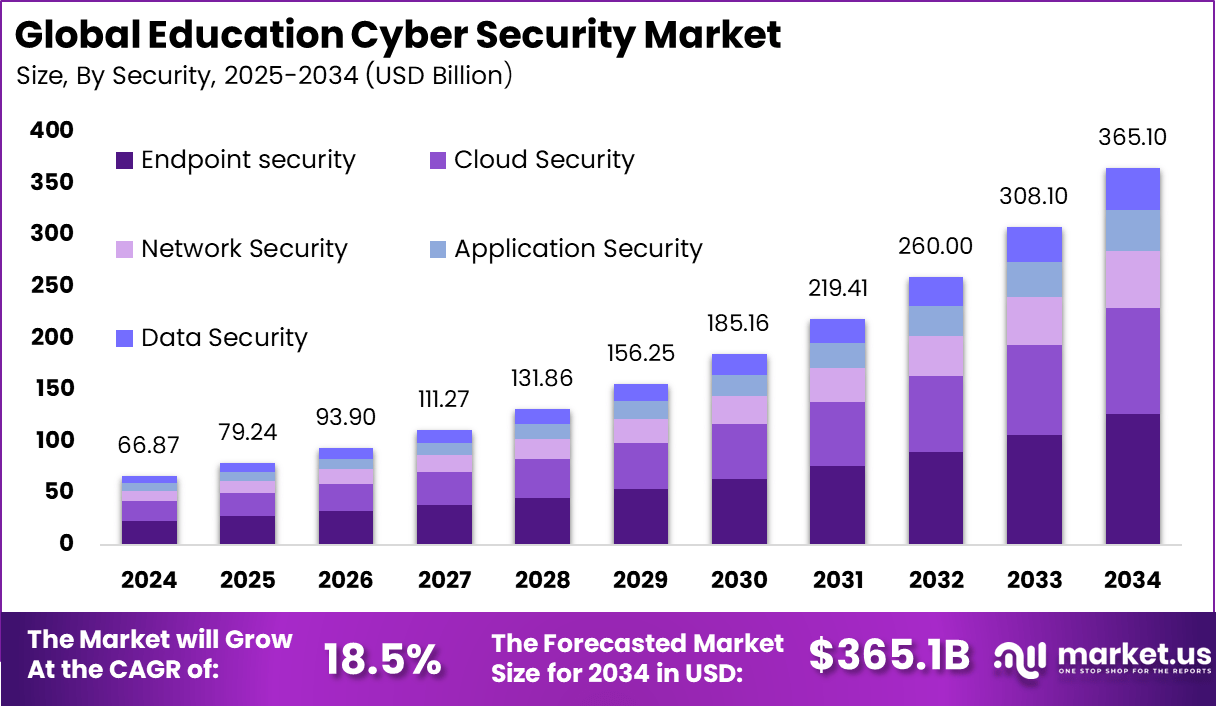
NEW YORK — In an era defined by geopolitical friction, algorithmic warfare, and the relentless migration of enterprise workloads to hybrid cloud environments, corporate balance sheets are undergoing a profound structural re-evaluation. A landmark market intelligence study distributed via GlobeNewswire reveals that the global cybersecurity sector is hurtling toward a staggering valuation of US$ 552.35 billion by 2031, expanding at a compound annual growth rate (CAGR) of 13.8%. This multi-decade capital supercycle reflects not merely an incremental line-item increase in corporate IT budgets, but an existential re-engineering of how sovereign states, multinational corporations, and critical infrastructure operators allocate capital to defend against systemic digital collapse.
For institutional investors, venture capitalists, and C-suite executives navigating complex regulatory landscapes, this valuation milestone marks a pivotal inflection point. As threat actors leverage artificial intelligence, polymorphic malware, and supply-chain vulnerabilities to bypass legacy defenses, the economics of information security have shifted from a reactive operational expense to a core driver of enterprise valuation, risk mitigation, and market liquidity.
Executive Takeaways
- Valuation Trajectory: The global cybersecurity market is projected to reach US$ 552.35 billion by 2031, sustaining a robust 13.8% CAGR from its baseline assessment period.
- Catalytic Drivers: Accelerated cloud compute architecture adoption, heightened geopolitical cyberespionage, and stringent global regulatory compliance frameworks (such as DORA, NIS2, and SEC cyber disclosure rules) are forcing unprecedented capital allocation.
- Geographic Hegemony: North America retains dominant market share, fueled by deep-pocketed enterprise buyers and advanced venture capital ecosystems, while the Asia-Pacific region exhibits the fastest regional growth velocity.
- Investment Implications: Consolidation is accelerating across valuation multiples as platform players swallow niche point-solution vendors, creating prime targets for private equity buyouts and strategic mergers.
The Catalytic Anatomy of a $552 Billion Market
To understand the sheer velocity of capital flooding the cybersecurity sector, one must examine the macroeconomic headwinds and technological shifts reshaping the digital enterprise. The contemporary threat landscape is no longer populated solely by isolated hackers or financially motivated ransomware syndicates. Today, enterprise networks face persistent, state-sponsored APTs (Advanced Persistent Threats) capable of weaponizing zero-day exploits across complex software supply chains.
This escalating threat matrix has forced boards of directors to completely overhaul capital allocation strategies. Historically relegated to the basement of IT departments, Chief Information Security Officers (CISOs) now command direct access to executive committees, wielding significant influence over corporate governance, infrastructure scalability, and merger-and-acquisition due diligence. When evaluating enterprise ROI, boards increasingly view robust security architecture not as a cost center, but as a non-negotiable insurance policy against catastrophic brand erosion, regulatory fines, and operational paralysis.
Simultaneously, the mass migration of enterprise data lakes and ERP systems to multi-cloud environments (spanning AWS, Microsoft Azure, and Google Cloud) has obliterated traditional perimeter-based security models. The perimeter is no longer a corporate firewall; it is the identity of every remote employee accessing corporate applications from personal devices across unsecured domestic Wi-Fi networks. This paradigm shift has triggered massive enterprise demand for Zero Trust Architecture (ZTA), Extended Detection and Response (XDR), and cloud-native application protection platforms (CNAPP).
Regulatory Compliance as a Demand Multiplier
While malicious actors provide the immediate catalyst for defense spending, regulatory mandates act as the permanent engine of demand. Across major global jurisdictions, regulatory bodies have transformed cybersecurity from a best-practice recommendation into a legally enforceable mandate with severe personal liability for executive leadership.
In the United States, the Securities and Exchange Commission (SEC) enacted stringent rules requiring public companies to disclose material cybersecurity incidents within four business days and provide annual transparency regarding their risk management, strategy, and governance. Across the Atlantic, the European Union's NIS2 Directive and the Digital Operational Resilience Act (DORA) impose rigorous accountability on financial institutions and critical infrastructure providers, threatening non-compliant entities with sweeping financial penalties running into the millions of euros or a percentage of global annual turnover.
These legal frameworks have eliminated executive complacency. Corporate legal counsels and risk committees are mandating continuous compliance auditing, automated threat intelligence feeds, and rigorous third-party vendor risk assessments. Consequently, enterprise spending on compliance-driven security tools has become entirely inelastic, insulating the sector against broader macroeconomic downturns and tightening monetary policies.
Verified Market Metrics & Projections
A granular examination of the data underscores the structural momentum underpinning the 13.8% CAGR projection through 2031. The following matrix outlines the core financial parameters, regional trajectories, and primary growth catalysts defining the current market cycle:
| Metric / Parameter | Market Status & Projection Data | Primary Growth Drivers |
|---|---|---|
| Projected Market Size (2031) | US$ 552.35 Billion | Surging enterprise reliance on cloud infrastructure, AI-driven threat automation, and mandatory regulatory compliance. |
| Compound Annual Growth Rate (CAGR) | 13.8% (Forecast Period) | Persistent rise in sophisticated ransomware campaigns, state-sponsored cyberespionage, and widespread remote work adoption. |
| Dominant Geographic Region | North America | High concentration of Fortune 500 enterprises, mature venture capital markets, and proactive federal cybersecurity mandates. |
| Fastest-Growing Region | Asia-Pacific (APAC) | Rapid digitization of economies in Southeast Asia, expanding 5G networks, and escalating state-backed cyber threats. |
| Key Enterprise Technologies | Zero Trust, XDR, CNAPP, AI Security | Shift from perimeter defense to identity-centric verification and real-time behavioral analytics. |
Geographic Breakdown and Regional Dynamics
The trajectory toward the $552.35 billion milestone is distributed unevenly across global geographies, with distinct regional dynamics dictating technology adoption curves and capital deployment.
North America continues to command the lion's share of global market revenue. The region's dominance is anchored by a dense concentration of global financial institutions, defense contractors, and technology giants that routinely absorb high enterprise software costs. Furthermore, rigorous oversight by agencies such as CISA (Cybersecurity and Infrastructure Security Agency) and the Department of Defense has established rigorous baseline security requirements that cascade down through entire supply chains, forcing small and medium-sized enterprises (SMEs) to upgrade their defensive postures.
Meanwhile, the Asia-Pacific (APAC) region is registering the fastest growth velocity globally. Economies such as India, Singapore, Japan, and Australia are experiencing an unprecedented digital transformation, driven by massive mobile-first consumer bases, burgeoning fintech sectors, and smart-city initiatives. However, this rapid digital expansion has exposed vast attack surfaces. Governments across APAC are responding by enacting sweeping data privacy laws and bolstering national cybersecurity centers, creating lucrative greenfield opportunities for both domestic startups and multinational security vendors.
In Europe, the market is characterized by a heavy emphasis on data sovereignty, privacy protection (building upon the foundation of GDPR), and critical infrastructure hardening. The enforcement of NIS2 and DORA has made the European market exceptionally receptive to integrated platform solutions that can demonstrate verifiable compliance and continuous risk monitoring.
Industry Implications: Winners, Losers, and Capital Reallocation
As the cybersecurity sector matures toward its 2031 valuation target, a profound bifurcation is taking place among market participants. The era of point-solution proliferation—where enterprises cobbled together dozens of disparate single-purpose tools&mdashis rapidly drawing to a close.
The Winners: Platform Consolidation and AI Integration
Enterprise buyers are exhibiting acute vendor fatigue. Chief Information Officers are aggressively rationalizing their software spend, favoring consolidated platform plays offered by industry behemoths and agile leaders capable of delivering end-to-end visibility through a single pane of glass. Companies that successfully integrate artificial intelligence and machine learning to automate threat detection, triage alerts, and execute autonomous remediation are commanding premium valuation multiples.
Furthermore, private equity firms and strategic acquirers are sitting on massive piles of dry powder. We anticipate a relentless wave of M&A activity as well-capitalized platform vendors absorb innovative startups specializing in niche domains like API security, post-quantum cryptography, and generative-AI-driven governance.
The Losers: Point-Solution Vendors and Legacy Laggards
Conversely, single-product vendors that fail to integrate into broader ecosystems face severe margin compression and acquisition vulnerability. Without the balance sheet scale to weather lengthening enterprise sales cycles or the technical architecture to interoperate with cloud-native environments, these sub-scale players risk becoming footnotes in industry consolidation waves. Similarly, legacy antivirus and firewall providers that clung too long to hardware-centric business models have steadily surrendered market share to cloud-native disruptors.
Frequently Asked Questions (People Also Ask)
What is driving the massive 13.8% CAGR in the cybersecurity market?
The 13.8% CAGR is propelled by a convergence of critical factors: the explosive migration of corporate data to multi-cloud environments, an escalating frequency and sophistication of ransomware and state-sponsored cyberattacks, the widespread adoption of remote and hybrid workforces, and stringent new regulatory compliance mandates enacted by global governments and financial watchdogs.
Which geographic region holds the largest market share in cybersecurity?
North America currently maintains the dominant market share, driven by deep enterprise IT budgets, a mature ecosystem of venture-backed technology startups, and proactive federal cybersecurity mandates. However, the Asia-Pacific (APAC) region is experiencing the fastest growth velocity due to rapid regional digitization and expanding national defense budgets.
How are regulatory frameworks impacting corporate security spending?
Regulations such as the SEC's cybersecurity disclosure rules in the U.S., the EU's NIS2 Directive, and DORA have transformed information security from a discretionary IT budget item into a legally mandated fiduciary responsibility. Executive leadership and boards face severe legal liabilities and financial penalties for non-compliance, making security spending entirely inelastic and prioritized across all economic cycles.
What technologies are attracting the most venture capital and enterprise investment?
Enterprise investment is heavily concentrated in Zero Trust Architecture (ZTA), Extended Detection and Response (XDR), Cloud-Native Application Protection Platforms (CNAPP), and AI-driven automation tools designed to mitigate analyst burnout and accelerate threat neutralization.
Future Outlook and Strategic Milestones to Watch
Looking ahead toward the 2031 horizon, the cybersecurity landscape will be defined by the maturation of generative artificial intelligence on both sides of the digital battlefield. While defenders utilize AI to predict breach pathways and automate incident response, malicious actors are simultaneously deploying autonomous AI agents to discover zero-day vulnerabilities and execute hyper-personalized phishing campaigns at machine speed.
For capital allocators, corporate executives, and industry observers, several critical milestones will dictate market winners over the next decade:
- The Quantum Threat Horizon: As quantum computing advances toward commercial viability, enterprise investment will increasingly pivot toward post-quantum cryptography (PQC) standards to protect encrypted data archives against future decryption attacks.
- AI Agent Governance: The proliferation of autonomous enterprise AI agents will necessitate entirely new classes of security tools dedicated to monitoring machine-to-machine transactions and preventing algorithmic data exfiltration.
- Supply Chain Transparency: Software Bill of Materials (SBOM) enforcement will become standardized across federal and enterprise procurement, punishing vendors with opaque software supply chains and rewarding those with verifiable code provenance.
Ultimately, the march toward a US$ 552.35 billion valuation underscores a fundamental economic reality: in a hyper-digitized global economy, security is the ultimate foundation of trust. Organizations that treat cybersecurity as a strategic capital investment rather than a tactical overhead expense will secure not only their networks, but their long-term market leadership.