NEW YORK — As the trading desks across lower Manhattan prepare for the opening bell of a pivotal summer week, a palpable tension hangs over institutional and retail portfolios alike. The era of unbridled, momentum-driven technology outperformance is facing its most rigorous stress test in quarters. With high-flying tech darlings wobbling under the weight of lofty valuation multiples, institutional capital allocators are aggressively pivoting away from passive growth accumulation. Instead, they are demanding rigorous proof of infrastructure scalability, tangible enterprise return on investment (ROI), and decisive macroeconomic clarity from the Federal Reserve.
This comprehensive investigative report dissects the underlying mechanics driving the current market inflection. We examine how shifting monetary policy expectations, ballooning capital expenditure cycles in artificial intelligence, and a looming corporate earnings season are colliding to reshape the architecture of global equity markets.
Executive Takeaways
- Federal Reserve Crossroads: Fixed-income and equity markets are locked in a high-stakes guessing game, scrutinizing incoming labor and inflation prints for definitive clues on the timing and magnitude of central bank monetary easing.
- The Tech Sector Inflection: Years of multiple expansion driven by generative AI enthusiasm are hitting a brick wall of fiscal accountability, as corporate buyers demand immediate bottom-line impact from cloud compute architecture and software deployments.
- Earnings Season Bellwethers: Upcoming quarterly disclosures from bellwether mega-cap technology and industrial firms will serve as a definitive litmus test for corporate profit margins and macroeconomic resilience.
- Capital Allocation Shifts: Risk mitigation strategies are forcing institutional portfolio managers to rebalance aggressively out of over-concentrated mega-cap equities and into defensive, cash-generative sectors.
Comprehensive Narrative: The Anatomy of a Market Correction
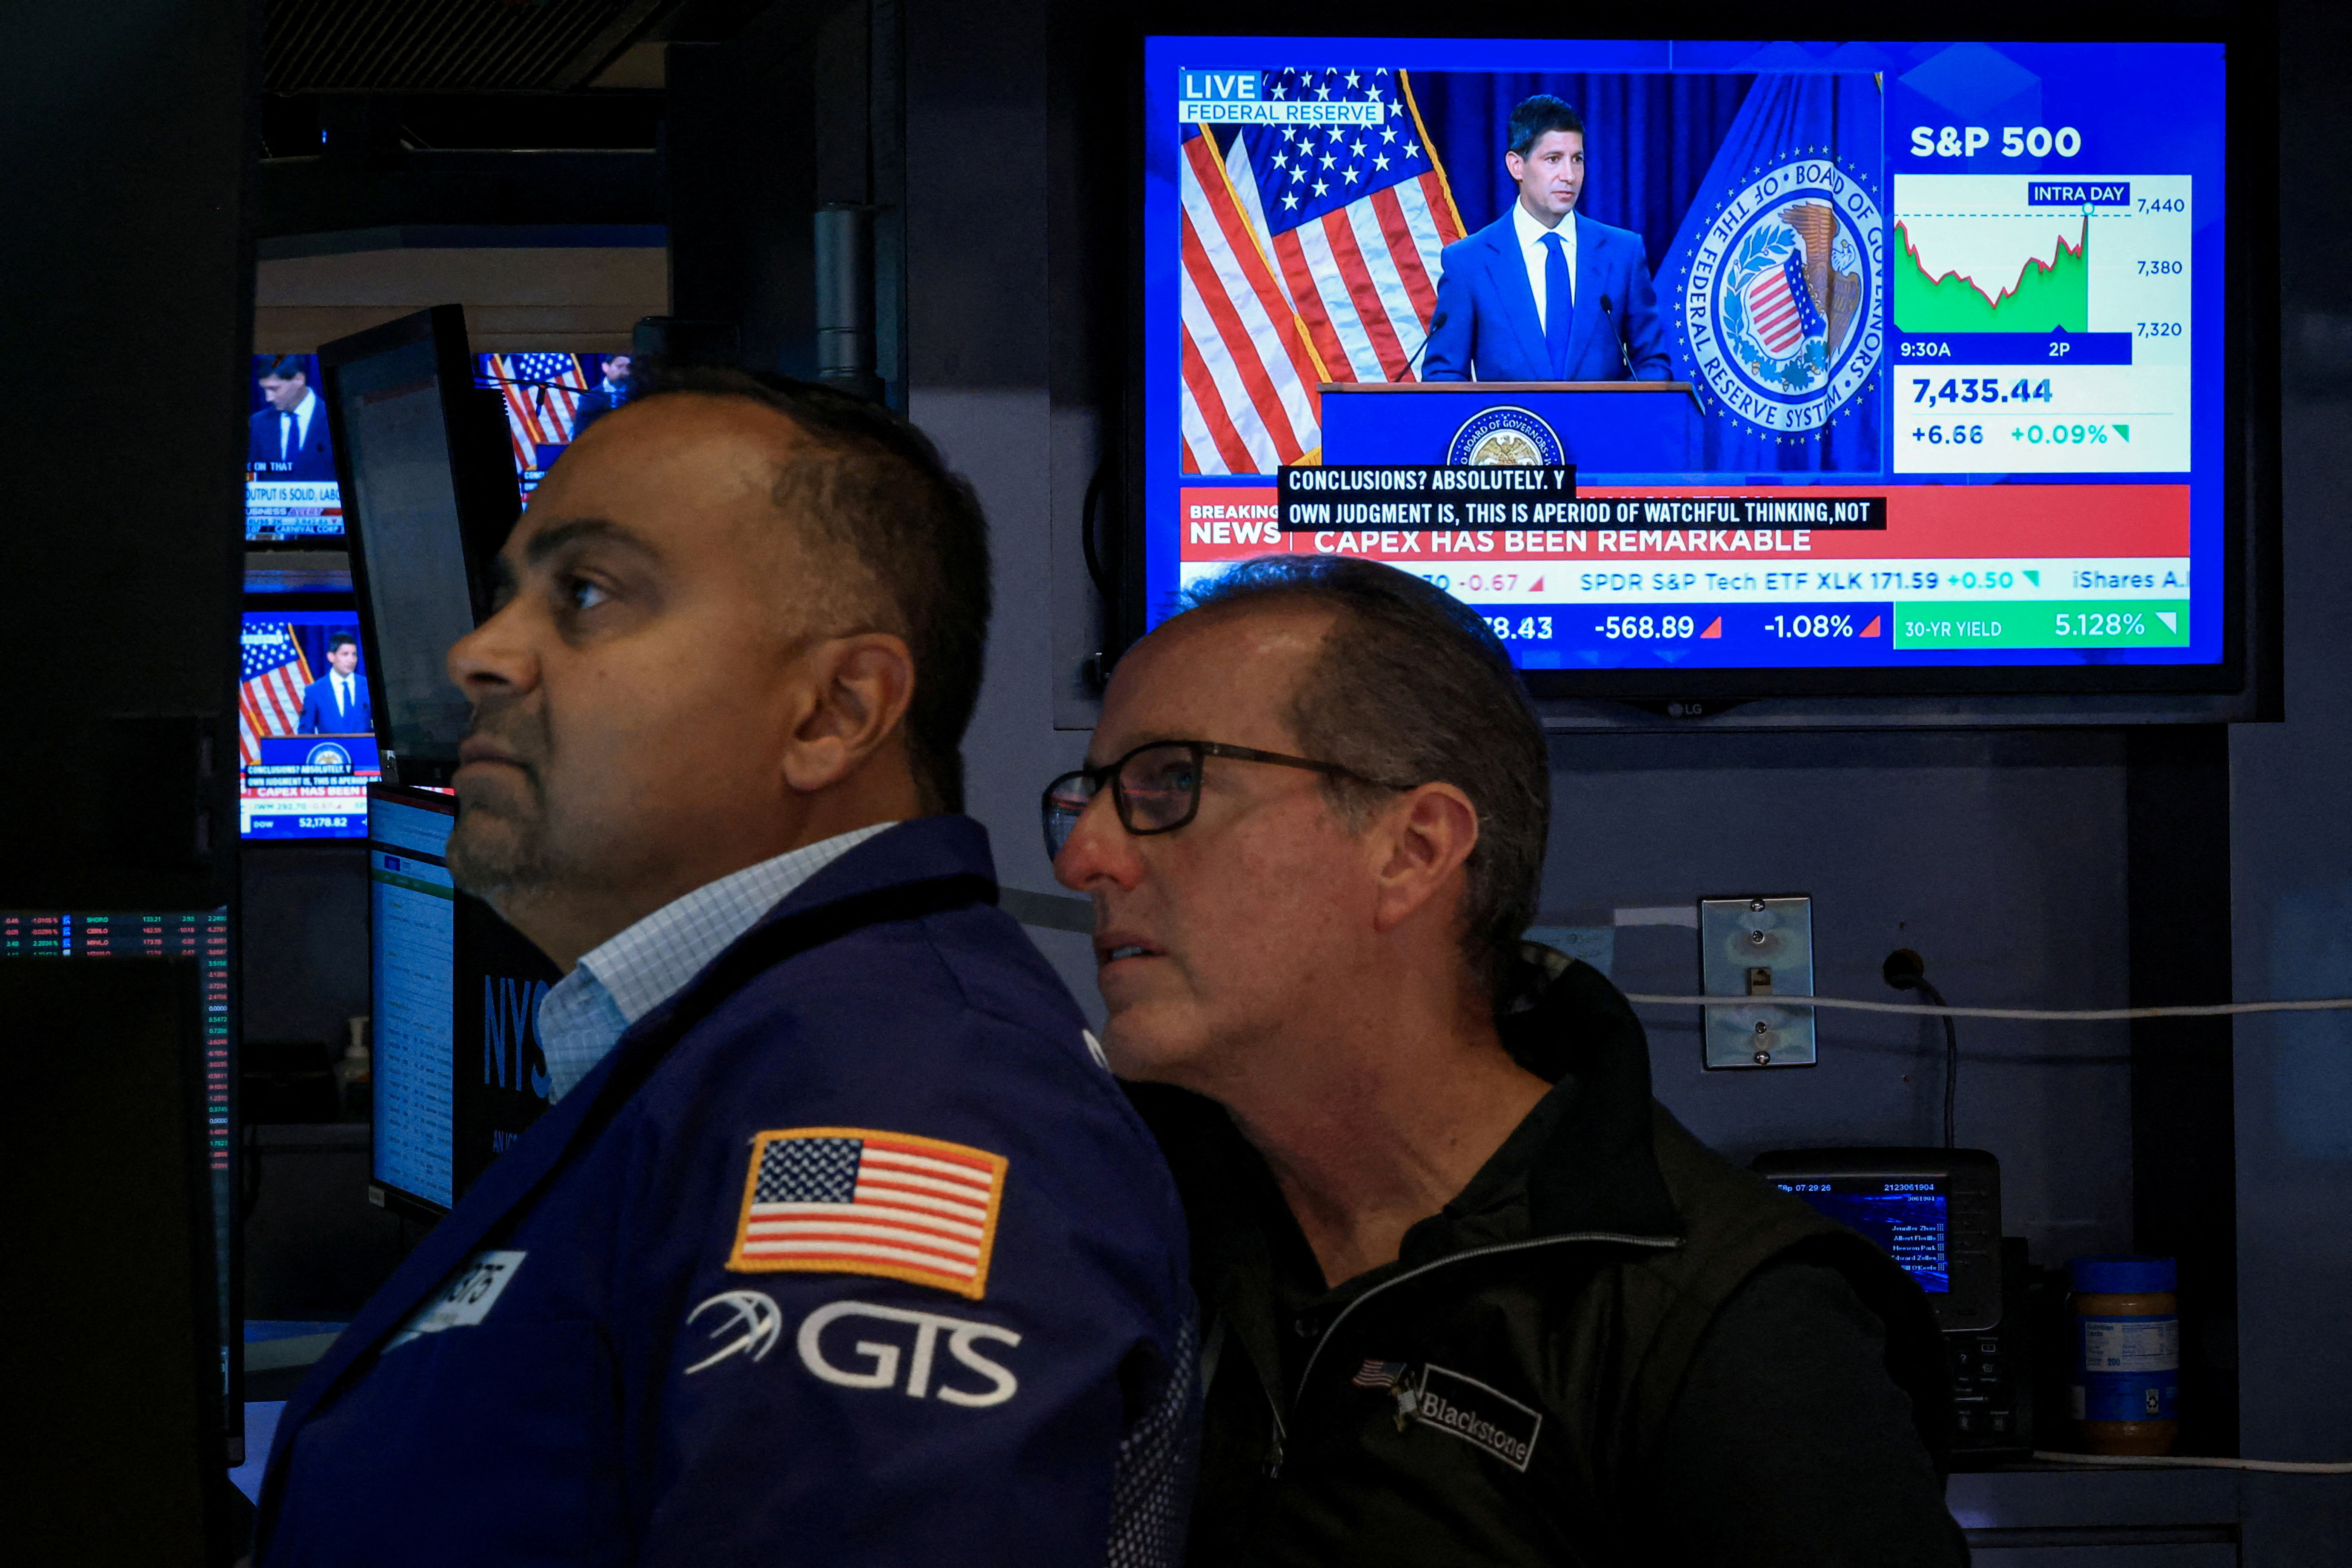
The macroeconomic backdrop heading into this critical market juncture is characterized by persistent friction between Wall Street’s dovish rate-cut aspirations and the Federal Reserve’s data-dependent stance. For months, market liquidity has been propped up by the resilient narrative of a "soft landing"—a macroeconomic scenario where inflation cools to the central bank's 2% target without triggering a broad-based economic contraction. However, recent economic data releases have muddied the waters, forcing rate strategists to recalibrate their models.
Simultaneously, the technology sector—the undisputed engine of the post-pandemic bull market—is showing structural fatigue. For nearly two years, capital markets rewarded aggressive capital allocation toward cloud infrastructure scalability and large language model training. Venture capitalists, private equity titans, and public market investors poured trillions into semiconductor manufacturing, high-density data centers, and advanced networking hardware. Yet, a fundamental question is now echoing through executive suites and boardrooms: Where is the enterprise ROI?
Chief Information Officers (CIOs) across Fortune 500 enterprises are under mounting pressure from CFOs to demonstrate immediate productivity gains and bottom-line cost reductions from their AI investments. The era of exploratory pilot projects is giving way to stringent regulatory compliance checks, security audits, and financial accountability. As enterprise software buyers scrutinize renewal cycles and push back on software-as-a-service (SaaS) price hikes, the top-line revenue growth rates of major tech firms are facing downward revisions.
This fundamental re-evaluation has triggered a cascading effect across Wall Street. As momentum algorithms unwind crowded long positions in semiconductor leaders and hyperscalers, market breadth is deteriorating. Institutional investors are executing complex risk mitigation maneuvers, trimming equity exposure, and locking in yields in short-duration fixed-income instruments while volatility indices drift upward from historical lows.
Verified Data & Metrics Breakdown
| Metric / Indicator | Current Market Status | Historical Baseline (Prior Year) | Market Implications & Impact |
|---|---|---|---|
| S&P 500 Technology Sector Forward P/E | 28.5x | 22.1x | Reflects compressed valuation multiples and heightened investor skepticism regarding future earnings growth. |
| Federal Reserve Benchmark Rate | 5.25% - 5.50% | 5.25% - 5.50% | Continues to restrict corporate borrowing and pressure leveraged balance sheets across mid-cap sectors. |
| Hyperscaler AI Capital Expenditure (YoY Growth) | +42% | +18% | Signifies aggressive infrastructure spending that requires rapid monetization to justify shareholder returns. |
| CBOE Volatility Index (VIX) | 16.4 | 13.2 | Demonstrates an incremental uptick in hedging activity and downside protection acquisition by institutional funds. |
Industry & Market Implications
The ongoing market recalibration creates a distinct divergence between winners and losers across global financial ecosystems. Understanding these bifurcations is critical for institutional asset managers navigating the current economic cycle.
Who Wins
- Cash-Generative Value Sectors: Defensive industries boasting robust balance sheets, consistent dividend growth, and low leverage—such as healthcare, utilities, and consumer staples—are attracting steady inflows as safe havens.
- Disciplined Enterprise Software Providers: Vendors that can demonstrate immediate, measurable operational efficiencies and clear enterprise ROI without requiring massive upfront implementation costs are capturing market share from legacy providers.
- Active Portfolio Managers: Unlike the passive indexing boom where a handful of mega-cap stocks dictated overall market returns, a volatile, stock-picker’s market rewards fundamental equity research and rigorous balance-sheet analysis.
Who Loses
- Unprofitable Growth & Speculative Tech: Early-stage tech startups and pre-revenue biotechs dependent on continuous venture capital injections or low-interest-rate debt face severe funding squeezes.
- Over-Leveraged Corporations: Firms with significant floating-rate debt maturities are experiencing margin compression as higher-for-longer interest rates bite into net income.
- Momentum-Chasing Retail Traders: Participants relying on unhedged, short-term options strategies and high-beta momentum stocks face heightened drawdown risks as intraday volatility spikes.
Frequently Asked Questions (People Also Ask)
Why is the technology sector experiencing a valuation pullback on Wall Street?
The tech sector pullback is primarily driven by a combination of stretched valuation multiples, rising expectations for enterprise return on investment (ROI), and a recalibration of interest rate expectations. Investors are moving away from speculative growth narratives, demanding instead that major technology firms prove their multi-billion-dollar investments in artificial intelligence and cloud infrastructure are translating into sustainable, bottom-line revenue growth.
How do Federal Reserve interest rate decisions impact tech stock valuations?
Higher interest rates increase the discount rate applied to future corporate cash flows. Because technology and growth companies derive a significant portion of their projected earnings far into the future, higher benchmark rates diminish the present value of those expected earnings, directly compressing valuation multiples.
What should investors look for during the upcoming corporate earnings season?
Institutional analysts advise focusing on forward-looking guidance, operating margin sustainability, capital expenditure efficiency, and concrete commentary regarding enterprise software demand. Management teams will be pressed to articulate clear pathways to monetizing their infrastructure investments amidst a more cautious corporate spending environment.
How are institutional investors adjusting their risk mitigation strategies?
Institutional portfolio managers are actively diversifying away from extreme concentration in mega-cap technology equities. Strategies include reallocating capital into cash-generative value sectors, increasing duration in fixed-income portfolios, and utilizing derivatives such as put options to protect against sudden market drawdowns.
Future Outlook & Key Milestones to Watch
As the market navigates the remainder of the quarter, the interplay between macroeconomic data releases and corporate earnings execution will dictate the trajectory of global asset prices. The primary catalysts to monitor include:
- Central Bank Signaling: Upcoming speeches by Federal Reserve officials and the release of FOMC meeting minutes will provide vital transparency regarding the central bank's tolerance for persistent inflation versus labor market cooling.
- Enterprise IT Budget Updates: Forward guidance from major enterprise software and hardware providers will reveal whether corporate clients are curtailing digital transformation budgets or accelerating high-efficiency deployments.
- Employment and Inflation Prints: Monthly Consumer Price Index (CPI) and Non-Farm Payrolls reports will remain the ultimate arbiters of monetary policy expectations, directly influencing bond yields and equity market sentiment.
Ultimately, Wall Street is transitioning from an era of speculative abundance to a disciplined environment of fundamental accountability. Investors who successfully navigate this transition will be those who prioritize rigorous balance-sheet analysis, proven enterprise utility, and robust risk management over blind momentum.