Executive Takeaways
- Silicon Bifurcation: Samsung’s internal deliberations regarding the Galaxy S27 Ultra chipset highlight a multi-billion dollar capital allocation dilemma between proprietary Exynos architecture and Qualcomm’s Snapdragon flagship platforms.
- Supply Chain Realities: Yield rates, thermal management profiles, and cloud compute architecture integration are dictating hardware roadmaps far earlier than historical product lifecycles suggest.
- Market Valuation Impact: Semiconductor partners, foundry utilization rates, and investor sentiment hang in the balance as enterprise ROI expectations shift toward on-device neural processing units (NPUs).
- Strategic Risk Mitigation: OEM diversification strategies are transforming from optional hedging mechanisms into existential requirements for maintaining operating margins in saturated global smartphone markets.
The global semiconductor ecosystem is once again holding its collective breath as fresh intelligence emerges from Seoul regarding the long-term roadmap for Samsung’s premier flagship device line. The latest developments in the unfolding Galaxy S27 Ultra chipset saga—freshly detailed by industry trackers and supply chain leaks—reveal a high-stakes corporate chess match involving billions of dollars in enterprise value, foundry capacity allocations, and intense competition for mobile supremacy.
For financial analysts, tech historians, and supply chain auditors, this is not merely a routine hardware refresh story. It is a masterclass in modern risk mitigation, capital expenditure optimization, and the relentless pursuit of processing dominance. As enterprise ROI expectations tighten across the consumer electronics sector, Samsung's strategic decisions regarding silicon sourcing will reverberate through Wall Street, the semiconductor foundries of Taiwan and South Korea, and the ultimate valuation multiples of the world's leading technology conglomerates.
Background and Catalytic Events: How the Saga Unfolded
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
To understand the gravity of the current twist in the Galaxy S27 Ultra chipset saga, one must examine the historical friction points that preceded it. For generations, Samsung Electronics has wrestled with a dual-sourcing strategy for its tier-one smartphones. By dividing global markets between its proprietary Exynos processors and Qualcomm’s Snapdragon series, Samsung sought to optimize its supply chain leverage, protect profit margins against rising component costs, and showcase its own foundry prowess.
However, this strategy has faced severe operational hurdles. Discrepancies in thermal efficiency, battery drain profiles, and peak compute performance between regional variants frequently sparked consumer backlash and put pressure on market liquidity for trade-in values. In response, recent hardware generations saw a temporary consolidation toward globally unified Snapdragon configurations for the Ultra tier, signaling a tactical retreat for Samsung’s System LSI division.
The latest twists reported across industry channels indicate that the pendulum is swinging once more. Driven by aggressive advancements in foundry node scaling—specifically maneuvering around 2nm architecture timelines—internal factions within Samsung are pushing for a high-risk, high-reward reintegration of next-generation Exynos silicon into the 2027 flagship cycle. This internal friction has turned the Galaxy S27 Ultra development pipeline into a focal point of intense boardroom negotiations, balancing engineering ambition against strict financial accountability.
Deep Technical Breakdown: Architecture, Yields, and NPU Scaling
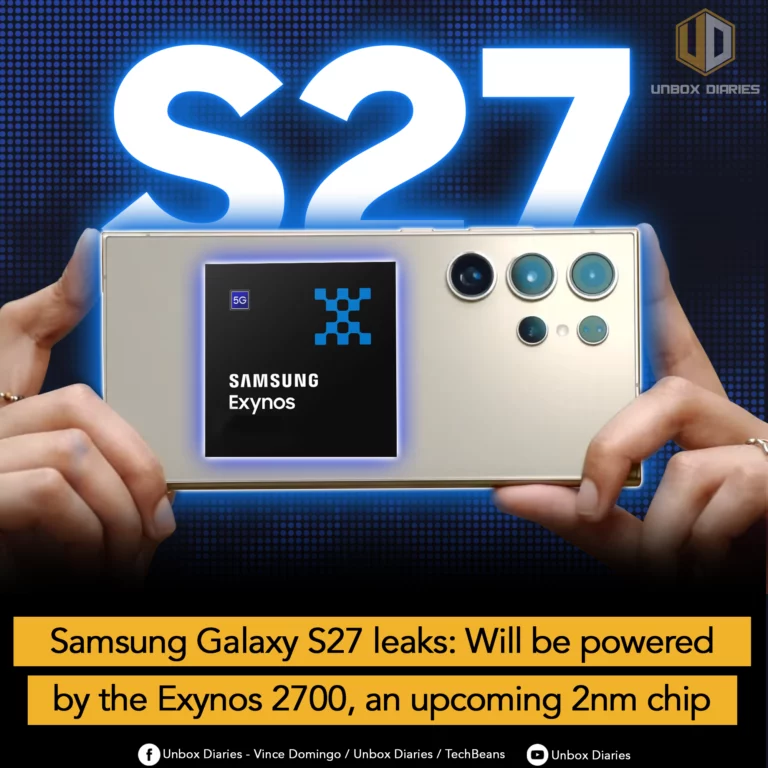
At the heart of the chipset saga lies an intricate web of engineering constraints and performance benchmarks. Modern ultra-tier smartphones are no longer judged solely by traditional CPU clock speeds or raw graphical rendering capabilities. Instead, enterprise and consumer demand have pivoted decisively toward on-device artificial intelligence, low-latency machine learning inference, and sophisticated cloud compute architecture integration.
The primary debate surrounding the Galaxy S27 Ultra centers on whether Samsung's upcoming gate-all-around (GAA) fabrication nodes can achieve the commercial yield rates necessary to sustain mass production for a globally distributed flagship. Key technical parameters under scrutiny include:
- Transistor Density & Node Maturity: The transition to sub-3nm and prospective 2nm nodes demands unprecedented precision, directly impacting manufacturing scrap rates and capital expenditure returns.
- Thermal Design Power (TDP): Managing sustained thermal output under heavy generative AI workloads without throttling performance remains a critical bottleneck for mobile system-on-chips (SoCs).
- NPU Throughput: Delivering high-teraflops-per-watt metrics to power localized large language models (LLMs) without depleting battery reserves within standard form factors.
- Memory Subsystem Bandwidth: Integrating next-generation LPDDR6 RAM to eliminate data bottlenecks between the primary processor and auxiliary accelerators.
Should Samsung's foundry division fail to hit aggressive yield targets, the company faces a difficult choice: absorb crippling margin compression by relying exclusively on outsourced, premium-priced Snapdragon silicon from Qualcomm, or risk reputational damage by deploying divergent regional chipsets once again.
| Strategic Dimension | The Exynos Internal Path | The Qualcomm Snapdragon Alternative |
|---|---|---|
| Financial & Margin Impact | High R&D cost, but potential for superior long-term component margin control. | Predictable component pricing, though subject to external supplier premium demands. |
| Foundry Utilization | Directly boosts Samsung Foundry fab loading and capacity monetization. | Outsources fabrication risk to external foundries (e.g., TSMC). |
| Performance Consistency | Historically volatile across regional batches; requires flawless execution on 2nm nodes. | Generally accepted gold standard for thermal stability and global benchmark parity. |
| Regulatory & Compliance Risk | Lower exposure to cross-border technology export restrictions. | Subject to complex international intellectual property licensing and trade frameworks. |
Industry & Market Implications: Winners, Losers, and Economic Ripples
The ramifications of this ongoing chipset saga extend far beyond Samsung's corporate headquarters in Suwon. In the global financial markets, semiconductor supply chain adjustments trigger immediate reactions in valuation multiples for publicly traded component makers, packaging specialists, and memory suppliers.
The Winners: If Qualcomm maintains its stronghold as the exclusive or primary silicon provider for the Galaxy S27 Ultra, its revenue visibility and market liquidity will receive a substantial bullish endorsement. Furthermore, specialized equipment manufacturers supplying advanced lithography and inspection tools to the winning fabrication lines stand to capture significant capital expenditure windfalls.
The Losers: Conversely, if Samsung’s internal semiconductor division is sidelined from powering the crown jewel of its mobile portfolio, it deals a psychological and financial blow to South Korea’s domestic chip manufacturing ambitions. Prolonged underutilization of advanced foundry nodes places immense pressure on operating margins and dampens investor enthusiasm for Samsung’s semiconductor foundry turnaround narrative.
From a macroeconomic perspective, the saga underscores the fragility of high-end consumer technology supply chains. As regulatory compliance landscapes shift and geopolitical tensions influence cross-border semiconductor trade, OEMs are forced to continuously recalibrate their risk mitigation playbooks. The ability to pivot manufacturing pipelines dynamically is no longer an operational luxury; it is a fundamental prerequisite for corporate survival.
Frequently Asked Questions (People Also Ask)
Expert Answers to Common Inquiries
Why is the Galaxy S27 Ultra chipset decision causing such intense industry debate?
The debate centers on a high-stakes trade-off between utilizing Samsung's proprietary Exynos silicon—which supports internal foundry utilization and margin control—versus adopting Qualcomm’s Snapdragon processors, which offer proven global performance consistency and thermal efficiency. The decision directly impacts billions of dollars in R&D, manufacturing yield targets, and end-user market reception.
How do fabrication node advancements (such as 2nm technology) influence this saga?
Moving to advanced sub-3nm and 2nm nodes drastically increases transistor density and energy efficiency, which are critical for running heavy on-device AI tasks. However, these cutting-edge nodes present severe manufacturing challenges, including low initial yield rates and massive capital expenditure requirements, complicating Samsung's production timeline.
What are the financial implications for Samsung's operating margins?
Relying entirely on external tier-one suppliers like Qualcomm exposes Samsung to rigid component pricing, compressing hardware margins. Conversely, successfully producing and deploying competitive proprietary silicon can dramatically improve long-term profitability and amortize the massive overhead costs associated with modern foundry operations.
When will a definitive hardware roadmap be finalized for the device?
While early engineering samples and foundry trial runs are currently underway, supply chain insiders indicate that final silicon lock-ins typically occur several quarters ahead of commercial launch, leaving a narrow window for executive leadership to weigh trial yield data against market risk.
Future Outlook: What Comes Next and Key Milestones to Watch
As the narrative surrounding the Galaxy S27 Ultra chipset continues to evolve, market observers and financial analysts must monitor several critical leading indicators over the coming quarters. The resolution of this saga will establish a vital precedent for how legacy consumer electronics giants manage the delicate intersection of semiconductor fabrication and branded hardware manufacturing.
Key milestones to watch include:
- Foundry Yield Reports: Early data releases concerning Samsung Foundry's 2nm test wafer defect densities and commercial production readiness.
- Supply Chain Audit Leaks: Component procurement filings and preliminary volume commitments submitted to packaging and assembly partners.
- Executive Guidance Adjustments: Commentary from Samsung Electronics' quarterly earnings calls regarding capital expenditure allocations for System LSI and memory divisions.
- Competitor Benchmarking: Comparative performance metrics from rival flagship mobile platforms deploying contemporary architecture.
Ultimately, the Galaxy S27 Ultra chipset saga is far more than a routine technology news cycle. It is a defining crucible for mobile semiconductor strategy, testing the resilience, financial discipline, and engineering mettle of one of the world's most influential technology titans. As the pieces fall into place, the outcome will irrevocably shape the competitive landscape of the global mobile economy for years to come.