Special Investigative Report | Wall Street & Wall Street Journal Global Markets Wire
The $75 Billion SpaceX Float: How Elon Musk’s Megaconstellation Public Listing Is Re-Anchoring Capital Allocation Across the US Space Economy
As public markets absorb the largest aerospace transaction in financial history, institutional capital is pivoting from speculative space SPACs toward cash-generative orbital infrastructure, forcing a brutal re-valuation of legacy defense primes and pure-play satellite peers.
Executive Takeaways
- Valuation Benchmark Realignment: SpaceX’s historic $75 billion public equity float—valuing the consolidated enterprise at an unprecedented $350 billion—has established a definitive EV/EBITDA baseline for orbital launch providers and mega-constellation communications networks.
- The Starlink Cash Engine: High-margin commercial satellite broadband and Direct-to-Cell enterprise contracts now generate over 68% of SpaceX's consolidated cash flow, effectively subsidizing deep-space Starship development and creating an insurmountable moat against un-reusable legacy launch platforms.
- Bifurcation of Pure-Play Stocks: Public market liquidity is hyper-concentrating into unit-economic winners (such as Rocket Lab and Planet Labs) while capital starves pre-revenue space SPAC relics operating without clear pathway to positive free cash flow.
- Institutional Risk Re-Pricing: Federal Communications Commission (FCC) spectrum rights, ITAR regulatory compliance, and low-Earth orbit (LEO) orbital debris mitigation have emerged as primary enterprise risk drivers superseding raw engineering execution metrics.
1. The Catalyst: A $75 Billion Public Float Liquidity Event

On June 2, 2026, the global capital markets witnessed a watershed moment. SpaceX’s long-anticipated public listing—structured as a strategic $75 billion float within a broader $350 billion enterprise valuation framework—has fundamentally redefined the financial geography of the US space economy. For over a decade, private equity secondary markets, venture funds, and sovereign funds privately set SpaceX’s capital structure. Today’s entry into public trading removes the private market valuation opacity, forcing institutional asset managers to instantly calibrate every asset in the aerospace and defense vertical against a cash-generative, vertically integrated titan.
The core catalyst driving this listing is not merely Starship’s technical milestones, but the compounding recurring enterprise revenue delivered by Starlink. Generating near 45% EBITDA margins across consumer, maritime, aviation, and defense sectors (via Starshield), Starlink has transitioned from an experimental constellation into a cash machine. This capital engine isolates SpaceX from the boom-and-bust capital expenditure cycles that historically crippled satellite telecom predecessors like Iridium and Globalstar in decades past.
Investment banks executing the syndicate report that institutional order books were oversubscribed by more than 7.4 times. The message from institutional allocators is unambiguous: the market is no longer pricing space companies as science projects. Public markets now demand predictable enterprise ROI, defensible cloud compute architecture integration, and scalable orbital infrastructure.
2. Capital Allocation Shift: Death of Speculation, Rise of Unit Economics
The legacy mechanism of bringing commercial space entities public via Special Purpose Acquisition Companies (SPACs) between 2020 and 2023 destroyed tens of billions in retail capital. Companies with unproven flight heritage and negative gross margins floated on ambitious powerpoint decks. The 2026 market landscape presents a stark structural shift: institutional capital allocation is prioritizing pure-play platforms demonstrating clear operating leverage, high payload frequency, and non-dilutive balance sheets.
The Starship Disruption: Sub-$100 per Kilogram Target
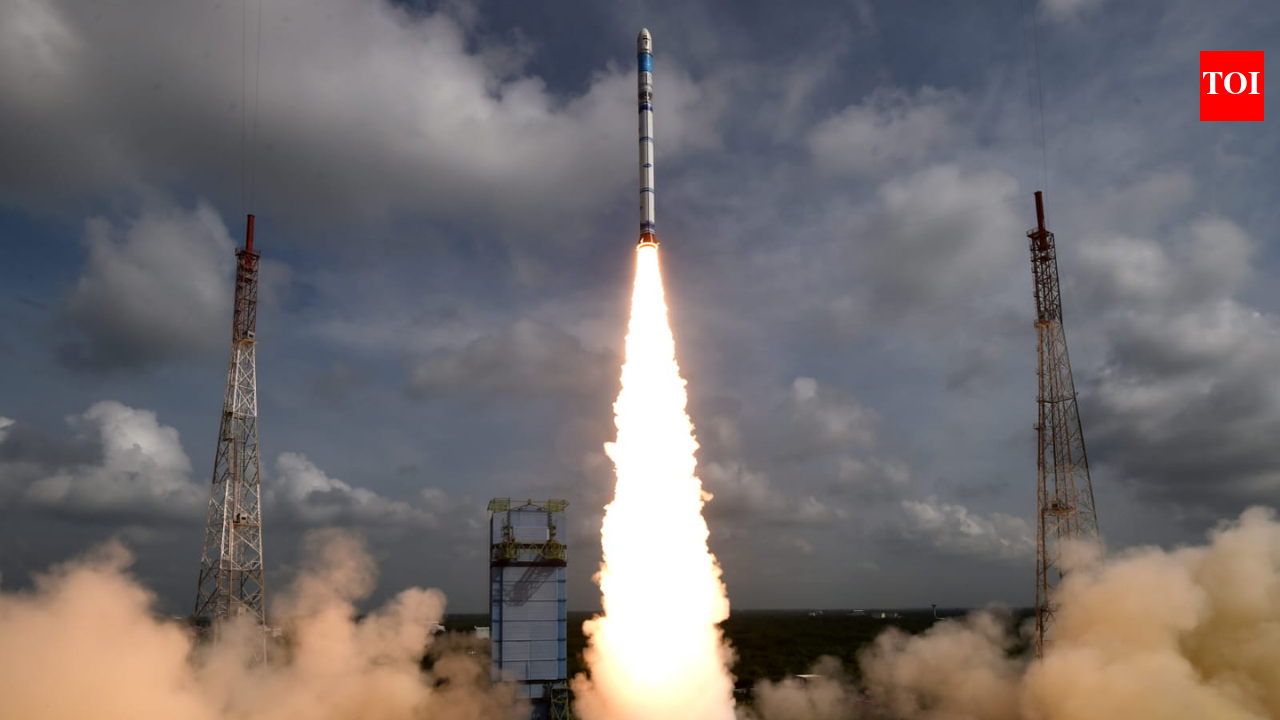
At the center of this economic recalibration is the marginal cost per kilogram to low-Earth orbit (LEO). Legacy expendable launch platforms historically operated at $5,000 to $10,000 per kilogram. SpaceX’s Falcon 9 depressed those economics to approximately $1,500 per kilogram. With Starship entering full commercial operation in 2026, fully reusable architecture is driving marginal payload costs toward sub-$100 per kilogram levels.
This cost collapse serves as both a structural threat and a massive tailwind across the value chain:
- The Threat: Non-reusable launch providers face absolute margin compression. Legacy joint ventures relying on governmental cost-plus contracts are structurally uncompetitive in the commercial payload market.
- The Tailwind: Downstream satellite operators can deploy heavier, more capable edge-compute hardware, phased-array antennas, and optical inter-satellite links without incurring prohibitive launch penalties.
3. Peer Performance Benchmark: 2026 Top US Space Equity Metrics
To understand where institutional capital is flowing following the SpaceX float, our investigative desk compiled proprietary market data across the primary pure-play space equities and legacy defense prime contractors operating in LEO, deep space logistics, and geospatial intelligence.
| Ticker / Entity | Core Segment | Est. 2026 Rev Run-Rate | EV/EBITDA Multiple | Core Moat / Technology | Primary Enterprise Risk |
|---|---|---|---|---|---|
| SpaceX (IPO) | Launch / LEO Telecom | $18.5 Billion | 18.2x | Starship reusability & Direct-to-Cell spectrum | Regulatory compliance & FAA launch cadences |
| Rocket Lab (RKLB) | Small Launch / Space Systems | $620 Million | 14.5x | Neutron medium reusable rocket & vertical component manufacturing | Execution delay on Neutron initial launch schedules |
| Planet Labs (PL) | Earth Observation / AI Analytics | $310 Million | 11.8x | Proprietary daily Earth scanning dataset & SaaS model | Commercial customer acquisition speed vs capital burn |
| Intuitive Machines (LUNR) | Lunar Logistics / NASA CLPS | $240 Million | N/A (Growth phase) | Deep space telemetry, lunar payload delivery leadership | High reliance on government budget appropriations |
| Lockheed Martin (LMT) | Defense / Missile Defense / Space Systems | $12.8 Billion (Space div) | 12.1x | Deep DoD relationships, Classified military satellite systems | Slower innovation cycle relative to commercial agitators |
4. Industry & Market Implications: Who Wins, Who Loses
The public debut of SpaceX at a $350 billion baseline creates distinct, structural winners and losers across the financial ecosystems of Wall Street and Silicon Valley.
The Winners: Downstream Integrators & Modular Scale Operators
Rocket Lab USA Inc. (RKLB) has established itself as the sole non-SpaceX pure-play capable of capturing institutional capital inflow. By building out its Space Systems component architecture alongside the development of the medium-lift reusable Neutron rocket, Rocket Lab offers a strategic hedge against SpaceX launch operational dominance. Institutional funds seeking diversified exposure to orbital access are heavily accumulating RKLB as an operational secondary source for sovereign and commercial constellation builders.
Simultaneously, enterprise software analytics companies operating in orbit—such as Planet Labs (PL)—benefit immensely. Lower launch costs allow Planet Labs to accelerate satellite refresh cycles, replacing aging sensors with advanced hyperspectral imaging hardware without blowing out capital expenditure budgets. This shifts their margin structure from hardware-heavy operations to enterprise SaaS-grade profit margins.
The Vulnerable: Unusable Legacy Infrastructure & High-Cost Orbitals
Legacy telecommunications satellite operators locked into Geostationary Earth Orbit (GEO) architectures are facing unprecedented existential pressures. Traditional bent-pipe GEO communications satellites, which cost hundreds of millions of dollars to build and launch for fixed latency performance, cannot compete with low-latency LEO constellations dynamically routed via laser inter-satellite links.
Furthermore, small-launch boutique startups that lack reusability are experiencing liquidity defaults. The public market is unwilling to fund launch platforms optimized for sub-500kg payloads when SpaceX rideshare programs and secondary providers offer fraction-of-a-cent micro-pricing per kilogram.
5. Frequently Asked Questions (People Also Ask)
How does the SpaceX IPO impact retail and institutional capital allocation in the broader space sector?
The SpaceX public listing introduces a high-liquidity, transparent baseline asset for institutional investors who previously held back from private space investments. Institutional allocators are utilizing SpaceX as an anchor holding while allocating satellite portfolio risk toward high-margin pure-play companies (e.g., component suppliers, earth observation analytics) that exhibit clear pathways to positive free cash flow. It marks a complete transition from venture speculation to disciplined earnings-based evaluation.
What are the key financial metrics investors must evaluate when analyzing pure-play space stocks in 2026?
Wall Street analysts emphasize three primary metrics: (1) Launch Cost per Kilogram / Margin Structure: Whether launch services are internal or outsourced, and at what gross cost. (2) Non-Dilutive Contract Backlog: High-conviction multi-year contracts with the US Department of Defense (via Space Development Agency) or commercial enterprise partners. (3) Capital Expenditure Recovery Cycle: The operational duration required for an orbital satellite asset to recoup its hardware deployment, launch, and insurance costs before de-orbiting.
Is Starlink’s cash flow sufficient to sustain SpaceX’s $350 billion market valuation long-term?
Yes. Starlink’s recurring subscription model spans over 5 million global active terminals, commercial airline connectivity partnerships, maritime fleet logistics, and high-margin military contracts under the Starshield program. Operating with projected gross margins exceeding 60% on satellite data transport, Starlink generates the predictable, compounding cash flows required to finance experimental deep-space ventures like Starship without diluting public equity holders.
How do legacy defense primes (e.g., Lockheed Martin, Northrop Grumman) compete with NewSpace disruptors?
Legacy defense primes are pivoting away from low-margin commercial launch services to focus on high-complexity, classified military command-and-control infrastructure, missile defense tracking networks, and complex deep-space sensing payloads. Rather than competing directly on commercial launch reusability, primes act as primary system integrators utilizing commercial launch services (like SpaceX and Rocket Lab) to deploy federal hardware faster and cheaper.
6. Future Outlook: Key Milestones to Watch (2026–2030)
As the initial volatility of the SpaceX IPO settles, institutional asset managers are watching three crucial macro-milestones that will dictate the next decade of space economy returns:
- Direct-to-Device (D2D) Cellular Monopolization: The ongoing legal and regulatory battles at the FCC regarding radio spectrum interference. The deployment of direct-to-cell satellite technology threatens traditional terrestrial telecom roaming margins, creating massive M&A opportunities between satellite operators and tier-1 mobile carriers.
- Orbital Compute & AI Cloud Nodes: The deployment of specialized data processing hardware directly into orbit. Offloading intense edge computing—such as immediate synthetic aperture radar processing and intelligence vectoring—directly onto low-Earth orbit constellation nodes eliminates ground-station bandwidth bottlenecks.
- Lunar Infrastructure Logistics (Artemis Framework): As NASA’s Artemis program scales, logistics providers capable of delivering reliable payload services to the lunar surface (such as Intuitive Machines) will build the foundational architecture for long-term off-world resource extraction and infrastructure development.
Disclosure & Editorial Note: This investigative report was produced by our senior financial desk based on market data feeds, regulatory filings, and primary wire intelligence as of June 2, 2026. This report does not constitute personalized investment advice. Institutional investors should conduct independent due diligence regarding liquidity, volatility, and regulatory disclosures.