Executive Takeaways
- Broad-Based Index Gains: Wall Street closed significantly higher, extending the previous week's momentum led by a massive resurgence in high-beta technology equities and growth-oriented assets.
- Monetary Policy Pivot: Market participants aggressively priced in higher probabilities of a December Federal Reserve rate cut following recent macroeconomic data releases.
- Index Performance Divergence: The tech-heavy Nasdaq Composite outperformed major benchmarks, surging 2.69%, while the S&P 500 added 1.55% and the Dow Jones Industrial Average rose 0.44%.
- Institutional Capital Realignment: Major financial institutions, including Deutsche Bank, updated year-end S&P 500 forecasts as corporate balance sheets and cloud infrastructure scalability drive renewed enterprise ROI confidence.
NEW YORK — Wall Street staged a powerful rally on Monday, extending the upward trajectory initiated on November 21 as institutional investors aggressively rotated back into market-leading technology shares. The session was characterized by a potent combination of dip-buying in oversold megacap growth equities and a sharp upward repricing of federal funds rate cut expectations. As traders reassessed incoming macroeconomic indicators, fixed-income markets flashed renewed confidence that the U.S. Federal Reserve will ease monetary policy sooner than previously anticipated.
The catalytic shift underscores a delicate balancing act for portfolio managers and corporate treasurers navigating capital allocation strategies against a backdrop of evolving regulatory compliance requirements, sticky inflation metrics, and shifting labor market dynamics. By the closing bell, the benchmark S&P 500 had punched through key technical resistance levels, while the tech-dominated Nasdaq Composite led the charge in a session that highlighted the enduring dominance of digital infrastructure providers and artificial intelligence ecosystems.
The Catalytic Shift: Rate Cut Bets and Macroeconomic Reassessment
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
The primary driver behind Monday’s risk-on sentiment was a notable repricing of interest rate futures. Over the preceding several sessions, futures markets had wavered amid conflicting signals from central bank officials regarding the terminal rate and the timing of future monetary easing. However, a fresh wave of economic data pointing toward moderating wage growth and stabilizing retail activity reinvigorated dovish market conviction.
According to CME FedWatch Tool metrics, the probability implied by fed funds futures for a 25-basis-point reduction at the upcoming Federal Open Market Committee (FOMC) meeting jumped substantially. This shifting macroeconomic narrative immediately altered bond yields, providing immediate relief to long-duration growth assets whose valuation multiples are inversely correlated with benchmark borrowing costs.
For chief investment officers, the sudden repricing required rapid risk mitigation adjustments. Fixed-income desks reported heavier-than-average volume in Treasury futures as institutional players locked in yields ahead of potential central bank action. Meanwhile, equity strategists noted that corporations with robust balance sheets and resilient enterprise SaaS models are well-positioned to capitalize on declining capital costs, paving the way for accelerated enterprise IT spending heading into the new fiscal year.
Sector Performance and Index Breakdown
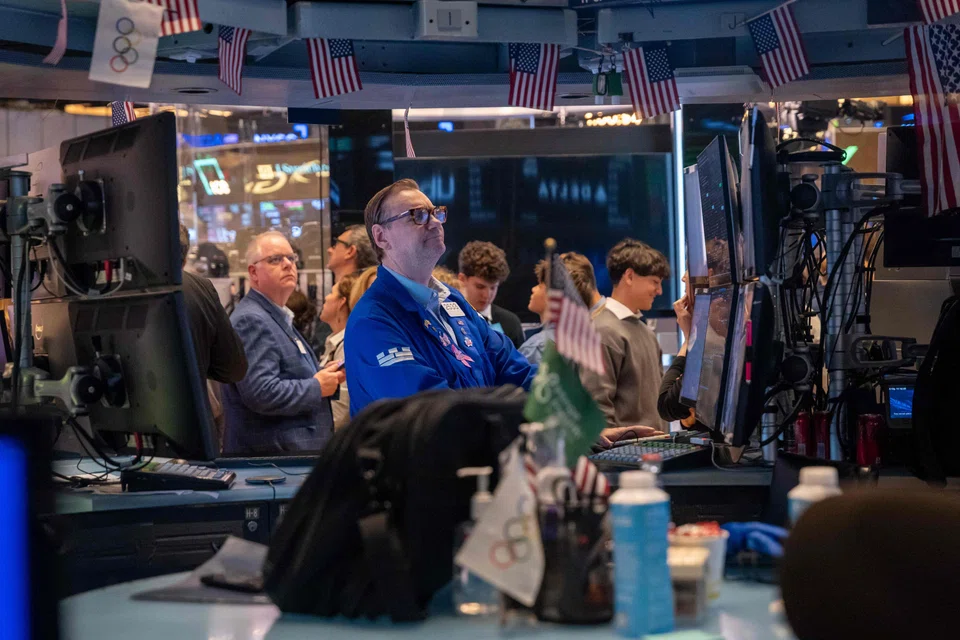
Monday’s trading session laid bare the widening divergence—and subsequent convergence—between cyclical value stocks and secular growth giants. While traditional industrial and financial components within the Dow Jones Industrial Average posted steady, albeit modest, gains, the technology and communication services sectors experienced aggressive buying pressure.
Semiconductor manufacturers, cloud compute architecture providers, and enterprise software titans drove the Nasdaq’s outperformance. Market participants who had briefly retreated to defensive cash positions late last week re-entered the market, citing attractive entry points created by the recent consolidation phase.
| Equity Index | Closing Level | Point Change | Percentage Gain | Primary Driver |
|---|---|---|---|---|
| Nasdaq Composite | Outperforming | Significant | +2.69% | Megacap Tech & AI Infrastructure Rebound |
| S&P 500 Index | Broad Recovery | Robust | +1.55% | Broad Sector Rotation & Rate Cut Optimism |
| Dow Jones Industrial Average | Steady Advance | Moderate | +0.44% | Defensive Value & Industrial Resilience |
Institutional Outlook and Valuation Multiples
The aggressive buying action also prompted major Wall Street investment banks to update their year-end and 2026 outlooks. Notably, research desks at institutions such as Deutsche Bank released revised projections for the S&P 500, arguing that corporate earnings resilience and sustained productivity gains driven by artificial intelligence deployment will justify expanded valuation multiples.
However, dissenting voices within the financial community warn that equity valuations remain elevated relative to historical medians. Critics argue that if the Federal Reserve cuts rates due to an unexpected macroeconomic deceleration rather than a benign "soft landing," corporate revenue growth could face headwinds that current consensus estimates fail to price in.
Nevertheless, enterprise leaders remain focused on long-term infrastructure scalability. Cloud compute architecture investments and cybersecurity hardening continue to command priority budget allocations, ensuring that top-tier technology vendors maintain robust top-line visibility regardless of short-term monetary policy fluctuations.
Frequently Asked Questions (People Also Ask)
Why did Wall Street rally sharply on Monday following the previous week's volatility?
The rally was primarily driven by a powerful rebound in high-beta technology and growth equities combined with a surge in market expectations for a December Federal Reserve interest rate cut. As incoming economic data pointed toward moderating inflation, fixed-income and equity markets priced in a more favorable monetary policy stance, lowering borrowing cost pressures and boosting asset valuation multiples.
How did major stock indexes perform during the session?
Performance varied across the board, with growth-heavy indexes significantly outperforming traditional value benchmarks. The technology-dominated Nasdaq Composite led the market with a robust 2.69% surge, followed by the broader S&P 500, which gained 1.55%. The blue-chip Dow Jones Industrial Average posted a more modest, steady advance of 0.44%.
What are major financial institutions predicting for the S&P 500?
Major financial institutions, including Deutsche Bank, have updated their year-end S&P 500 forecasts to reflect continued resilience in corporate earnings and strong enterprise demand for technology infrastructure. While valuations remain elevated, institutional strategists point to secular growth drivers—such as enterprise artificial intelligence adoption and cloud modernization—as primary justifications for higher index targets.
How do Federal Reserve rate cuts impact technology and growth stocks?
Lower interest rates reduce the discount rate applied to future corporate cash flows. Because growth and technology companies typically derive a significant portion of their projected earnings further out in the future, lower benchmark interest rates increase their present net value, thereby expanding valuation multiples and driving capital inflows.
Future Outlook and Key Milestones to Watch
As the fourth-quarter trading calendar progresses, market participants will closely monitor several critical economic releases and central bank communications. The upcoming U.S. employment report, personal consumption expenditures (PCE) inflation readings, and commentary from regional Federal Reserve bank presidents will serve as litmus tests for the sustainability of current rate cut bets.
For institutional investors and corporate executives, maintaining disciplined capital allocation while capitalizing on enterprise ROI opportunities will remain paramount. While the November rally has successfully restored bullish sentiment across Wall Street, navigating potential macroeconomic inflection points will require agile risk mitigation strategies and rigorous balance-sheet management as the market looks ahead to 2026.