Executive Takeaways
- Unprecedented Valuations Meet Macro Realities: A relentless, technology-led equities rally has pushed U.S. markets to record highs, setting up a high-stakes collision with the upcoming Consumer Price Index (CPI) print.
- The Fed Policy Pivot Under Scrutiny: Fixed-income desks and institutional asset managers are recalibrating risk models as headline inflation prints, crude oil fluctuations (WTI at $83.38/bbl), and volatile commodity baskets threaten the anticipated monetary easing cycle.
- Capital Allocation Rebalancing: Corporate treasuries and institutional allocators are executing aggressive risk mitigation strategies, rotating out of frothy multiple expansions and into defensive hedging instruments.
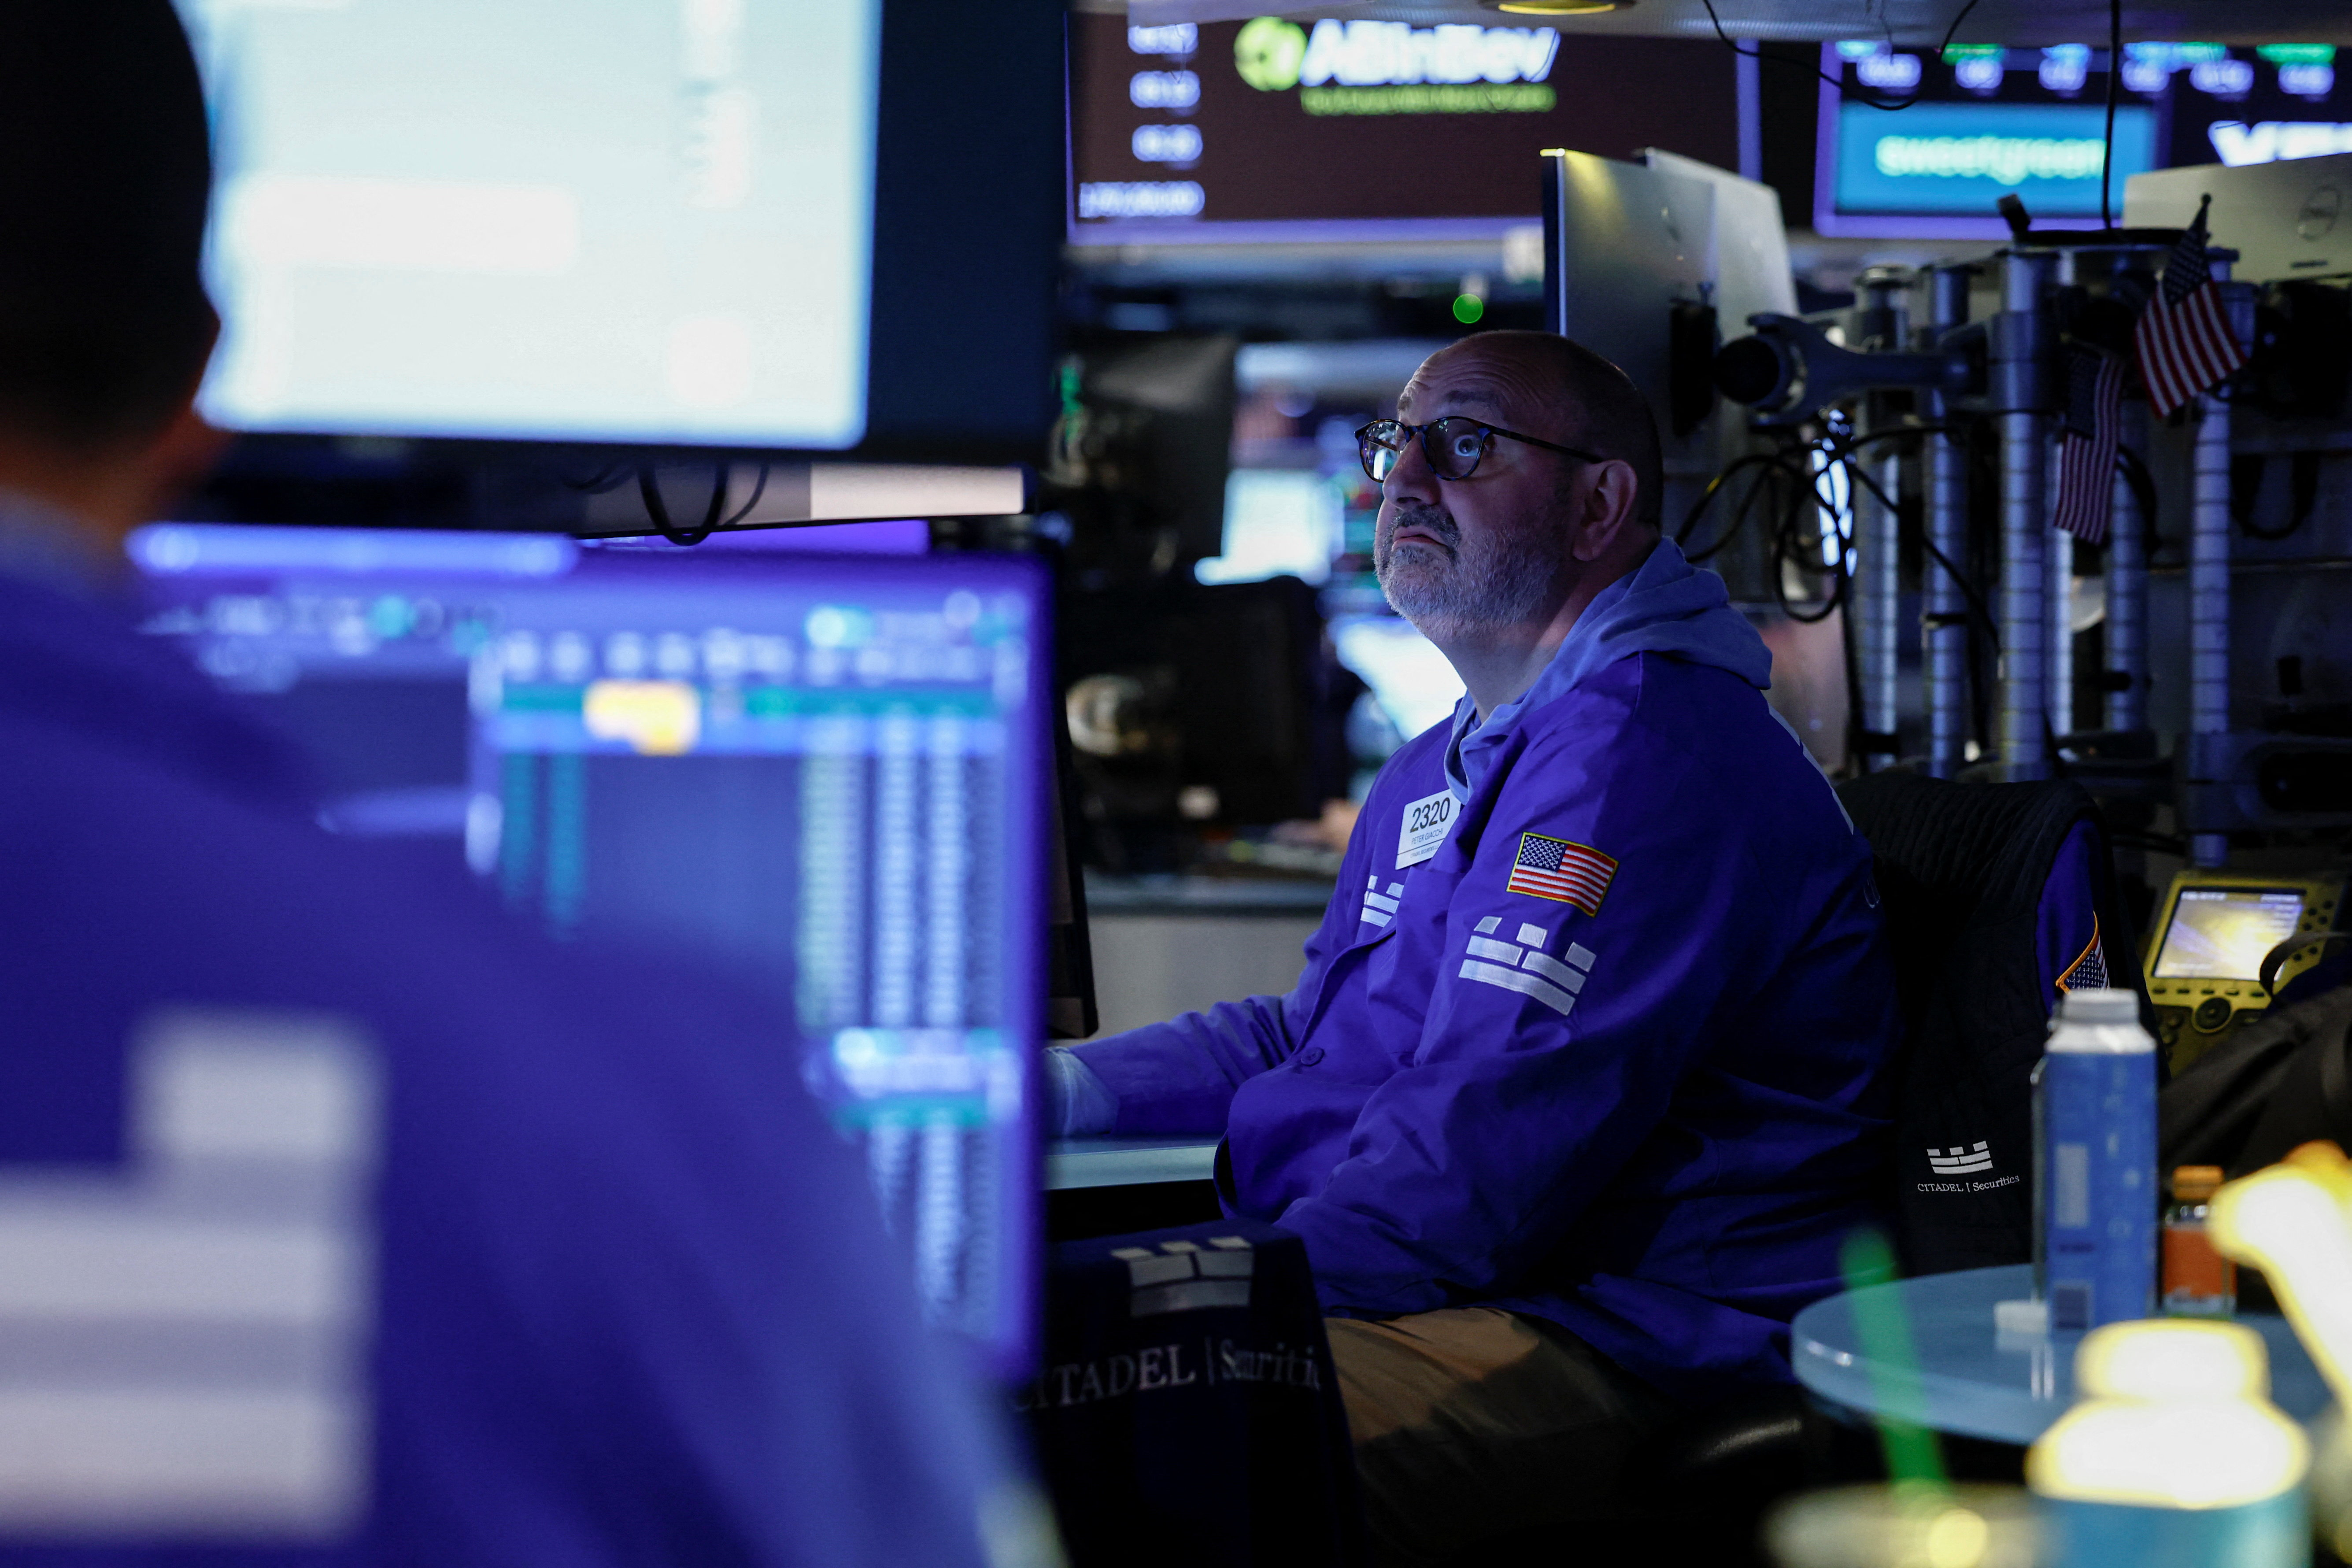
NEW YORK — As the trading floor hums with the electric tension characteristic of late-summer capital markets, Wall Street stands at a formidable macroeconomic precipice. Driven by relentless enthusiasm for artificial intelligence infrastructure scalability, cloud compute architecture dominance, and resilient enterprise software earnings, major U.S. equity benchmarks have punched through successive technical ceilings to notch historic all-time highs. Yet, beneath the veneer of this record-setting surge lies a fragile consensus. The upcoming release of the Consumer Price Index (CPI) report on Wednesday, August 12, 2026, threatens to disrupt the prevailing monetary narrative, testing the limits of aggressive valuation multiples and forcing institutional investors to re-evaluate their risk-reward parameters.
For months, the market narrative has been anchored by a singular, comforting assumption: that disinflation is entrenched, the Federal Reserve has successfully engineered a soft landing, and an imminent series of benchmark interest rate cuts will provide a liquidity cushion for corporate expansion. However, recent readings in commodity complexes—most notably West Texas Intermediate (WTI) crude oil holding firm at $83.38 per barrel, alongside sticky components like agricultural baselines and core services—suggest that inflationary pressures may prove more stubborn than consensus forecasts allow. As institutional desks finalize their positioning ahead of the mid-week data drop, Chief Investment Officers across Midtown Manhattan and Mayfair are asking a critical question: Can current equity valuations survive an upside inflation surprise, or are markets priced for perfection in an increasingly imperfect economic reality?
The Anatomy of the Current Rally: Tech Dominance and Multiple Expansion
To understand the gravity of this week’s inflation test, one must examine the mechanics of the current bull run. Unlike previous liquidity-driven expansions, the 2026 market surge has been characterized by extreme concentration in mega-cap technology enterprises. These firms have leveraged structural shifts in enterprise ROI to justify soaring equity prices, backed by massive capital expenditures in semiconductor fabrication, hyperscale data centers, and generative AI deployment.
However, this concentration has left broader market indices highly sensitive to shifts in the discount rate. When risk-free yields—specifically the U.S. 10-year Treasury yield—drift upward, the present value of future cash flows for high-growth, long-duration technology assets contracts sharply. Consequently, any hawkish signal from the Federal Reserve, catalyzed by a hotter-than-expected CPI print, risks triggering a cascading de-rating across both growth and cyclical equities. Market liquidity, while robust, could evaporate rapidly if algorithmic trading models and systematic macro funds are forced to unwind leveraged long positions simultaneously.
Decoding the Macro Crosswinds: Energy, Commodities, and Yields

The macroeconomic backdrop heading into the mid-August trading week is defined by a complex web of crosscurrents. Fixed-income investors are monitoring sovereign debt auctions with heightened scrutiny, parsing every word from Federal Reserve officials for clues regarding the timing and magnitude of upcoming monetary policy adjustments. At the same time, the commodities market is sending mixed signals that complicate the inflation outlook.
Crude oil WTI futures hovering near $83.38 per barrel represent a persistent floor for energy costs, directly impacting transportation, manufacturing, and consumer discretionary sectors. Simultaneously, idiosyncratic price spikes in core agricultural commodities—such as staple food items and eggs—continue to erode consumer purchasing power at the retail level. This persistent cost-of-living pressure complicates the Federal Reserve's dual mandate, forcing policymakers to weigh the risks of premature easing against the dangers of maintaining restrictive interest rates for too long.
Corporate balance sheets are feeling the squeeze as well. While mega-cap technology firms boast pristine debt-to-equity ratios and substantial cash reserves, small- and mid-cap enterprises (represented by the Russell 2000) face significant refinancing walls. For these firms, sustained high borrowing costs threaten profit margins, making them acutely vulnerable to any macroeconomic shock that delays monetary relief.
| Economic Indicator / Asset Class | Current Market Level | Consensus Expectations | Potential Market Impact |
|---|---|---|---|
| Headline CPI (YoY) | Prior: ~2.9% | Expected flat to minor uptick | High volatility across all asset classes; direct hit to rate-cut bets. |
| Crude Oil (WTI) | $83.38 / Bbl | Range-bound | Maintains cost pressures on transport and industrial supply chains. |
| U.S. 10-Year Treasury Yield | Tracking ~4.25% - 4.40% | Sensitive to inflation surprises | Spike above 4.50% would trigger equity multiple contraction. |
| S&P 500 Valuation (P/E) | Trailing/Forward ~21x+ | Priced for earnings resilience | Vulnerable to sharp retracement if discount rates rise unexpectedly. |
Industry & Market Implications: Who Wins, Who Loses
The intersection of record equity valuations and sticky inflation creates clear winners and losers across the financial ecosystem. Institutional portfolio managers are actively repositioning their portfolios to weather potential turbulence.
- Winners — Energy and Defensive Value Sectors: Integrated oil majors, pipeline operators, and commodity-linked equities stand to benefit directly from sustained higher energy prices (WTI at $83.38/bbl). Similarly, defensive sectors such as healthcare, consumer staples, and regulated utilities offer earnings stability that insulates them from growth-stock volatility.
- Losers — High-Multiple Growth and Long-Duration Tech: Software-as-a-Service (SaaS) providers, pre-revenue technology startups, and highly leveraged growth companies face severe headwinds. If inflation prints hot and pushes bond yields higher, the cost of capital surges, crushing speculative valuation multiples.
- The Banking and Credit Complex: Commercial banks face a nuanced environment. While higher-for-longer interest rates support net interest margins (NIM), persistent borrowing costs elevate credit default risks within commercial real estate (CRE) and consumer credit portfolios.
Frequently Asked Questions (People Also Ask)
Why is this week’s CPI report so critical for record-setting U.S. stocks?
U.S. equity markets have scaled historic highs largely on the expectation that inflation is subdued and the Federal Reserve will aggressively cut interest rates. A hotter-than-expected CPI print would challenge this narrative, driving bond yields higher, increasing the cost of capital, and triggering a sharp multiple contraction for richly valued technology and growth stocks.
How do crude oil prices ($83.38 WTI) influence the broader inflation trajectory?
Crude oil is a primary input cost across global manufacturing, logistics, and consumer goods supply chains. When WTI holds firm at elevated levels near $83.38 per barrel, it feeds directly into headline inflation metrics and prevents core transportation and goods costs from declining as rapidly as central bankers desire.
What actions are institutional asset managers taking for risk mitigation ahead of the data?
Sophisticated allocators are trimming exposure to frothy, high-multiple equities, increasing cash buffers, and utilizing options structures (such as protective puts and collar strategies) to hedge against sudden downside volatility. Many are also rotating capital into short-duration fixed income and defensive equity sectors.
How will the Federal Reserve likely react if inflation prints above consensus?
If inflation proves sticky or accelerates, Federal Reserve officials will likely adopt a more hawkish posture, signaling that benchmark interest rates must remain restrictive for an extended duration. This stance would push back market expectations for imminent rate cuts and elevate short-term borrowing costs.
Future Outlook: What Comes Next and Key Milestones to Watch
As Wall Street navigates the pivotal August 12 CPI release, the broader trajectory for the remainder of 2026 hinges on the delicate interplay between macroeconomic data and corporate earnings delivery. If inflation prints in line with or below consensus, the path of least resistance for equities may remain upward, fueled by lingering FOMO (fear of missing out) and robust corporate buyback programs.
However, should inflation surprise to the upside, institutional investors must prepare for a rigorous regime change. The era of easy monetary policy would be officially deferred, forcing a brutal reckoning with elevated valuation multiples. Beyond this week's inflation print, market participants must maintain a vigilant watch on upcoming Producer Price Index (PPI) releases, retail sales figures, and labor market reports as the Federal Reserve’s autumn policy meeting approaches. In this high-stakes environment, disciplined capital allocation, rigorous risk mitigation, and a keen focus on balance sheet resilience will separate the surviving portfolios from the casualties of a shifting economic tide.