Executive Takeaways
- Executive Action: President Trump’s newly signed directive compels the Federal Reserve and banking regulators to audit and dismantle institutional barriers restricting digital asset firms from accessing master accounts and payment rails.
- Capital Allocation Shift: The order promises to unlock trillions in dormant market liquidity, driving a massive wave of enterprise ROI, institutional valuation multiples, and infrastructure scalability.
- Risk Mitigation & Compliance: Financial institutions face heightened regulatory compliance mandates as federal agencies balance systemic risk mitigation with the integration of decentralized financial architecture.
- Market Re-rating: Traditional banking gatekeepers are undergoing forced reviews of their de-risking practices, signaling a profound shift in U.S. monetary and digital asset policy.
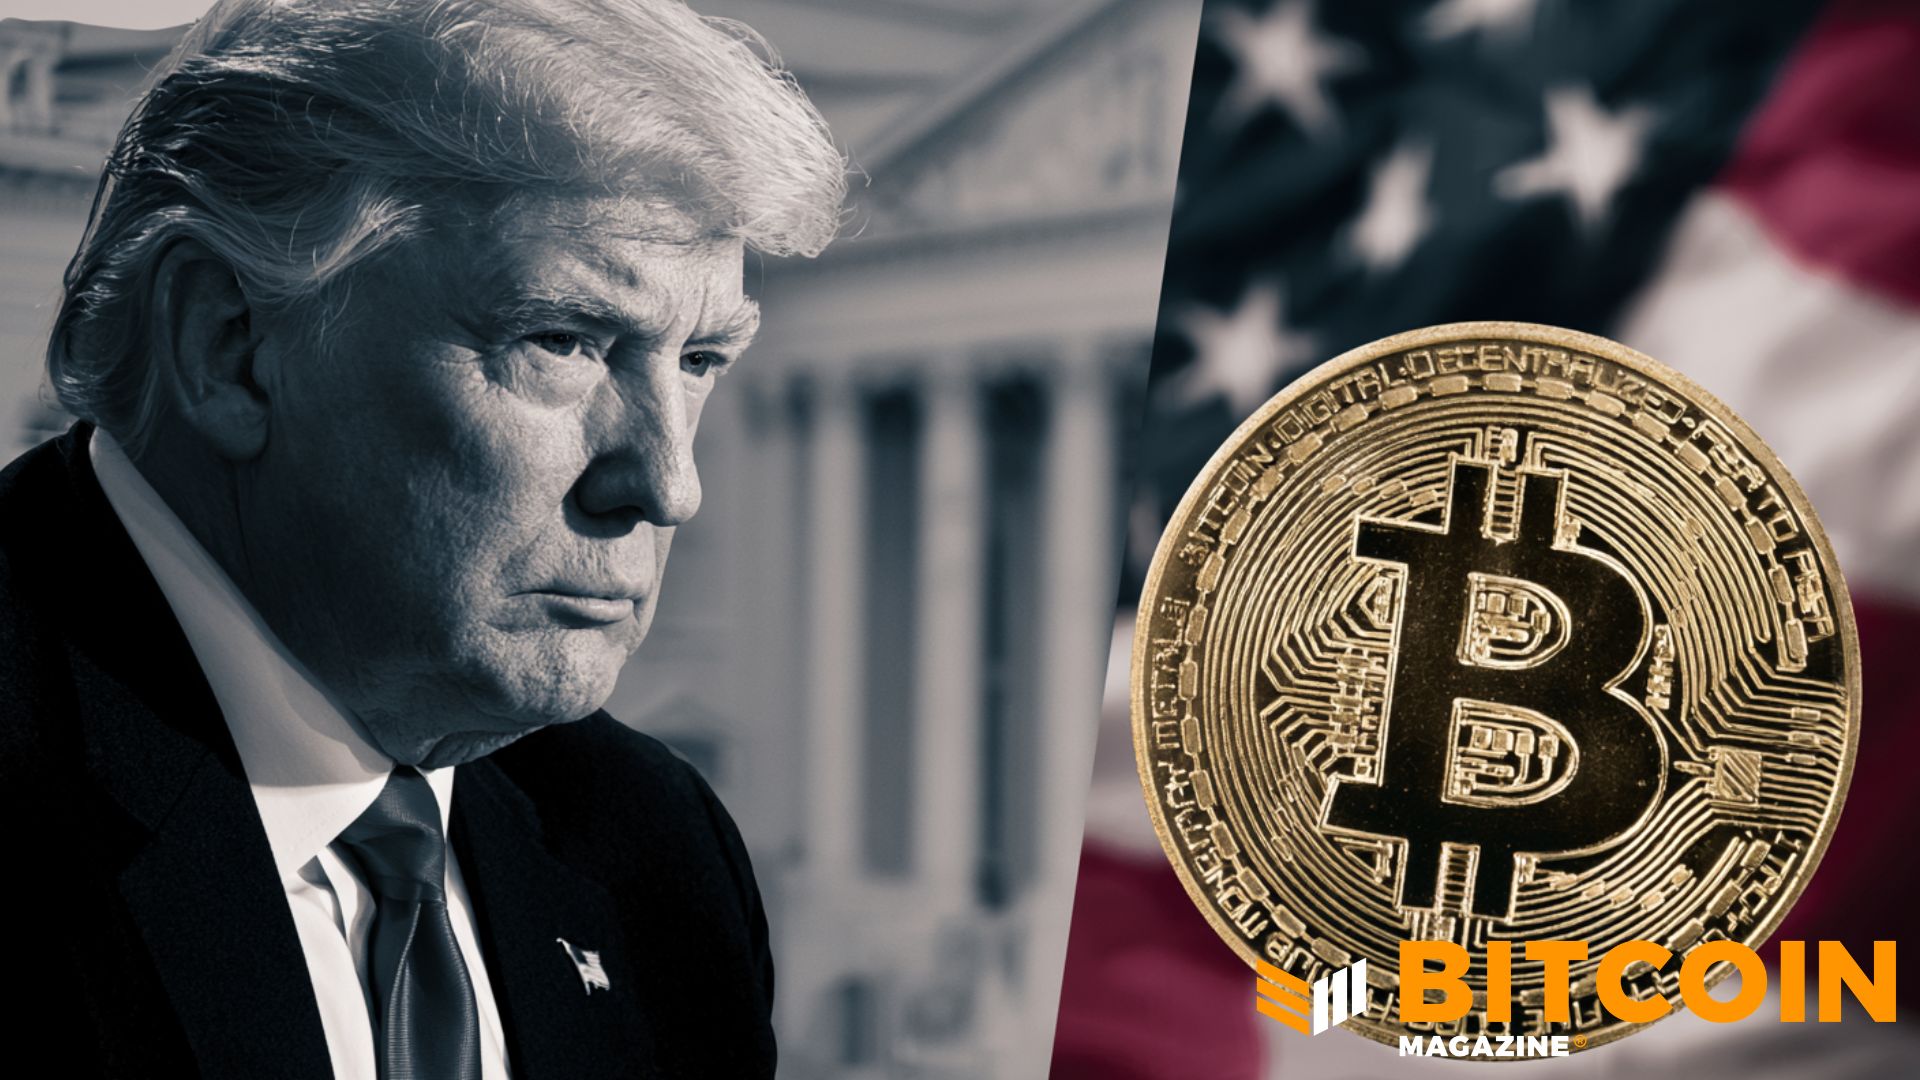
WASHINGTON — In a sweeping executive maneuver that fundamentally reshapes the architecture of American finance, the White House has formally ordered the Federal Reserve and federal banking regulators to review and overhaul access to critical payment systems for digital asset enterprises. The directive, tracked closely by primary wire sources including Bitbo, strikes directly at the heart of systemic "de-banking"—a phenomenon that has long constrained market liquidity, choked enterprise ROI, and stifled innovation across the Web3 sector.
For years, cryptocurrency exchanges, custody providers, and decentralized finance (DeFi) protocols have navigated an adversarial regulatory landscape characterized by opaque restrictions on traditional banking relationships. By mandating an immediate review of payment access and master account eligibility, the administration’s directive signals a watershed moment for capital allocation, cloud compute architecture integration within legacy finance, and institutional valuation multiples across the fintech sector.
The Catalytic Anatomy of "Operation Choke Point 2.0"
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
To understand the profound economic gravity of this executive order, one must examine the institutional friction that preceded it. Over the past several cycles, digital asset firms have systematically encountered what industry executives term structural exclusion. Traditional tier-1 commercial banks, operating under informal yet potent guidance from regulatory agencies such as the Federal Reserve, the Federal Deposit Insurance Corporation (FDIC), and the Office of the Comptroller of the Currency (OCC), engaged in aggressive de-risking campaigns.
This risk mitigation strategy manifested as wholesale termination of banking services for blockchain-native startups, institutional liquidity providers, and crypto asset managers. Consequently, firms were forced to rely on niche, fragile regional banking partners—vulnerable to systemic contagion, as evidenced during the regional banking crises of recent years. The resulting fragmentation severely impaired market liquidity, inflated transaction friction, and introduced structural inefficiencies into institutional portfolio management.
The new executive order targets these administrative bottlenecks head-on. By compelling the Federal Reserve to establish transparent, objective, and legally sound criteria for master account access, the directive dismantles the discretionary gatekeeping that has plagued the sector. Financial institutions and payment networks can no longer justify blanket rejections of digital asset entities under vague safety and soundness pretexts, provided those entities meet rigorous anti-money laundering (AML) and know-your-customer (KYC) standards.
Economic Mechanics: Unlocking Market Liquidity and Valuation Multiples

The macroeconomic implications of normalized payment access for digital asset firms extend far beyond the cryptocurrency ecosystem, directly impacting global capital markets and enterprise technology deployment.
When crypto enterprises are denied direct access to Federal Reserve master accounts and Automated Clearing House (ACH) networks, capital must travel through convoluted, high-cost intermediary channels. This friction introduces systemic counterparty risk and compresses valuation multiples for fintech and blockchain infrastructure providers. With the federal government now enforcing open, merit-based access to payment rails, the friction disappears.
- Institutional Capital Inflows: Asset managers and pension funds can seamlessly allocate capital into digital assets without navigating precarious offshore banking bridges or inefficient custody arrangements.
- Infrastructure Scalability: Enterprise blockchain platforms can integrate natively with traditional banking APIs, optimizing cloud compute architecture and transaction settlement speeds.
- Cost of Capital Reduction: Eliminating banking discrimination lowers operational overhead, directly improving enterprise ROI for venture-backed digital asset startups and established market makers alike.
Furthermore, this policy shift triggers a fierce competitive dynamic among commercial banks. Forward-thinking institutions that have invested heavily in digital asset custody and tokenization infrastructure are now positioned to capture high-margin corporate deposits and transaction fee revenue, challenging legacy institutions that previously relied on exclusionary tactics.
| Metric / Parameter | Pre-Directive Status Quo | Post-Directive Projection |
|---|---|---|
| Federal Reserve Master Account Access | Protracted delays, discretionary denials, systemic ambiguity | Standardized, transparent review timelines with legal recourse |
| Institutional Market Liquidity | Siloed across fragile regional networks and offshore entities | Deepened domestic liquidity pools via tier-1 bank integration |
| Regulatory Compliance Framework | Informal guidance and inconsistent supervisory pressure | Codified rules prioritizing risk mitigation over exclusion |
| Enterprise ROI & Valuation Multiples | Suppressed by high legal overhead and banking friction | Expanded multiples driven by lower operational cost of capital |
Navigating Risk Mitigation and Regulatory Compliance
Critics of the administration's order argue that forcing banks to service digital asset firms could inadvertently introduce systemic vulnerabilities into the traditional banking system. However, senior financial economists and regulatory compliance experts emphasize that the directive does not compromise safety standards. Instead, it shifts the focus from administrative avoidance to active, quantifiable risk mitigation.
Under the new mandates, digital asset firms seeking payment rails must satisfy rigorous compliance audits, including real-time transaction monitoring, robust AML protocols, and verified capitalization reserves. Rather than treating cryptocurrency as an unmitigated hazard, the policy establishes a structured framework that integrates digital asset operations into the supervised federal safety net.
This dual approach protects the broader economy while allowing institutional capital to flow freely. Financial institutions must upgrade their internal compliance infrastructure, utilizing advanced analytics and cloud compute architecture to monitor blockchain data streams with unprecedented precision.
Frequently Asked Questions (People Also Ask)
What does the executive order mean for cryptocurrency firms seeking bank accounts?
The executive order directs the Federal Reserve and banking regulators to establish transparent, objective criteria for digital asset firms applying for master accounts and payment system access. It curtails the practice of arbitrary de-banking, ensuring qualified crypto enterprises receive fair evaluation based on statutory compliance rather than regulatory discretion.
How does this policy change impact market liquidity and capital allocation?
By removing barriers to traditional banking infrastructure, the directive bridges the gap between institutional capital and digital assets. This integration deepens domestic market liquidity, lowers transaction costs, and allows institutional investors to allocate capital more efficiently across regulated financial products.
Will traditional banks be forced to take on excessive risk?
No. The order mandates merit-based access, not unconditional approval. Banks and regulatory agencies retain the authority to reject entities that fail to meet strict risk mitigation, anti-money laundering (AML), and know-your-customer (KYC) standards. The focus is shifted from wholesale exclusion to rigorous, transparent risk management.
What are the broader implications for fintech infrastructure and cloud compute architecture?
As payment rails open up, fintech and blockchain firms can integrate natively with legacy banking APIs. This technological convergence accelerates demand for scalable cloud compute architecture, enhances enterprise ROI, and drives higher valuation multiples across the digital financial services sector.
Future Outlook: Milestones and Market Trajectory
As the Federal Reserve and regulatory agencies draft implementation guidelines in response to the White House directive, market participants are monitoring several critical milestones over the coming quarters:
- Regulatory Rulemaking Timelines: Deadlines for the Federal Reserve to publish standardized master account application frameworks and adjudication metrics.
- Commercial Bank Adoption: The speed at which tier-1 commercial lenders re-engage with institutional digital asset clients and roll out integrated custody services.
- Litigation & Legislative Follow-Through: Potential congressional action to codify payment access rights, ensuring long-term regulatory certainty regardless of future executive administrations.
Ultimately, this executive action marks a definitive turning point in U.S. financial history. By dismantling the institutional barriers that isolated digital assets from traditional banking, the administration has laid the groundwork for a modernized, highly liquid, and deeply integrated global financial architecture where traditional and decentralized capital markets converge.