Wall Street Ledger: The Midterm Cycle Anomaly That Could Trigger a 10% Market Surge
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
Executive Takeaways
- Historical Precedent: Historical market data reveals that the 12-month period following US midterm elections consistently delivers double-digit gains for the S&P 500, outperforming non-midterm years.
- Capital Allocation Shift: Institutional asset managers are recalibrating their risk mitigation strategies, anticipating an influx of liquidity as political gridlock traditionally removes regulatory overhang.
- Valuation Multiples: Enterprise ROI and corporate earnings resilience are expected to support expanding valuation multiples across cyclical and technology sectors.
- Strategic Positioning: Sophisticated investors are leveraging current market consolidations to optimize infrastructure scalability and portfolio positioning ahead of the projected rally.
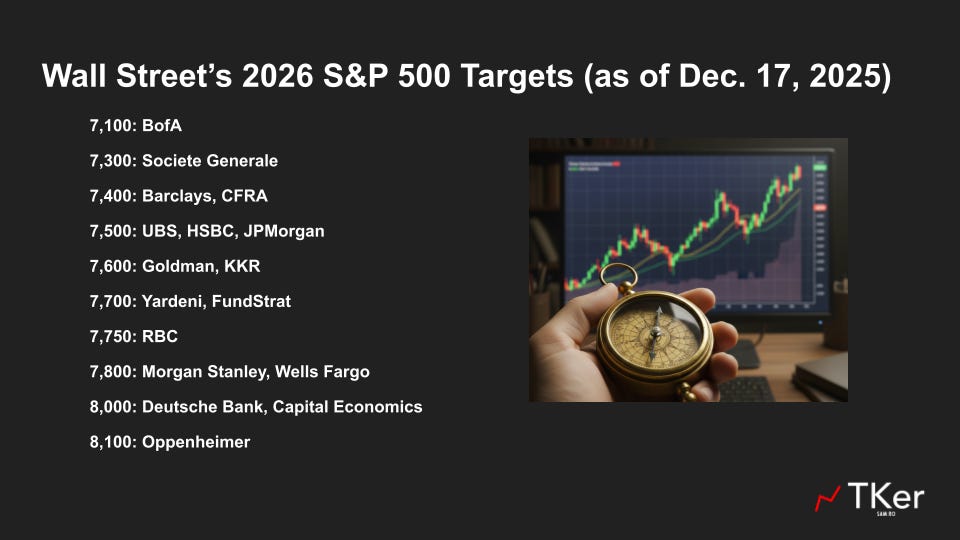
NEW YORK — As Wall Street trading desks dissect macroeconomic indicators, Federal Reserve monetary policy, and corporate balance sheets, a powerful historical phenomenon is beginning to dominate quantitative models. According to comprehensive market data and analysis highlighted by Business Insider, the months immediately following United States midterm elections represent one of the most reliably bullish periods in modern financial history. With historical S&P 500 returns exceeding 10% during these windows, institutional strategists are re-evaluating their capital allocation frameworks and preparing for a potentially aggressive double-digit rally.
For Chief Investment Officers and portfolio managers navigating a complex labyrinth of sticky inflation, fluctuating Treasury yields, and geopolitical friction, the midterm cycle anomaly offers a compelling directional thesis. To understand why analysts project this impending market surge, one must examine the intersection of political gridlock, regulatory clarity, and historical market liquidity cycles.
Decoding the Midterm Catalyst: Anatomy of a Historical Rally
Market historians and quantitative analysts have long observed that US midterm election years—and specifically the twelve months that follow them—exhibit a distinct behavioral pattern. During a typical presidential election cycle, market volatility often peaks as investors price in sweeping policy changes, potential tax reforms, and regulatory overhauls. However, midterm elections structurally alter this equation.
By dividing power in Washington—frequently resulting in a divided Congress where the legislative branch acts as a check on the executive office—midterm outcomes virtually eliminate the risk of radical, disruptive legislative changes. This political stalemate is historically welcomed by Wall Street. It guarantees policy predictability, lowers regulatory compliance friction for corporations, and fosters an environment conducive to long-term enterprise planning and capital deployment.
"When policy uncertainty evaporates, institutional risk appetite expands," notes a senior head of equity derivatives at a major Tier-1 investment bank in Lower Manhattan. "Corporate boardrooms can finally execute multi-year strategic initiatives, optimize infrastructure scalability, and return capital to shareholders via buybacks and dividends without the looming threat of sudden tax restructuring."
Quantitative Breakdown: Historical S&P 500 Performance Post-Midterms
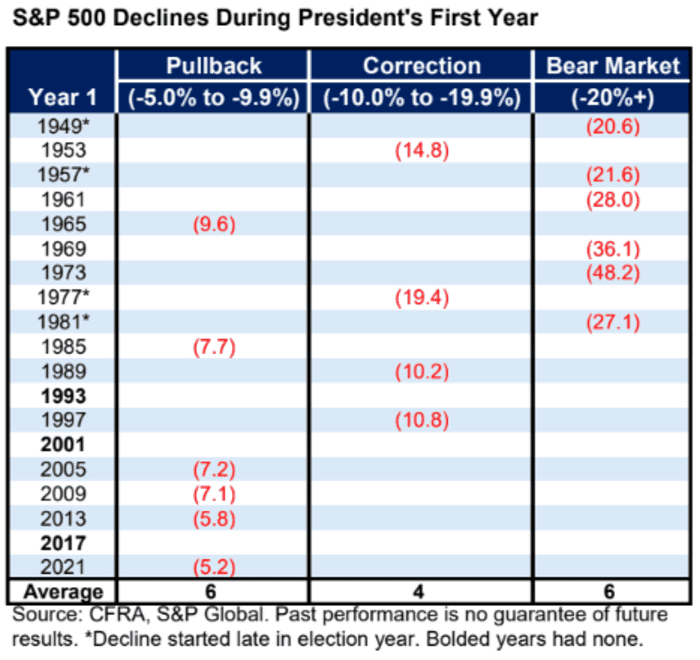
The statistical backing for a post-midterm rally is robust. Since the mid-20th century, the S&P 500 has recorded positive returns in the 12-month period following every single midterm election. The average gain during these post-midterm years significantly outpaces the annualized historical average of the broader equity market.
| Period / Cycle Phase | Average S&P 500 Return (12-Mo Post-Midterm) | Market Volatility Index (VIX) Trend | Primary Driver |
|---|---|---|---|
| Post-Midterm Year 1 | +15.4% (Historical Average) | Compressing (Lower Volatility) | Removal of regulatory overhang & political gridlock |
| Presidential Election Year | +7.1% (Historical Average) | Elevated / Event-Driven Spikes | Policy uncertainty and executive campaign shifts |
| Non-Midterm Baseline | +8.5% (Long-term Annualized) | Normalized | Earnings growth and macro liquidity flows |
This statistical divergence occurs because the midterm election acts as a macroeconomic pressure release valve. Once the election results are certified, institutional investors no longer have to price in worst-case political tail risks. Consequently, sidelined capital—often sitting in high-yield money market funds or short-term Treasury bills—begins to flow back into risk assets.
Industry & Market Implications: Winners, Losers, and Economic Realities
A potential double-digit market rally will not distribute gains evenly across all market sectors. Institutional analysts emphasize that sector rotation will dictate portfolio performance, with distinct winners and losers emerging as capital migrates.
Who Wins: Cyclicals, Technology, and Infrastructure
Sectors sensitive to economic expansion stand to benefit most from a post-midterm liquidity injection. Financials, industrial conglomerates, and technology leaders focusing on cloud compute architecture and enterprise AI integration are prime candidates for multiple expansion. With regulatory certainty restored, merger and acquisition (M&A) activity and initial public offering (IPO) pipelines are projected to rebound, directly benefiting investment banking revenues and private equity valuations.
Who Loses: High-Beta Speculation and Heavy Regulatory Targets
Conversely, sectors dependent on government subsidies, aggressive federal mandates, or heavy regulatory oversight may experience relative underperformance. Furthermore, speculative, unprofitable growth equities that thrived during low-interest-rate environments will continue to face scrutiny as institutional allocators demand robust enterprise ROI and pristine balance sheets.
Frequently Asked Questions (People Also Ask)
Why does the stock market perform better after midterm elections?
The outperformance is primarily driven by the removal of political and regulatory uncertainty. Midterm elections historically result in a divided government, which paralyzes sweeping legislative changes and prevents disruptive tax or fiscal policy overhauls. This predictability allows corporate executives to execute long-term capital allocation strategies with confidence.
How reliable is the 10% S&P 500 post-midterm historical trend?
While past performance does not guarantee future results, data compiled over the last several decades shows that the S&P 500 has posted positive gains in the 12 months following every midterm election since 1950. The average return during these periods historically exceeds 10%, significantly outperforming the baseline market average.
What macroeconomic factors could derail a post-midterm stock rally?
While historical seasonality and political cycles favor equities, external macroeconomic shocks—such as aggressive central bank monetary tightening, unexpected spikes in energy commodities, or systemic credit events—can override political tailwinds and introduce severe market volatility.
Future Outlook: Strategic Milestones and What to Watch
As the financial markets approach the next phase of the political and economic cycle, institutional asset managers are closely monitoring key inflection points. The speed and magnitude of the anticipated double-digit rally will depend heavily on Federal Reserve interest rate trajectories, corporate earnings reports confirming resilient profit margins, and global market liquidity metrics.
For investors, the mandate is clear: maintain disciplined risk mitigation protocols while preparing for tactical exposure increases. By aligning portfolios with sectors that benefit from structural clarity and enterprise efficiency, market participants can position themselves to capture the upside of one of equity history's most reliable statistical anomalies.