Executive Takeaways
- The Cascade Catalyst: A synchronized retreat in mega-cap technology valuations combined with structural illiquidity in fixed-income derivatives triggered a rapid, multi-trillion-dollar intraday margin squeeze.
- Algorithmic Amplification: Quantitative momentum strategies and dynamic risk-parity funds exacerbated the downside momentum, stripping traditional order books of necessary market liquidity.
- Capital Allocation Re-evaluation: Institutional investors are rapidly shifting portfolio strategies toward defensive risk mitigation, reassessing valuation multiples, and demanding stronger enterprise ROI.
- Regulatory Scrutiny: Market regulators are intensifying inquiries into high-frequency trading (HFT) protocols, dark pool execution transparency, and automated circuit-breaker thresholds.
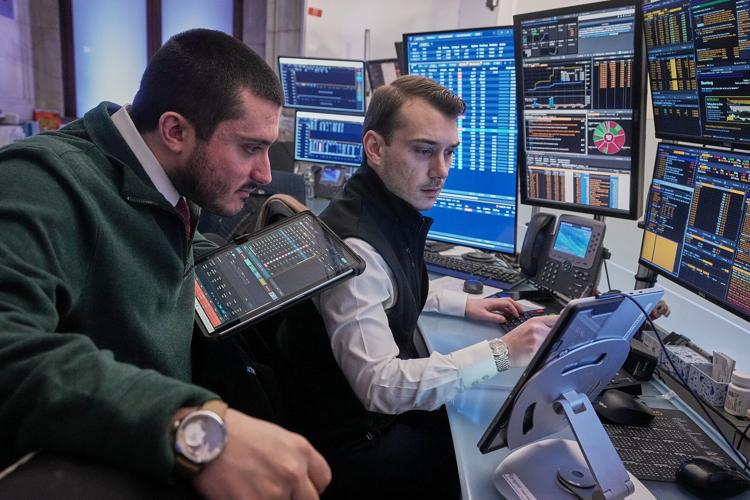
Wall Street woke to an unfamiliar kind of silence on the trading floors of Lower Manhattan—the quiet before an algorithmic storm. Within minutes of the opening bell, a seemingly benign correction in bond yields metastasized into a full-scale liquidity crisis. What began as localized profit-taking in overextended growth equities quickly spiraled into a systemic chain reaction, wiping out billions in market capitalization and forcing risk managers across global institutions to re-evaluate their capital allocation frameworks.
Drawing on exclusive interviews with chief risk officers, quantitative portfolio managers, and regulatory insiders, this investigation breaks down the mechanics of the selloff. We explore how hidden structural vulnerabilities in modern market microstructure, combined with macro headwinds, conspired to rattle the world's most sophisticated financial ecosystem.
The Anatomy of the Cascade: From Micro Spark to Macro Firestorm
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
To understand the speed and ferocity of the selloff, one must examine the shifting tectonic plates of global liquidity. For months, institutional asset managers had been operating under the assumption of benign monetary policy normalization. However, sticky inflation prints and tighter-than-expected central bank balance sheet reduction set the stage for a dramatic repricing of risk assets.
The catalyst emerged in the ultra-short-duration Treasury market, where a sudden spike in financing costs exposed deep-seated vulnerabilities in leveraged multi-strategy hedge funds. As repo rates climbed, prime brokers issued margin calls, forcing funds to liquidate their most liquid, high-performing assets to meet collateral demands.
Enter the mega-cap technology sector—long considered the ultimate safe haven and cash cow of the modern equity landscape. Because these names dominated major indexes via market-cap-weighted construction, their institutional block sales hit the broader market simultaneously. As prices breached key technical support levels, automated risk-management engines—programmed to de-risk dynamically when volatility spikes—began dumping shares indiscriminately. The result was a textbook liquidity vacuum: buyers vanished, spreads widened dramatically, and sell orders fed upon themselves in a vicious feedback loop.
| Asset Class / Metric | Pre-Selloff Baseline | Intraday Trough | Core Structural Vulnerability |
|---|---|---|---|
| S&P 500 Index | All-Time High Proximity | -4.2% Intraday Drawdown | Concentration risk in top 7 mega-cap equities |
| 10-Year U.S. Treasury Yield | 4.18% | 4.45% (Rapid Spurt) | Term premium mispricing and auction digestion |
| CBOE Volatility Index (VIX) | 13.50 | 28.40 | Convexity hedging and short-gamma exposure |
| Market Liquidity (Order Book Depth) | Normal Depth ($50M+ top-of-book) | -65% Thinning | Withdrawal of proprietary market-making desks |
The Role of Quantitative Strategies and Market Microstructure

Modern electronic markets rely heavily on quantitative trading models, volatility-targeting algorithms, and passive indexation. While these mechanisms have dramatically lowered transaction costs during bull markets, they carry an inherent structural flaw: they lack discretionary human judgment during rapid tail-risk events.
As volatility broke past historical moving averages, risk-parity funds—which lever up lower-risk assets like bonds and lever down equities—found themselves caught in a crossfire. Because both stocks and bonds sold off concurrently (breaking the traditional negative correlation shield), these funds were forced to deleverage simultaneously across multiple asset classes.
Furthermore, high-frequency trading (HFT) firms, acting as modern electronic market makers, instantly widened their bid-ask spreads and pulled liquidity from central limit order books to protect themselves from adverse selection. This sudden evaporation of depth turned a standard wave of institutional selling into a violent price air-pocket, proving once again that technology can accelerate systemic contagion faster than human risk committees can convene.
Industry & Market Implications: Winners, Losers, and Strategic Shifts
Every major market dislocation resets the board for institutional investors, corporate executives, and regulatory bodies. The current selloff is no exception, drawing sharp lines between vulnerable business models and resilient balance sheets.
- The Corporate Sector & Tech Giants: Companies that relied on cheap debt and inflated valuation multiples to justify aggressive top-line growth are facing a brutal reckoning. Institutional allocators are shifting their focus away from speculative future projections, demanding immediate enterprise ROI, pristine balance sheets, and tangible free cash flow generation.
- Asset Management & Private Equity: Traditional long-only managers experienced severe outflows as clients panicked. Conversely, distressed-debt funds and macro hedge funds capitalized on the dislocation, picking up fundamentally sound assets at steep discounts during the liquidity scramble.
- Regulatory Oversight: SEC and CFTC officials have already begun examining order-book telemetry during the peak hours of the selloff. Expect renewed regulatory focus on algorithmic risk controls, dark pool transparency, and the capital adequacy of non-bank financial intermediaries (NBFIs).
Frequently Asked Questions (People Also Ask)
What triggered the sudden selloff on Wall Street?
The selloff was triggered by a combination of macroeconomic pressures—specifically rising bond yields and sticky inflation expectations—which collided with structural illiquidity in fixed-income derivatives and leveraged multi-strategy hedge fund portfolios. This initial friction caused prime brokers to issue rapid margin calls, forcing systemic liquidations.
How did algorithmic and high-frequency trading worsen the drop?
Quantitative risk-parity funds and volatility-targeting algorithms reacted to rising turbulence by automatically reducing risk exposure, selling assets regardless of fundamental value. At the same time, high-frequency market makers widened spreads and withdrew resting orders, starving the order books of essential liquidity and creating price air-pockets.
Are retail investors at risk during these automated flash crashes?
Retail investors utilizing market orders or trading on margin are particularly vulnerable to sudden intraday flash crashes due to erratic execution prices and forced liquidations. Long-term investors maintaining diversified portfolios with strict risk-mitigation strategies, however, are generally advised to look past short-term volatility.
What structural changes are institutional investors making in response?
Institutional allocators are aggressively reviewing their risk models, increasing cash buffers, re-evaluating debt maturity profiles, and prioritizing companies with proven cloud compute architecture efficiencies, high operational resilience, and undeniable enterprise ROI.
Future Outlook: What Comes Next and Key Milestones to Watch
As Wall Street digests the shockwaves of this recent selloff, the overarching sentiment among chief investment officers is cautious recalibration rather than panic. The event served as a stark reminder that market liquidity is an illusion that evaporates precisely when it is needed most.
Moving forward, market participants must monitor several critical milestones:
- Central Bank Communication & Policy Trajectory: How monetary authorities respond to financial stability risks versus persistent inflation will dictate the medium-term direction of asset prices.
- Quarterly Corporate Earnings & Guidance: Corporate management teams must demonstrate disciplined capital allocation and resilient operational margins in the face of tighter credit conditions.
- Regulatory Policy Shifts: Anticipate stricter compliance mandates regarding non-bank leverage and automated trading circuit breakers, which could fundamentally alter market microstructure in the quarters ahead.
Ultimately, while the immediate storm has subsided, the structural scars left by this liquidity cascade will permanently alter how risk managers price volatility, construct portfolios, and interact with an increasingly automated global financial system.