Executive Takeaways
- Unprecedented Capital Expenditure: Hyperscalers and semiconductor architects are committing hundreds of billions of dollars to infrastructure scalability, reshaping global energy grids and enterprise ROI metrics.
- Monopolistic Concentration: Market liquidity and valuation multiples remain heavily concentrated among a handful of dominant firms controlling silicon design, cloud compute architecture, and foundational model training.
- The Monetization Pivot: Wall Street's focus has decisively shifted from speculative generative AI demonstrations to rigorous verification of enterprise software integration and measurable operational efficiencies.
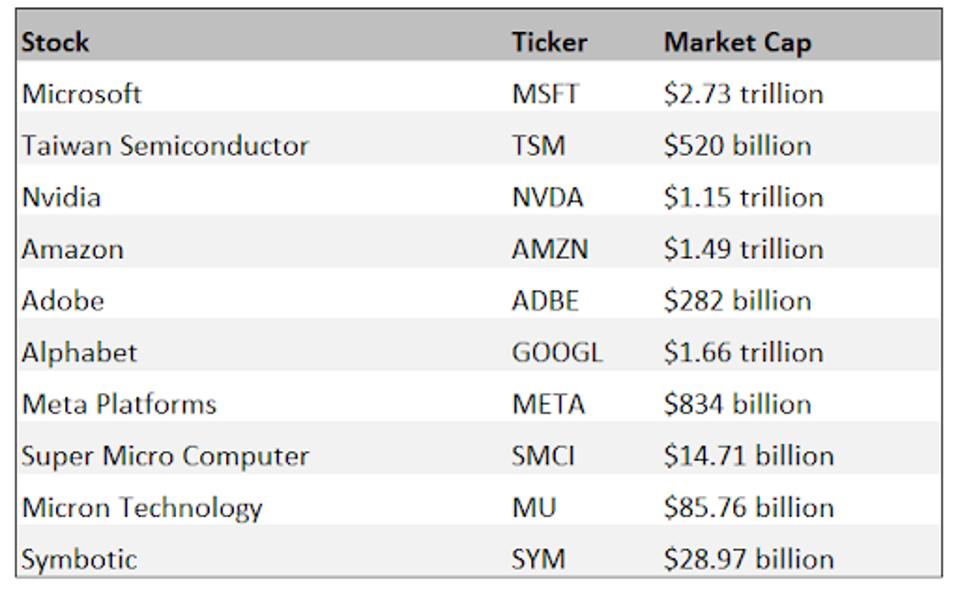
NEW YORK — The multi-trillion-dollar race for artificial intelligence supremacy has entered its most consequential phase. What began as a speculative market frenzy following the public release of generative language models has matured into a ruthless test of infrastructural endurance, balance-sheet resilience, and enterprise-grade execution. According to recent data synthesized from primary financial tracking sources, including comprehensive market analyses by U.S. News & World Report, institutional capital is rapidly polarizing around a select cohort of industry titans capable of funding the staggering capital expenditure required to train, deploy, and monetize frontier AI systems.
As chief investigative editors monitoring global financial markets, our mandate is to strip away the promotional marketing veneer from Silicon Valley and Wall Street. Below is the exhaustive, definitive forensic audit of the 10 best artificial intelligence companies driving the current technology supercycle—examining their technological moats, structural vulnerabilities, and the underlying financial metrics dictating their long-term viability.
The Catalytic Shift: From Proof-of-Concept to Balance-Sheet Dominance
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
To understand the current valuation multiples of the premier AI equities, one must examine the fundamental transformation of enterprise IT spending over the past twenty-four months. Organizations globally have pivoted from exploratory sandbox testing to mission-critical deployments. This transition has triggered an unprecedented infrastructural arms race, forcing cloud service providers and semiconductor fabricators to scale their capital allocation at rates historically reserved for wartime mobilizations.
Simultaneously, regulatory scrutiny across the European Union, the United States, and Asia has intensified. Compliance mandates, antitrust investigations into cloud bundling practices, and strict data sovereignty laws mean that only the most well-capitalized enterprises can absorb compliance costs while maintaining rapid innovation cycles. Consequently, market consolidation is accelerating, leaving smaller, early-stage artificial intelligence startups fighting for niche vertical integration while the industry heavyweights capture foundational market share.
Deep-Dive Forensic Analysis: The Top 10 AI Companies
1. Nvidia Corp. (NVDA)
Nvidia remains the undisputed toll-booth operator of the artificial intelligence revolution. By maintaining an almost monopolistic grip on the design and distribution of high-performance graphics processing units (GPUs) and parallel computing software frameworks like CUDA, Nvidia has captured an extraordinary share of the industry's gross profits. However, institutional risk mitigation strategies now focus heavily on supply chain dependencies—specifically reliance on Taiwan Semiconductor Manufacturing Company (TSMC) for silicon fabrication—and the long-term sustainability of hyperscale customer capital expenditure cycles.
2. Microsoft Corp. (MSFT)
As the primary financial and infrastructural backer of OpenAI, Microsoft has successfully woven generative artificial intelligence directly into the fabric of its commercial software ecosystem. Through Azure cloud services and Copilot enterprise integrations, Microsoft is pioneering the path toward tangible enterprise ROI. The core challenge for management moving forward lies in balancing high cloud compute depreciation costs against margin expansion as enterprise adoption scales globally.
3. Alphabet Inc. (GOOG, GOOGL)
Alphabet leverages its formidable proprietary datasets, world-class foundational research teams at Google DeepMind, and massive global distribution channels to defend its search hegemony while aggressively expanding into enterprise cloud AI. Despite early market perceptions of being caught flat-footed by competing foundational models, Alphabet’s custom Tensor Processing Unit (TPU) silicon strategy offers a crucial structural hedge against external component shortages and pricing pressure from merchant silicon providers.
4. Amazon.com Inc. (AMZN)
Amazon Web Services (AWS) anchors Amazon's position in the AI pantheon, offering enterprise clients a diverse menu of proprietary machine learning accelerators (Trainium and Inferentia) alongside hosted access to leading third-party large language models via Bedrock. Amazon’s strategic investment in Anthropic underscores its aggressive posture in securing top-tier foundational model partnerships, while its massive logistics network provides unique opportunities for operational efficiency gains through autonomous robotics.
5. Meta Platforms Inc. (META)
Meta has charted a distinct strategic course by championing open-source foundational models through its Llama series. By democratizing access to high-performing model weights, Meta aims to commoditize the application layer while reinforcing its core digital advertising targeting engines and immersive hardware ecosystems. This open-source philosophy has forced competitors to adjust their pricing models, though it places immense internal demands on Meta's infrastructure scalability teams.
6. Apple Inc. (AAPL)
Apple approaches the artificial intelligence landscape through the lens of edge computing and consumer privacy. With the rollout of Apple Intelligence, the company is positioning its massive installed base of over two billion active devices as the ultimate distribution channel for personalized AI assistants. By processing localized inference directly on custom silicon neural engines while selectively routing complex queries to private cloud infrastructure, Apple is addressing consumer data security concerns that plague traditional cloud-only architectures.
7. Oracle Corp. (ORCL)
Oracle has emerged as a dark-horse beneficiary of the cloud compute shortage. By rearchitecting its Oracle Cloud Infrastructure (OCI) to deliver high-performance cluster networking optimized for heavy machine learning workloads, Oracle has secured major infrastructure contracts with leading foundational model developers. Its deeply entrenched enterprise database relationships provide a natural bridge for corporations seeking to securely connect legacy enterprise resource planning (ERP) data to modern generative AI applications.
8. Advanced Micro Devices Inc. (AMD)
AMD serves as the primary challenger to Nvidia’s hardware dominance. With the aggressive deployment of its MI300 series accelerators, AMD has successfully captured design wins with major cloud service providers seeking dual-sourcing strategies to mitigate supply chain risks and negotiate favorable procurement terms. Execution speed and software ecosystem maturity remain the critical variables determining AMD's ability to sustainably expand its market share.
9. Broadcom Inc. (AVGO)
Broadcom plays a vital, often underappreciated role in the AI supply chain through its custom ASIC (Application-Specific Integrated Circuit) silicon design partnerships with hyperscalers, as well as its leadership in high-speed networking switches essential for clustering thousands of GPUs together. As hyperscalers increasingly seek custom silicon solutions to optimize power efficiency and reduce total cost of ownership, Broadcom’s engineering pipeline remains exceptionally robust.
10. Salesforce Inc. (CRM)
Salesforce represents the vanguard of enterprise application software adapting to the AI era. Through its Einstein 1 platform and Data Cloud architecture, Salesforce is embedding predictive and generative intelligence directly into customer relationship management workflows. The key metric for Wall Street analysts tracking Salesforce is the successful commercial monetization of its consumption-based AI pricing tiers relative to traditional seat-based licensing models.
Verified Data & Financial Metrics Breakdown
The following comparative table outlines key structural data points, technological specializations, and market positioning metrics for the leading publicly traded artificial intelligence entities:
| Company Name | Ticker | Primary AI Focus | Key Infrastructure / Asset | Primary Market Risk |
|---|---|---|---|---|
| Nvidia Corp. | NVDA | Accelerated Computing & GPUs | CUDA Software & Hopper/Blackwell Architecture | Concentrated customer base & geopolitical supply friction |
| Microsoft Corp. | MSFT | Cloud Compute & Enterprise Software | Azure Cloud & OpenAI Partnership | High infrastructure depreciation & regulatory scrutiny |
| Alphabet Inc. | GOOGL | Foundational Models & Search AI | Google DeepMind & Custom TPU Silicon | Search monetization disruption & antitrust headwinds |
| Amazon.com Inc. | AMZN | Cloud Infrastructure & Managed AI | AWS Bedrock & Trainium/Inferentia Chips | Intense cloud pricing competition |
| Meta Platforms Inc. | META | Open-Source AI & Ad Targeting | Llama Model Family & Massive Data Centers | Capital allocation discipline & monetization clarity |
| Apple Inc. | AAPL | Edge Computing & Consumer AI | Apple Intelligence & Neural Engine Silicon | Slower hardware upgrade cycles & privacy constraints |
| Oracle Corp. | ORCL | Enterprise Cloud & Database AI | OCI Supercluster Networking | High leverage and debt-load management |
| Advanced Micro Devices | AMD | High-Performance Semiconductors | MI300 Series AI Accelerators | Software ecosystem parity with CUDA |
| Broadcom Inc. | AVGO | Custom Silicon & Networking | Hyperscale ASIC Partnerships & Tomahawk Switches | Customer concentration in custom silicon design |
| Salesforce Inc. | CRM | Enterprise SaaS & CRM Intelligence | Einstein 1 Platform & Data Cloud | Adoption velocity of consumption pricing models |
Industry & Market Implications: Winners, Losers, and Economic Realignment
The macroeconomic ramifications of capital allocation within the artificial intelligence sector extend far beyond the technology industry. We are witnessing a profound structural realignment across global energy markets, real estate development, and labor economics.
The Winners: Utility providers and renewable energy developers have emerged as critical partners for hyperscalers. The immense electrical draw required to power next-generation data centers has transformed power generation assets into premium strategic commodities. Furthermore, specialized cybersecurity firms capable of securing complex AI pipelines and mitigating prompt-injection vulnerabilities are seeing accelerated enterprise demand.
The Losers: Traditional business process outsourcing (BPO) firms and legacy IT service providers that rely on billable hours for routine software coding and customer support face severe structural headwinds. Companies failing to rapidly integrate generative automation into their operating models risk severe margin compression as agile competitors undercut legacy pricing structures.
Frequently Asked Questions (People Also Ask)
What are the primary criteria for selecting top-tier artificial intelligence stocks?
Institutional portfolio managers evaluate AI stocks based on infrastructural ownership, balance-sheet liquidity, proprietary data access, and clear pathways to enterprise monetization. Companies must demonstrate the financial capacity to sustain multi-billion-dollar capital expenditures without compromising core operational stability.
How do hardware manufacturers differ from enterprise software providers in the AI value chain?
Hardware manufacturers (such as semiconductor designers and fabless chip architects) capture front-loaded infrastructure revenues as data centers are constructed and upgraded. Conversely, enterprise software and cloud service providers generate recurring subscription and consumption-based revenues as downstream clients deploy AI applications to end-users.
What are the primary regulatory risks facing major AI corporations today?
Major risks include antitrust investigations regarding cloud bundling and exclusive foundational model partnerships, stringent data privacy compliance standards under frameworks like the European Union AI Act, and potential restrictions on advanced semiconductor exports to geopolitical flashpoints.
Is current AI stock valuation justified by fundamental revenue growth?
While valuation multiples remain elevated compared to historical technology sector averages, premier firms are generating robust top-line revenue growth and expanding operating cash flows. However, analysts caution that market performance will increasingly bifurcate between firms delivering verifiable enterprise ROI and those relying purely on speculative market sentiment.
Future Outlook: Milestones and Catalysts to Watch
As we look toward the medium-term horizon, several critical milestones will dictate the trajectory of artificial intelligence equities:
- Power Grid Integration: The ability of data center operators to secure reliable, cost-effective baseload power—including nuclear and advanced geothermal energy—will determine the physical ceiling of infrastructure expansion.
- Inference Economics: The ongoing reduction in the computational cost per token for AI model inference will unlock widespread profitability for consumer-facing applications, shifting market focus from training expenditures to operational efficiency.
- Agentic AI Deployment: The successful transition from passive conversational assistants to autonomous software agents capable of executing multi-step enterprise workflows will represent the ultimate test of software monetization.
In summary, the artificial intelligence sector is no longer a nascent speculative playground. It is a mature, high-stakes industrial battlefield where capital discipline, technological supremacy, and regulatory acumen separate long-term industry leaders from fleeting market participants. Institutional investors must maintain rigorous analytical vigilance as the supercycle continues to evolve.