Billionaire Moon Rush: Inside the High-Stakes Race as SpaceX, Blue Origin, and NASA Clash Over Lunar Infrastructure
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
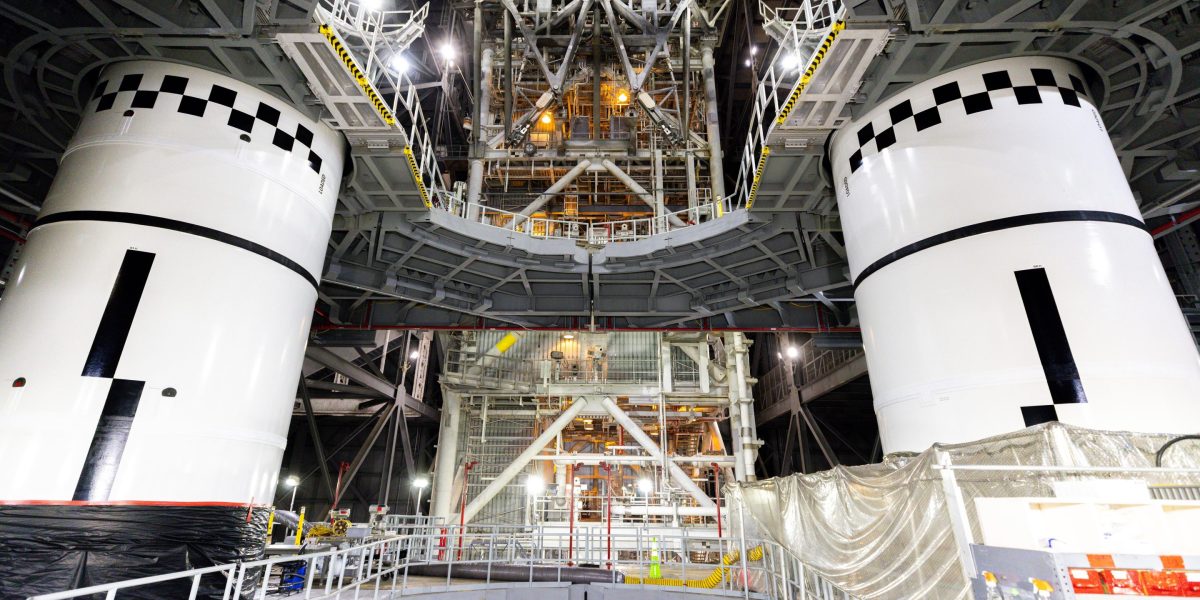
The race to establish a permanent human foothold on the lunar surface has transitioned from speculative science fiction to a high-stakes corporate and geopolitical chess match. As Elon Musk’s SpaceX and Jeff Bezos’ Blue Origin rapidly accelerate their aerospace development cycles to build a sustainable Moon base, NASA leadership—spearheaded by top administrators—finds itself navigating a labyrinth of tight budgets, aggressive timelines, and unprecedented private-sector leverage. This convergence of capital allocation, geopolitical ambition, and revolutionary engineering is reshaping the global defense and aerospace landscape, setting off a scramble for lunar real estate that will dictate the economic and strategic parameters of low-Earth and deep-space commerce for the next century.
For institutional investors, aerospace stakeholders, and defense strategists, the commercialization of cislunar space represents both an extraordinary capital expenditure cycle and a radical shift in infrastructure scalability. With government agencies increasingly relying on public-private partnerships, the traditional cost-plus contracting model is being disrupted by fixed-price, milestone-driven development. As SpaceX prepares its Starship architecture for heavy-lift cargo operations and Blue Origin refines its Blue Moon lander variants, the operational dynamics of the Artemis program are undergoing a profound structural metamorphosis.
Executive Takeaways
- Private-Public Power Dynamic: NASA is shifting from a prime system developer to an anchor tenant, relying heavily on SpaceX and Blue Origin to execute core lunar logistics.
- Capital Expenditure Super-Cycle: Billions in private equity and venture capital are pouring into cislunar infrastructure, driving unprecedented valuation multiples across the aerospace supply chain.
- Strategic Resource Scarcity: The rush to secure water ice deposits at the lunar poles has elevated celestial geography to a matter of national security and long-term enterprise ROI.
- Regulatory & Legal Frontiers: The lack of a codified international legal framework for lunar property rights and resource extraction introduces significant risk mitigation challenges for institutional backers.
The Catalytic Shift: From Apollo Nostalgia to Cislunar Economics
Unlike the geopolitical vanity project of the 1960s Apollo missions, the modern return to the Moon is anchored entirely in commercial viability, technological persistence, and resource utilization. The current trajectory is driven by a stark realization: mastering cislunar logistics is the mandatory precursor to any viable crewed mission to Mars. Consequently, NASA’s architectural roadmap has become inextricably linked to the technological roadmaps of SpaceX and Blue Origin.
SpaceX’s iterative, rapid-prototyping philosophy has redefined aerospace development. By absorbing massive risk through frequent flight tests and internal capital deployment, the company has forced legacy aerospace contractors to reevaluate their operational efficiency and cost structures. Concurrently, Blue Origin—bolstered by Jeff Bezos’ long-term capital allocation strategy and a newly revitalized executive leadership team—has secured critical Human Landing System (HLS) contracts, positioning itself as a formidable counterweight in the heavy-lift sector.
However, this reliance on private-sector behemoths introduces unique governance challenges for NASA administrators. Balancing safety compliance with aggressive launch cadences requires delicate regulatory maneuvering. As NASA works alongside aerospace executives to outline the specifications for a sustainable lunar base—often referred to as Artemis Base Camp—the agency must ensure that technical standards, interoperability protocols, and safety baselines are universally maintained across disparate proprietary systems.
Verified Data & Metrics Breakdown
| Program / Enterprise | Primary Vehicle | Contract / Valuation Scope | Target Lunar Milestone | Strategic Focus |
|---|---|---|---|---|
| NASA (Artemis Program) | Space Launch System (SLS) / Gateway | $93B+ Programmatic Lifecycle Budget | Artemis III Crewed Landing (Late 2020s) | Government oversight, international cooperation, scientific exploration. |
| SpaceX | Starship HLS | $2.89B+ Initial HLS Award (Plus Private Capital) | Uncrewed Demo & Cargo Drops (2026-2027) | Heavy-lift mass delivery, in-space propellant transfer, base infrastructure. |
| Blue Origin | Blue Moon (MK1 / MK2) | $3.4B Sustaining Lunar Development Contract | Uncrewed Cargo Lander Demo (2025-2026) | Heavy cargo transport, solar power generation, sustainable habitat modules. |
Industry & Market Implications: Winners, Losers, and Capital Flows
The transition toward a lunar economy is triggering massive shifts in market liquidity and venture capital allocation. Upstream suppliers specializing in advanced propulsion, cryogenic fluid management, autonomous guidance systems, and radiation-hardened cloud compute architecture are seeing unprecedented demand. Investors evaluating the sector are closely monitoring valuation multiples, looking for firms that possess proprietary intellectual property capable of surviving the harsh thermal and radiative environment of the lunar south pole.
Conversely, traditional aerospace primes that failed to adapt to the agile, fixed-price contracting paradigm face severe margin compression. Companies unable to match the innovation velocity and cost efficiency of New Space enterprises are finding themselves relegated to sub-tier supplier roles or facing dwindling backlogs as NASA pivots its purchasing power toward commercial transport services.
On a macroeconomic scale, the establishment of a Moon base introduces the concept of extraterrestrial resource extraction—specifically water ice, which can be electrolyzed into hydrogen and oxygen rocket propellant. This capability effectively transforms the Moon into a celestial gas station, radically altering the cost equation for deep-space exploration and unlocking new paradigms for enterprise ROI.
Frequently Asked Questions (People Also Ask)
Why are SpaceX and Blue Origin focusing so heavily on the lunar south pole?
The lunar south pole is strategically vital because of permanently shadowed craters that contain vast reserves of water ice. This ice can be converted into life support resources and rocket propellant, enabling the Moon to serve as a refueling hub for deeper space missions and dramatically lowering long-term mission operational costs.
What is NASA’s exact role if private companies are building the Moon base?
While SpaceX and Blue Origin are developing the heavy-lift transport vehicles and landing systems, NASA acts as the primary anchor customer, scientific director, and regulatory coordinator. NASA provides foundational research, safety standards, coordination with international partners via the Artemis Accords, and overarching architectural frameworks for the base.
How are these lunar missions funded?
Funding is a hybrid of federal appropriations through NASA budgetary allocations and massive private capital deployment by billionaires Elon Musk and Jeff Bezos, alongside institutional venture capital backing aerospace supply chain startups and technological innovations.
What are the primary technical hurdles remaining for a permanent lunar base?
Key obstacles include mastering cryogenic propellant storage in space over extended durations, developing autonomous construction equipment to shield habitats from cosmic radiation and micrometeorites, generating reliable long-term power, and managing abrasive lunar regolith that damages mechanical systems.
Future Outlook: Critical Milestones to Watch
As the countdown to initial uncrewed demonstrations ticks down, market observers and aerospace analysts are tracking several critical catalysts. First, the successful execution of uncrewed lunar landing tests by both SpaceX and Blue Origin will serve as the ultimate litmus test for their respective technical architectures. Second, regulatory developments concerning property rights under the Outer Space Treaty will dictate how aggressively private enterprises can monetize lunar assets.
Ultimately, the convergence of government ambition and private-sector capital is forging a new economic frontier. The entities that successfully navigate regulatory compliance, technological scaling, and capital allocation over the next five years will not only dictate the architecture of the Artemis Base Camp but will also capture the foundational economic high ground of the cislunar century.