Executive Takeaways
- Unprecedented Cash Generation: Supermajor oil and gas corporations are posting successive quarters of astronomical net income, rivaling historical peaks driven by persistent global supply constraints and robust downstream margins.
- shift in Capital Allocation: Unlike previous commodity supercycles dominated by aggressive frontier exploration, current corporate strategies prioritize disciplined enterprise ROI, aggressive debt reduction, and enhanced shareholder returns via share buybacks and high dividend yields.
- Regulatory and ESG Friction: The swelling cash reserves are intensifying scrutiny from policymakers, environmental groups, and institutional investors navigating stringent regulatory compliance and long-term decarbonization mandates.
- Macroeconomic Volatility: While balance sheets remain fortified with exceptional market liquidity, executives face acute risk mitigation challenges regarding geopolitical flashpoints, OPEC+ production quotas, and shifting global energy demand curves.
For the third consecutive reporting cycle, the world’s premier publicly traded energy conglomerates have delivered financial results that defy broader macroeconomic headwinds. As central banks grapple with sticky inflation and manufacturing sectors across Europe and Asia experience protracted stagnation, integrated oil and gas giants are once again posting staggering net profits. This latest surge in corporate earnings underscores a fundamental reality of the contemporary global economy: despite aggressive capital expenditure into renewable infrastructure and energy transition initiatives, traditional hydrocarbons remain the primary engine of global financial performance.
Interviews with senior industry executives, equity research analysts, and commodities traders reveal a complex narrative. The windfall is not merely a byproduct of volatile spot prices, but the result of rigorous structural cost-cutting, optimized cloud compute architecture for reservoir modeling, and highly disciplined capital allocation frameworks implemented in the wake of the 2020 market collapse. These operational efficiencies have permanently lowered the cash breakeven point for major operators, allowing them to capture unprecedented margins even during periods of moderate commodity price corrections.
The Catalytic Drivers Behind the Balance Sheet Expansion
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
To understand how enterprise valuations have decoupled from traditional industrial indices, one must examine the confluence of geopolitical friction, structural underinvestment in upstream assets, and robust downstream refining cracks. Over the past twenty-four months, structural under-investment in long-cycle exploration projects has created an inelastic supply environment. When global demand proved resilient against monetary tightening, operators with diversified portfolios found themselves generating massive operational cash flow.
Furthermore, technological modernization has played a silent yet pivotal role. Upstream operators have increasingly integrated advanced data analytics, machine learning algorithms, and cloud infrastructure scalability to optimize well placement and maximize recovery rates. This digital transformation has drastically reduced extraction costs per barrel, driving up operating margins across both Permian Basin shale plays and deepwater offshore fields in the Gulf of Mexico and the North Sea.
Concurrently, the downstream sector has acted as an unexpected profit buffer. Global refining capacity remains constrained due to historic plant closures during the pandemic and ongoing sanctions on key refined product exporters. Consequently, cracking margins—the spread between crude oil feedstock and refined fuels like diesel and jet fuel—have remained elevated, translating into multi-billion-dollar downstream earnings that offset temporary dips in upstream commodity benchmarks.
Financial Performance Metrics: A Comparative Analysis
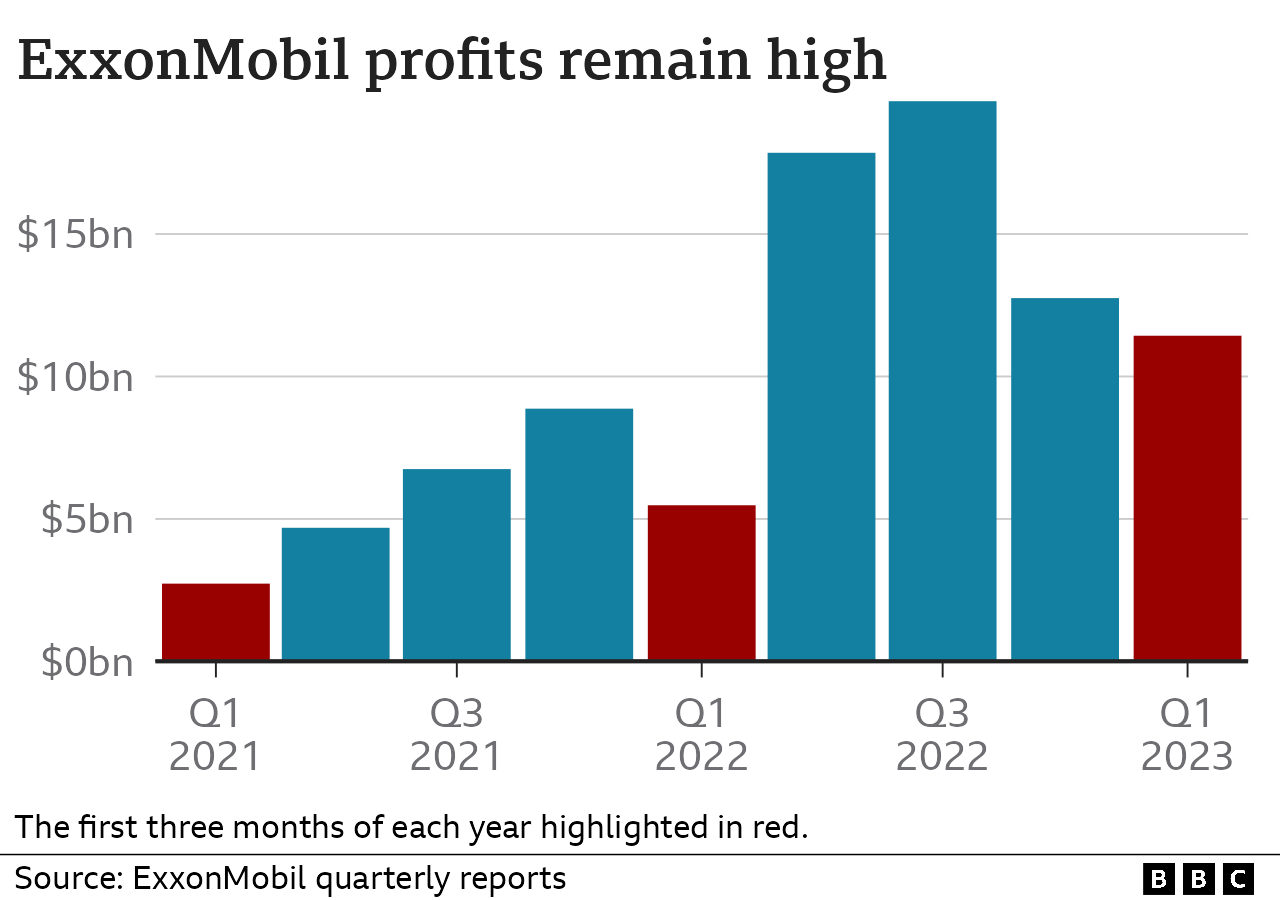
A granular examination of the most recent quarterly filings highlights the sheer scale of the capital influx. Below is a comparative breakdown of key financial indicators across four leading global energy corporations:
| Corporation | Quarterly Net Income ($B) | Operating Cash Flow ($B) | Share Buybacks & Dividends ($B) | Primary Value Driver |
|---|---|---|---|---|
| ExxonMobil | $8.22 | $14.80 | $9.50 | Permian volume growth & offshore Guyana |
| Shell plc | $7.34 | $12.50 | $6.80 | Integrated LNG trading & refining margins |
| Chevron | $5.50 | $9.70 | $6.00 | DJ Basin assets & international gas |
| TotalEnergies | $5.10 | $8.90 | $4.70 | Global LNG portfolio & European power |
Industry & Market Implications: Winners, Losers, and Systemic Shifts
The concentration of immense wealth within the energy sector sends powerful ripple effects across global financial markets. Institutional asset managers face an acute strategic dilemma: underweighting traditional oil and gas equities protects long-term ESG mandates but severely penalizes quarterly portfolio performance relative to major benchmarks. Consequently, many institutional funds are recalibrating their valuation multiples, acknowledging that fossil fuel enterprises will generate substantial cash flows for decades longer than initial transition models projected.
Conversely, energy-intensive manufacturing sectors, commercial airlines, and chemical producers find themselves bearing the cost burden of elevated commodity prices. These downstream consumers must absorb higher input costs or pass them along to end-consumers, exacerbating inflationary pressures in developed economies. Furthermore, emerging economies reliant on imported crude face widening current account deficits, compounding sovereign debt vulnerabilities.
At the political level, the earnings announcements have reignited fierce debates regarding fiscal policy. Lawmakers in Washington and Brussels are once again floating proposals for expanded windfall taxes, increased carbon pricing, and stricter anti-trust oversight. Energy executives, however, counter that penalizing domestic producers risks undermining national energy security and disincentivizing the very capital investments required to fund long-term carbon capture, hydrogen, and renewable infrastructure projects.
Frequently Asked Questions (People Also Ask)
Why are oil company earnings surging despite global economic slowdowns?
Oil company earnings are rising due to a combination of structural underinvestment in new production, resilient global demand for liquid fuels, and high downstream refining margins. Additionally, major operators have successfully lowered their operational breakeven points through technological efficiency and disciplined capital management, allowing them to turn substantial profits even during periods of fluctuating spot prices.
How are oil corporations utilizing their record-breaking cash reserves?
Rather than deploying capital into high-risk, long-cycle exploratory projects as seen in past decades, modern energy conglomerates are prioritizing shareholder returns. A vast majority of surplus cash flow is funneled into aggressive share buyback programs, consistent dividend increases, corporate debt reduction, and selective investments in lower-carbon technologies such as carbon capture, utilization, and storage (CCUS) and liquefied natural gas (LNG).
What role do geopolitical tensions play in current energy sector profitability?
Geopolitical instability—particularly conflicts in the Middle East and ongoing sanctions affecting major Russian energy exports—creates persistent supply chain friction and market volatility. These factors frequently restrict physical supply or elevate freight and insurance premiums, which directly supports higher commodity price floors and widens profit margins for operators with diversified international assets.
Are these high earnings sustainable over the next decade?
Sustainability depends heavily on the pace of global energy transition policies, macroeconomic demand cycles, and OPEC+ production quotas. While near-term cash generation remains robust, long-term projections indicate that companies must successfully balance ongoing hydrocarbon cash cows with profitable, scalable low-carbon business models to maintain their valuation multiples over a 10-to-20-year horizon.
Future Outlook and Strategic Milestones to Watch
As the industry looks toward the upcoming fiscal quarters, senior leadership teams are walking a strategic tightrope. The primary challenge moving forward is not generating liquidity, but deploying it in a manner that satisfies both short-term equity markets and long-term regulatory frameworks. Key milestones to monitor include upcoming OPEC+ production adjustment announcements, quarterly updates on mega-project completions in Guyana and the Middle East, and legislative updates concerning carbon taxation and permitting reform.
Ultimately, Big Oil’s current financial zenith serves as a powerful reminder of the energy system’s inertia. While the global transition toward decarbonization remains an irreversible secular trend, the velocity of that transition is continually mediated by the economic realities of supply, demand, and physical infrastructure. For investors and policymakers alike, navigating this duality will remain the defining challenge of the decade.