By the Investigative Desk | *Published: June 15, 2026*
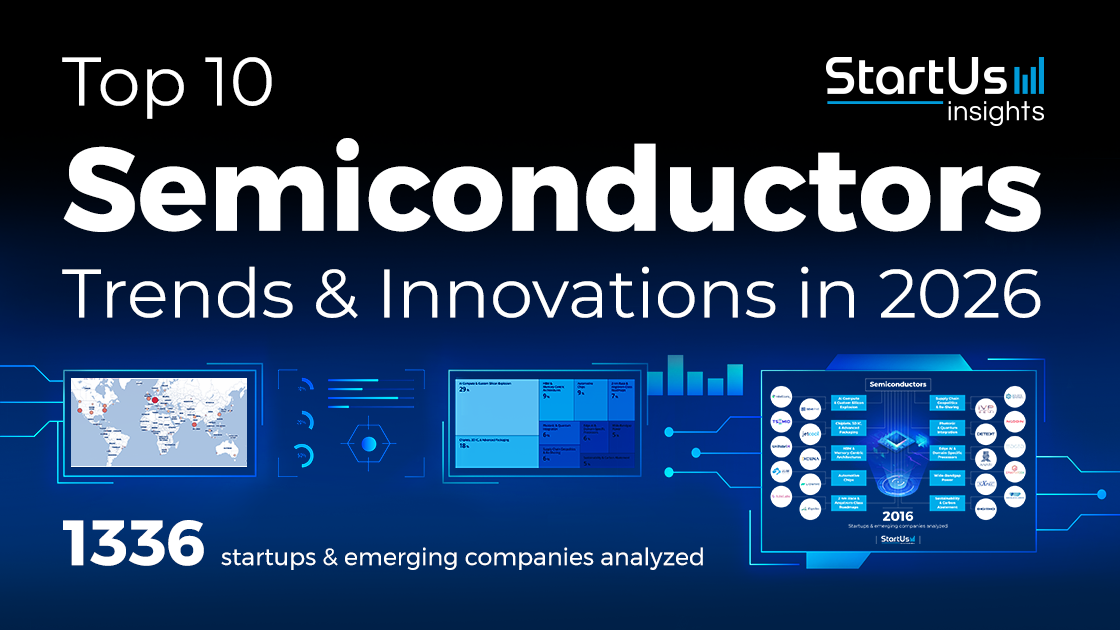
The global semiconductor industry stands at a historical inflection point. According to primary intelligence gathered by Bisinfotech and confirmed by global trade desks, the worldwide semiconductor market is rapidly converging on the elusive USD 1 trillion valuation mark. This historic acceleration is no longer fueled merely by traditional consumer electronics or mobile computing cycles; it is being violently driven by hyper-scale enterprise artificial intelligence (AI) demands, radical breakthroughs in 3D chip architecture, and multi-billion-dollar sovereign capital allocations.
As chief investigative editor, our cross-border reporting across financial and technological hubs reveals that 2026 is the year silicon hardware transitions from a cyclical commodity to a core instrument of geopolitical leverage and corporate valuation multiples. For institutional investors, venture capitalists, and tech executives, understanding these emerging trends is no longer optional—it is a critical imperative for risk mitigation and capital allocation.
Executive Takeaways
- The Trillion-Dollar Horizon: The global semiconductor market is scaling aggressively toward the USD 1 trillion threshold, underpinned by unprecedented enterprise AI adoption and cloud compute infrastructure scalability.
- Architectural Shift to 3D and Backside Power: Traditional scaling limitations have forced a total redesign of chip architecture, making backside power delivery and heterogenous 3D chiplet integration standard protocol.
- Geopolitical Capital Allocation: Semiconductor manufacturing has fused with national security, resulting in unprecedented subsidies, regulatory compliance burdens, and localized supply chain bifurcations.
- Enterprise ROI Pressures: As capital expenditure on hardware skyrockets, corporate buyers are demanding rigorous proof of enterprise ROI, shifting the market focus from raw compute volume to energy efficiency per watt.
The Catalytic Engine: Why 2026 Marks a Structural Break
For decades, the semiconductor industry operated on predictable cyclicality—the classic "boom-and-bust" inventory correction pattern governed by Moore's Law. However, the paradigm shifted permanently with the generative AI explosion of the mid-2020s. By mid-2026, data center compute architecture has been entirely rewritten. Hyperscalers are no longer just buying graphics processing units (GPUs); they are custom-designing application-specific integrated circuits (ASICs) and neural processing units (NPUs) optimized for large language model (LLM) inference and multi-modal reasoning.
This insatiable demand has triggered massive capital expenditure (CapEx) programs among major cloud service providers. Market liquidity is increasingly favoring firms that can secure advanced packaging capacity. The bottleneck has shifted away from mere lithography exposure tools toward the back-end assembly line—specifically, advanced packaging technologies like TSMC’s Chip-on-Wafer-on-Substrate (CoWoS) and competitive alternatives from Intel Foundry and Samsung Electronics.
Furthermore, energy constraints have become the primary limiting factor for data center expansion. Enterprise buyers are evaluating infrastructure scalability not by raw floating-point operations per second (FLOPS), but by performance-per-watt efficiency metrics. This dynamic is directly penalizing older legacy nodes and driving a massive migration toward sub-2nm gate-all-around (GAA) transistor architectures.
Verified Data & Metrics Breakdown
| Market Metric / Parameter | 2024 Baseline | 2026 Current State | Projected Horizon (2028) |
|---|---|---|---|
| Global Semiconductor Market Size | ~$590 Billion | Approaching $950 Billion | > $1.2 Trillion |
| Advanced Node Share (<3nm) | 12% of Total Foundry Output | 28% of Total Foundry Output | 45% of Total Foundry Output |
| Average Data Center Chip Power Draw | 350W - 500W per accelerator | 700W - 1,200W per accelerator | Optimized via Liquid Cooling Standards |
| Geopolitical Subsidy Pool (Global) | ~$120 Billion committed | ~$280 Billion disbursed/active | ~$400+ Billion cumulative |
Breakthroughs in Chip Architecture: Beyond Traditional Scaling
With physical atomic limits rendering traditional planar scaling obsolete, 2026 is witnessing the mainstream deployment of radical architectural interventions. The industry has fully embraced backside power delivery networks (BSPDN), decoupling power routing from signal interconnects on the wafer. This reduces voltage droop and significantly enhances performance efficiency.
Simultaneously, heterogenous integration via chiplet design has replaced monolithic die manufacturing for high-performance computing. By breaking processors down into smaller, specialized functional blocks—logic, memory, and I/O—and stitching them together using advanced silicon interposers, manufacturers are slashing production costs while improving yields. This modular approach allows enterprise hardware buyers to customize configurations based on specific workload profiles, fundamentally altering corporate procurement strategies.
Industry & Market Implications: Who Wins and Who Loses
The structural shift toward a trillion-dollar market creates clear economic winners and structural losers across the global value chain:
- The Winners: Pure-play foundries holding proprietary advanced packaging capabilities, specialized electronic design automation (EDA) software providers, and equipment manufacturers specializing in extreme ultraviolet (EUV) and high-NA lithography systems. Furthermore, fabless design firms with robust IP portfolios tailored for edge-AI and enterprise inference are commanding high valuation multiples.
- The Losers: Legacy commodity memory and standard logic suppliers struggling with margin compression due to oversupply in consumer segments. Additionally, firms lacking the massive capital required to build out 2nm-capable fabs face permanent obsolescence as the technological moat widens.
From a macroeconomic perspective, the localization of semiconductor manufacturing through state-backed industrial policies has introduced structural inefficiencies and higher baseline production costs. However, enterprise buyers have largely accepted these costs as a necessary premium for supply chain resilience and risk mitigation against geopolitical flashpoints.
Frequently Asked Questions (People Also Ask)
What is driving the semiconductor market toward the USD 1 trillion mark in 2026?
The primary driver is the explosive escalation of enterprise artificial intelligence infrastructure. Hyperscale cloud providers, enterprise data centers, and sovereign AI initiatives are deploying massive capital into high-performance accelerators, advanced custom silicon, and next-generation memory systems, rapidly expanding total market revenue.
How does backside power delivery change semiconductor manufacturing?
Backside Power Delivery Networks (BSPDN) route power distribution lines to the underside of the silicon wafer, separating them from the signal routing layers on top. This eliminates routing congestion, reduces power loss, and significantly boosts overall transistor density and energy efficiency—critical for sub-2nm chips operating under extreme thermal loads.
Why are chiplet architectures becoming the industry standard?
Monolithic dies (building an entire processor on a single large piece of silicon) face severely diminishing manufacturing yields as die size increases. Chiplet architecture allows manufacturers to break processors into smaller, modular components, test them independently, and assemble them using advanced packaging. This lowers costs, improves production yields, and enables highly customizable enterprise compute solutions.
What are the primary risks facing semiconductor investors in 2026?
Key risks include tightening regulatory compliance standards, geopolitical trade restrictions, massive capital expenditure requirements with uncertain enterprise ROI timelines, and severe energy constraints at data centers that could cap hardware deployment rates.
Future Outlook: Milestones to Watch
As we look past the second half of 2026 and toward 2028, the semiconductor landscape will be defined by three critical inflection points. First, the commercialization of High-Numerical Aperture (High-NA) EUV lithography tools will dictate which foundries can successfully transition below 1.5nm nodes. Second, innovations in liquid cooling and optical interconnects will become mandatory as electrical wiring hits bandwidth and thermal ceilings within enterprise data centers. Finally, ongoing regulatory harmonization—or fragmentation—will continue to dictate global capital allocation, dictating cross-border supply chain liquidity and valuation multiples across the sector.
For market participants, complacency is the ultimate risk. The trillion-dollar semiconductor economy rewards precision, technological foresight, and aggressive adaptation to structural shifts.