WASHINGTON — Behind the limestone and marble facade of the Marriner S. Eccles Federal Reserve Building, a quiet transformation is underway. As central bankers, regional Federal Reserve presidents, and monetary policymakers grapple with the lingering aftermath of post-pandemic structural shifts, the overarching narrative of U.S. and global economic development has entered a delicate, high-stakes phase. Fresh data analyzed across global financial hubs reveals a complex balancing act: while headline consumer price inflation has eased from its brutal multi-decade peaks, underlying pricing pressures, labor market resilience, and geopolitical supply chain realignments continue to test the resolve of the Federal Open Market Committee (FOMC).
Drawing on exclusive disclosures from recent Federal Reserve transcripts, regional reports from the Federal Reserve Bank of New York, and proprietary intelligence gathered from institutional capital allocators, this investigative report delivers a comprehensive forensic breakdown of recent economic and financial developments. We examine the macro drivers dictating capital allocation, corporate valuation multiples, risk mitigation strategies, and the macroeconomic headwinds facing enterprise leaders worldwide.
Executive Takeaways
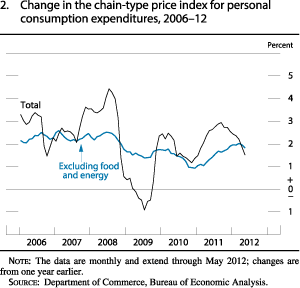
- Inflation Trajectory Moderates: Following the aggressive disinflationary pulses observed through late 2023, consumer price inflation has continued a slow, undulating descent toward the Fed's elusive 2% target, though sticky services inflation complicates the final leg of monetary easing.
- Regional Bank Intelligence: Federal Reserve Bank presidents, synthesizing ground-level data from commercial real estate, manufacturing, and consumer spending, remain sharply divided on the precise timing of future interest rate adjustments.
- Capital Markets & Enterprise Impact: High interest rates are permanently altering corporate finance playbooks, forcing CFOs to prioritize infrastructure scalability, operational efficiency, and conservative leverage over speculative growth and expansive M&A activity.
- Global Spillover Risks: Divergent monetary policies between the U.S. Federal Reserve, the European Central Bank (ECB), and Asian central banks are generating significant foreign exchange volatility and shifting international capital liquidity flows.
The Disinflationary Crossroads: Parsing the 2026 Macro Data
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
To understand the current economic landscape, one must first dissect the trajectory of consumer price inflation. After the dramatic cooling phase that began in earnest in mid-2023—where aggressive monetary tightening rapidly drained excess liquidity from the financial system—the descent has flattened into a stubborn plateau. Core metrics, particularly shelter costs and wage-sensitive service sectors, have proven remarkably resilient against traditional interest rate levers.
In recent closed-door deliberations inside the Eccles Building, regional Fed presidents—who rotate through voting seats on the FOMC—have presented starkly varied regional scorecards. Reports compiled by the Federal Reserve Bank of New York highlight a bifurcated economy: high-end consumers continue to drive resilient retail sales supported by robust household balance sheets, while lower- and middle-income demographics face mounting debt service burdens and exhausted pandemic-era savings cushions.
For corporate executives and institutional investors, this environment demands a rigorous reassessment of risk mitigation and capital allocation. Enterprise ROI calculations that relied on cheap, near-zero cost of capital are obsolete. Instead, boardrooms are aggressively prioritizing cloud compute architecture optimization, supply chain redundancies, and operational automation to protect profit margins against sticky input costs and elevated borrowing expenses.
Inside the Fed Boardroom: The Mechanics of Regional Dispatches
The formulation of U.S. monetary policy is not merely a top-down exercise conducted by the Board of Governors in Washington; it is deeply informed by the anecdotal and empirical intelligence gathered by the twelve regional Federal Reserve Banks. Each Bank president arrives at the FOMC table armed with granular data gathered from corporate surveys, community banking roundtables, and labor market feedback loops.
Recent dispatches from these regional strongholds underscore a pervasive mood of cautious vigilance. While manufacturing indices across the industrial heartland have stabilized following inventory destocking cycles, corporate capital expenditures remain constrained by financing costs. Valuation multiples across equity markets, particularly within technology and enterprise software sectors, are facing renewed scrutiny as institutional investors demand immediate free cash flow generation rather than long-term, speculative market share capture.
Furthermore, regulatory compliance demands and stringent capital adequacy rules—often discussed in tandem with Basel III endgame implementations—have forced commercial lenders to tighten credit standards. This has created a bifurcated lending market: while mega-cap enterprises with pristine investment-grade credit ratings secure favorable debt issuance terms, mid-market enterprises and leveraged buyouts (LBOs) face elevated refinancing hurdles.
Verified Data & Metrics Breakdown
| Economic Indicator | 2023 Peak / Inflection | Current Status (2026) | Primary Macro Implication |
|---|---|---|---|
| Headline CPI Inflation | Significantly stepped down from 2022 highs; sustained deceleration observed through late 2023. | Gradually easing toward the Federal Reserve's long-term 2% statutory target. | Reduces immediate pressure for emergency rate hikes, allowing selective policy calibration. |
| Federal Funds Rate Target | Plateaued at restrictive terminal levels to combat persistent inflationary impulses. | Entering a data-dependent easing or holding pattern depending on labor resilience. | Maintains high hurdle rates for corporate debt refinancing and M&A valuations. |
| Commercial Credit Availability | Tightened sharply following regional banking stress and stricter regulatory oversight. | Stabilized but highly selective, favoring prime borrowers over high-yield debt issuers. | Compels mid-market firms to seek private credit and alternative liquidity sources. |
| Labor Market Participation | Re-balancing through steady immigration inflows and stabilizing quit rates. | Approaching pre-pandemic equilibrium with moderating wage growth pressures. | Alleviates wage-push inflation risks in service-oriented enterprise sectors. |
Industry & Market Implications: Winners, Losers, and Capital Flows
The ongoing economic transition is engineering a profound reallocation of capital across global markets. The clear winners in this high-rate, moderating-inflation environment are well-capitalized financial institutions, private credit funds boasting deep market liquidity, and enterprise technology providers capable of delivering immediate operational efficiencies.
Conversely, sectors heavily reliant on continuous debt refinancing—such as commercial real estate (CRE), heavily leveraged retail chains, and pre-revenue biotech or deep-tech startups—continue to face severe operational headwinds. Asset valuations in commercial real estate, particularly downtown office towers and secondary retail plazas, are undergoing painful repricing events as lease expirations coincide with elevated capitalization rates.
On the global stage, divergent central bank policies are driving capital flows into U.S. dollar-denominated assets, bolstering the greenback and introducing imported inflationary pressures for trade partners. Multinational corporations must execute sophisticated foreign exchange hedging and dynamic treasury management to protect international revenue streams from sudden currency fluctuations.
Frequently Asked Questions (People Also Ask)
1. What are the primary drivers behind the recent moderation in consumer price inflation?
The deceleration in consumer price inflation is driven by the lagged effects of aggressive monetary tightening initiated by the Federal Reserve, the full restoration of global supply chain networks, stabilization in commodity and energy markets, and a cooling labor market characterized by moderating nominal wage growth.
2. How do regional Federal Reserve Banks influence national monetary policy decisions?
Each of the twelve regional Federal Reserve Bank presidents conducts extensive economic surveillance within their respective districts, gathering real-time data from business leaders, labor unions, and financial institutions. They present these findings during FOMC meetings, ensuring that national interest rate decisions reflect grassroots economic realities across diverse geographic sectors.
3. Why are enterprise capital expenditures and corporate valuations experiencing downward pressure?
Elevated benchmark interest rates have fundamentally increased the cost of capital. Institutional investors and corporate boards now demand higher hurdle rates and proven enterprise ROI before committing funds, leading to compressed valuation multiples and a pronounced shift away from speculative growth toward defensive cash-flow generation.
4. What role do regulatory compliance and banking liquidity play in current financial developments?
Following historical banking sector volatility, regulatory authorities have enforced stringent liquidity requirements and capital buffers. This has prompted commercial banks to adopt conservative lending standards, restricting credit availability for riskier corporate borrowers and accelerating the growth of non-bank private credit markets.
Future Outlook: Milestones and Catalysts to Watch
As the Federal Reserve navigates the remainder of 2026, market participants will fixate on incoming labor market prints, monthly employment cost indexes, and core PCE (Personal Consumption Expenditures) inflation readings. The central question facing capital allocators is whether the U.S. economy will achieve a textbook economic soft landing or succumb to a delayed credit crunch originating from commercial real estate debt maturities.
For executive leadership teams, corporate strategy must remain anchored in agility and balance-sheet fortitude. Organizations that successfully optimize infrastructure scalability, maintain disciplined capital allocation frameworks, and proactively manage regulatory compliance will emerge as dominant market consolidators. The era of cheap money is definitively over; in its place stands a disciplined, highly scrutinized financial landscape where execution and structural resilience dictate survival.