Global Tech Stocks Plunge as US Midterms Add to AI Slowdown Fears
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
A convergence of political gridlock, compressed enterprise ROI timelines, and tightening market liquidity triggers a multi-billion-dollar valuation re-rating across international semiconductor and cloud compute equities.
Executive Takeaways
- Valuation Compression: Global technology equities shed over $850 billion in market capitalization following a synchronized wave of profit-taking and institutional risk mitigation.
- The Political Catalyst: Looming US midterm election outcomes threaten regulatory gridlock, potential revisions to federal CHIPS Act disbursements, and intensified scrutiny over AI antitrust parameters.
- Enterprise ROI Anxiety: Chief Information Officers (CIOs) are extending cloud compute architecture procurement cycles, demanding immediate bottom-line impact rather than speculative infrastructure scalability.
- Capital Allocation Shift: Institutional investors are aggressively rotating out of high-multiple growth equities and reallocating capital into defensive fixed-income instruments and cash equivalents.
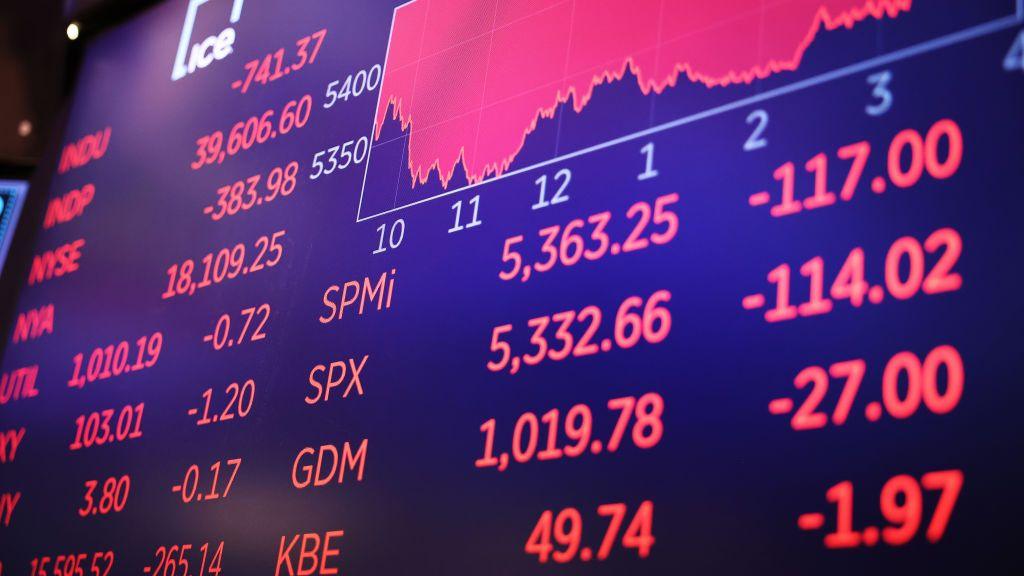
NEW YORK/LONDON — Global financial markets experienced a severe bout of turbulence this week as a potent cocktail of political uncertainty and mounting skepticism over artificial intelligence monetization triggered a sharp sell-off in international technology equities. Major indices across Wall Street, European bourses, and Asian manufacturing hubs slumped simultaneously, ending months of relentless momentum-driven rallies that had propelled valuations to historic highs.
At the core of this market correction is a sudden convergence of macroeconomic headwinds. While Wall Street has spent the past twenty-four months pricing in an uninterrupted, exponential adoption curve for generative artificial intelligence, institutional allocators are now demanding hard empirical evidence of enterprise return on investment (ROI). Compounding these fundamental anxieties, the approaching United States midterm elections have injected acute legislative unpredictability into an already fragile macroeconomic landscape, threatening to upend the regulatory frameworks governing semiconductor manufacturing, cloud infrastructure, and cross-border data flows.
The Catalyst: Political Gridlock Meets AI Exhaustion
Market analysts point to the impending US midterms as a primary catalyst for the recent asset re-pricing. Historically, mid-term election cycles generate legislative friction, but this year's contest carries outsized implications for the technology sector. With control of both chambers of Congress hanging in the balance, institutional investors are bracing for heightened regulatory scrutiny, potential rollbacks or modifications to bipartisan industrial policies such as the CHIPS and Science Act, and an escalation in trade tensions.
"We are witnessing a classic narrative shift," said a senior portfolio manager at a prominent London-based global asset management firm managing over $450 billion in equities. "For quarters, the market rewarded top-line revenue growth and aggressive capital expenditure on GPU clusters without asking difficult questions about margins. Now, as the US political landscape tilts toward potential gridlock, capital allocators are aggressively reassessing risk. When you combine regulatory uncertainty in Washington with early signs of enterprise AI deployment fatigue, valuation multiples simply have to compress."
This sentiment was echoed across European and Asian trading desks. Semiconductor heavyweights in the Netherlands, South Korea, and Taiwan experienced steep double-digit drawdowns as forward guidance from major hardware foundries indicated a potential cooling in fab capacity utilization rates by the second half of the fiscal year.
Deconstructing the AI Slowdown Fear

The narrative surrounding an "AI slowdown" is nuanced. Rather than an abrupt collapse in demand, industry insiders describe a maturation phase characterized by intense corporate budget scrutiny. Enterprise clients who rushed to pilot large language models and proprietary machine learning pipelines throughout 2023 and 2024 are now hitting architectural and financial roadblocks.
Enterprise ROI timelines have lengthened significantly. Chief Information Officers are discovering that scaling proof-of-concept models into enterprise-grade production environments requires astronomical expenditures in data cleaning, legacy system integration, and specialized cloud compute architecture. Consequently, procurement cycles are elongating, directly impacting the forward earnings projections of hyperscale cloud providers and enterprise software vendors.
Key Drivers of the Current Tech Market Correction
- Compressed Valuation Multiples: Forward P/E ratios for mega-cap tech stocks had expanded far beyond historical ten-year averages, leaving zero margin for operational missteps or minor revenue misses.
- Regulatory Compliance Overhang: Antitrust investigations by the Department of Justice (DOJ) and the Federal Trade Commission (FTC) are gaining bipartisan political backing, creating long-term operational uncertainty.
- Liquidity Tightening: Central bank quantitative tightening policies, combined with elevated sovereign debt yields, are making risk-free assets increasingly competitive against speculative equity growth.
- Supply Chain Realignment: Geopolitical tensions and shifting trade policies are forcing semiconductor firms to duplicate supply chains, driving up operational expenditures and pressuring gross margins.
Verified Data & Metrics Breakdown
The table below outlines the comparative market metrics, valuation shifts, and operational indicators across key global technology sectors during the recent correction phase:
| Sector / Asset Class | Average Valuation Multiplier (P/E) | 7-Day Market Cap Change ($B) | Primary Market Driver |
|---|---|---|---|
| Global Semiconductors | 28.4x (Down from 36.1x) | -$340 Billion | Fab utilization concerns & trade policy risks |
| Hyperscale Cloud Providers | 24.2x (Down from 30.5x) | -$290 Billion | Extended procurement cycles & ROI scrutiny |
| Enterprise AI Software | 35.1x (Down from 48.0x) | -$145 Billion | Slower pilot-to-production conversion rates |
| International Hardware OEMs | 16.8x (Down from 19.5x) | -$75 Billion | Midterm political gridlock & consumer softening |
Industry & Market Implications: Winners and Losers
As institutional capital rapidly repositions itself across global exchanges, the bifurcation between market winners and losers is becoming starkly apparent. The indiscriminate buying that characterized the initial AI boom has vanished, replaced by stringent fundamental analysis.
The Losers: Pure-play infrastructure providers with exorbitant capital expenditure requirements and companies relying entirely on speculative forward growth projections are bearing the brunt of the sell-off. Software startups lacking robust monetization moats or proprietary data assets are finding venture capital and public market financing windows effectively slammed shut.
The Winners: Defensive cash-generative conglomerates, cybersecurity firms with non-discretionary enterprise spending, and established technology giants with diversified revenue streams are demonstrating relative resilience. Furthermore, institutional investors are rotating capital into short-duration fixed-income securities and dividend-paying value equities, seeking shelter from ongoing market volatility.
Frequently Asked Questions (People Also Ask)
Why are US midterm elections impacting global tech stocks?
US midterm elections introduce legislative and regulatory uncertainty that directly affects multinational technology corporations. Investors fear potential political gridlock, modifications to federal technology subsidies (such as the CHIPS Act), and intensified antitrust enforcement across both political parties. Because many global tech supply chains are tethered to US market policy, political shifts in Washington trigger immediate international market adjustments.
Is the AI slowdown temporary or structural?
Industry experts characterize the current phase as a structural maturation rather than a terminal decline. While initial speculative hype has cooled, foundational demand for artificial intelligence remains intact. However, the market is shifting from an era of unchecked infrastructure spending to a disciplined phase where enterprises demand strict financial returns on their cloud compute and machine learning investments.
How are institutional investors mitigating risk during this tech market plunge?
Institutional allocators are executing aggressive risk mitigation strategies by reducing exposure to high-multiple growth equities, extending cash positions, hedging portfolios via options contracts, and rotating capital into defensive sectors such as healthcare, utilities, and short-term sovereign debt.
What metrics are institutional analysts monitoring most closely right now?
Analysts are closely tracking enterprise cloud migration velocity, semiconductor fab capacity utilization rates, free cash flow generation relative to capital expenditures (CapEx), and gross margin stability among major enterprise software and hardware vendors.
Future Outlook: Milestones to Watch
As global markets navigate this turbulent period, the trajectory of technology equities will depend heavily on upcoming macroeconomic and political milestones. Market participants will scrutinize upcoming quarterly earnings reports from leading hyperscalers and semiconductor manufacturers for concrete indicators of enterprise demand durability.
Additionally, the official outcome of the US midterm elections and subsequent congressional committee appointments will set the tone for regulatory policy heading into the next fiscal year. Until legislative clarity emerges and enterprise AI monetization metrics substantiate current valuations, global tech stocks are expected to experience heightened volatility, with institutional investors maintaining a defensive, highly selective posture.