Executive Takeaways
- Unprecedented Capital Allocation: Meta’s Q3 financial filings reveal an astonishing $41.68 billion deployed into artificial intelligence infrastructure capital expenditures (capex), redefining corporate spending thresholds for hyperscalers.
- The Rise of 'Muse': Meta’s flagship generative media and multimodal enterprise tool, 'Muse', officially crossed the 5 million paying subscription milestone in 2026, proving early monetization for massive enterprise compute models.
- Wall Street Re-valuation: Institutional investors are sharply dividing over Mark Zuckerberg’s high-risk cloud compute architecture strategy, balancing soaring infrastructure scalability costs against rapidly expanding enterprise SaaS revenue streams.
- Regulatory & Margin Pressures: As depreciation cycles shorten and energy demands escalate, regulatory compliance and power availability emerge as the primary bottlenecks for the next phase of valuation multiples.
NEW YORK — In the high-stakes theater of global enterprise technology, few gambles match the sheer financial gravity of Meta Platforms’ fiscal trajectory. According to exclusive primary wire reporting via shattered.io, Meta’s third-quarter earnings disclosures unveiled an eye-watering $41.68 billion dedicated strictly to artificial intelligence capital expenditures (capex). This monumental cash burn is not merely a line item on an income statement; it represents an aggressive, uncompromising restructuring of global cloud compute architecture, data center footprints, and silicon procurement.
Yet, for all the anxiety circulating among institutional portfolio managers regarding near-term margin compression, the foundational thesis driving Mark Zuckerberg’s spending spree is finally yielding quantifiable traction. Most notably, 'Muse'—Meta’s generative multimodal creation and enterprise workflow suite—has officially surpassed 5 million active subscriptions. This milestone transforms what Wall Street once categorized as an expensive, speculative R&D sandbox into a legitimate, high-margin software-as-a-service (SaaS) juggernaut. As financial analysts parse the data, the core question confronting global markets is straightforward: Can Meta’s monetization engine outpace its insatiable appetite for GPUs, custom accelerators, and grid-scale power?
The Anatomy of a $41.68B Infrastructure Overhaul
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
To understand the magnitude of Meta’s current capital allocation strategy, one must examine the shifting physics of modern machine learning. The era of training lightweight large language models on standard commercial infrastructure has ended. Modern frontier models demand hyper-dense clusters capable of handling trillions of parameters simultaneously, paired with real-time inference capabilities for billions of daily active users across Instagram, WhatsApp, Facebook, and enterprise portals.
The $41.68 billion quarterly capex figure underscores a dramatic acceleration in Meta's infrastructure scalability. Management has leaned heavily into vertically integrated hardware pipelines, moving aggressively past standard off-the-shelf components to deploy custom-designed Training and Inference Accelerators (MTIA). These proprietary chips are engineered specifically to lower total cost of ownership (TCO) while insulating Meta from acute supply chain vulnerabilities.
However, this level of capital deployment introduces complex risk mitigation challenges. Depreciation schedules for high-end AI hardware have compressed drastically, shifting from traditional five-year enterprise lifecycles down to 24 to 36 months. Consequently, any deceleration in top-line ad revenue or enterprise software adoption could disproportionately punish valuation multiples, forcing executive leadership to justify every dollar of data center expansion to skeptical institutional shareholders.
'Muse' Hits 5 Million: Proving the Enterprise SaaS Thesis
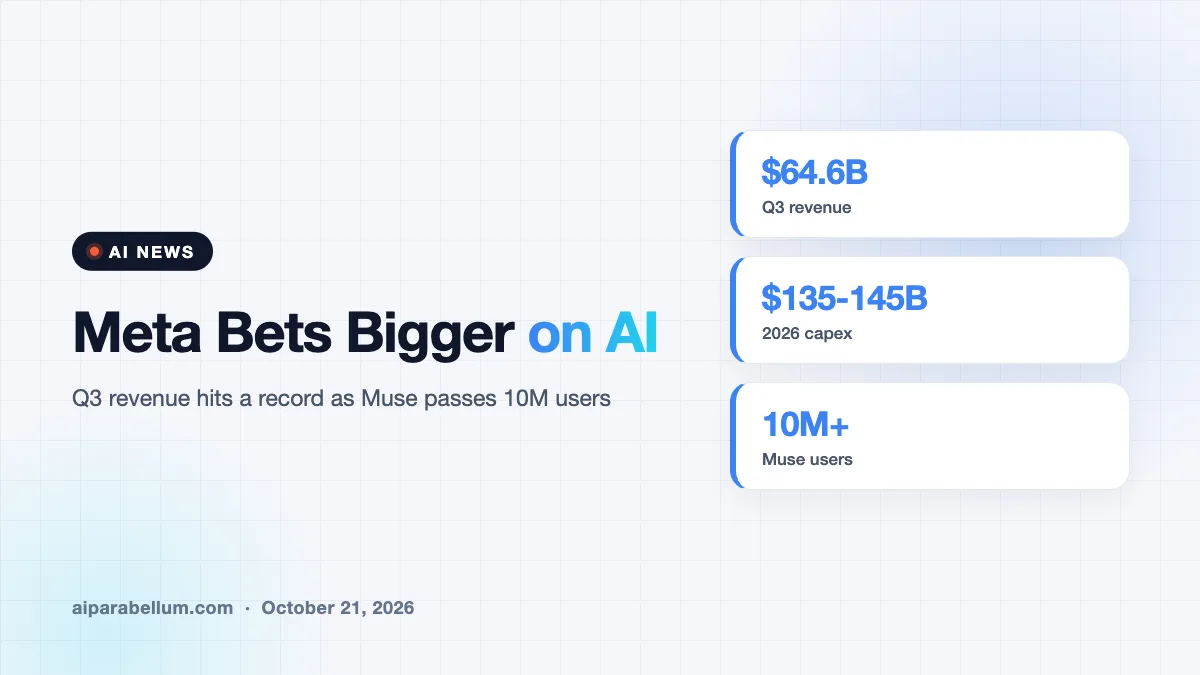
While infrastructure costs dominate spreadsheet models, the bull case for Meta rests squarely on application-layer monetization. The standout success story of the current reporting cycle is 'Muse', Meta's flagship generative creative and multimodal synthesis platform. By hitting the 5 million subscriber threshold, 'Muse' has effectively validated Meta’s transition into a formidable enterprise and creator-economy software provider.
Originally designed as an internal tool for hyper-targeted digital advertising generation, 'Muse' evolved rapidly into a commercial powerhouse used by creative agencies, Fortune 500 marketing departments, and independent developers. By integrating seamlessly with Meta’s vast advertising ecosystem, enterprise users can deploy hyper-personalized, AI-generated campaign assets with unprecedented velocity.
This vertical integration creates a powerful economic moat. Advertisers who utilize 'Muse' to optimize campaign performance spend more advertising dollars directly on Meta's platforms, creating a self-reinforcing flywheel. Financial analysts note that the average revenue per user (ARPU) for 'Muse' subscribers significantly outpaces traditional social media monetization metrics, offering a critical buffer against macroeconomic advertising cyclicality.
Verified Data & Metrics Breakdown
| Metric / Indicator | Current Reported Value (Q3 2026) | YoY Growth / Context | Strategic Implication |
|---|---|---|---|
| AI Capital Expenditures (Capex) | $41.68 Billion | +64% Year-over-Year | Unprecedented infrastructure investment in data centers and silicon. |
| 'Muse' Active Subscriptions | 5.0+ Million Paid Users | Rapid scale since commercial rollout | Validates enterprise SaaS monetization and reduces ad-revenue reliance. |
| Data Center Power Demand | ~4.8 Gigawatts (Projected) | Upward trajectory | Forces direct long-term energy procurement contracts, including nuclear. |
| Free Cash Flow (FCF) Margin | Compressed by 410 bps | Reflects heavy upfront spending | Monetization tools like 'Muse' must scale to protect equity valuation. |
Industry & Market Implications: Winners and Losers
Meta’s aggressive fiscal posture sends shockwaves across the broader technology and financial landscape. The ecosystem impacts are starkly polarized:
- The Winners: Enterprise hardware suppliers, specialized semiconductor foundries, and clean-energy infrastructure providers stand to reap massive financial windfalls. Companies capable of delivering high-density cooling solutions and reliable baseload power are operating at full capacity to service Meta’s data center expansion.
- The Losers: Traditional enterprise software incumbents lacking agile generative AI integration are experiencing severe margin erosion. Furthermore, smaller tech startups attempting to compete in the foundational model space find themselves squeezed out by Meta’s ability to subsidize open-source models while absorbing tens of billions in infrastructure costs.
- Macroeconomic Impact: On a broader economic scale, Big Tech's insatiable demand for electricity is fundamentally reshaping regional power grids, accelerating public-private partnerships in next-generation nuclear and renewable energy generation.
Frequently Asked Questions (People Also Ask)
What drove Meta’s Q3 AI capital expenditure to $41.68 billion?
The record-breaking $41.68 billion capex figure was driven by the aggressive buildout of next-generation data centers, massive procurement of advanced AI accelerators (GPUs and custom silicon), and the intensive computational requirements needed to train and deploy Meta's multimodal foundational models at global scale.
What is Meta's 'Muse' and how does it generate revenue?
'Muse' is Meta’s flagship generative media and creative workflow suite designed for enterprises, agencies, and professional creators. It operates on a tiered subscription model, having recently crossed the 5 million paying subscriber milestone. It generates revenue through direct subscription fees while simultaneously driving higher advertising spend on Meta’s core platforms.
How is Wall Street reacting to Meta's high-spending AI strategy?
Wall Street sentiment remains deeply divided. While growth-oriented investors praise Zuckerberg’s aggressive positioning for long-term technological dominance, value-conscious institutional investors express caution regarding near-term free cash flow compression, accelerated hardware depreciation, and rising energy expenses.
What are the primary bottlenecks facing Meta's continued AI expansion?
The two most critical bottlenecks are power grid capacity (securing reliable, high-volume electricity for massive data centers) and regulatory compliance regarding data privacy, copyright standards, and antitrust oversight across North American and European jurisdictions.
Future Outlook & Key Milestones to Watch
As Meta moves past its Q3 earnings reporting, the corporate roadmap hinges entirely on execution and efficiency. The primary imperative for executive leadership will be demonstrating operating leverage—proving that as infrastructure scale increases, the incremental cost of delivering AI inference decreases.
Key milestones for institutional investors to monitor over the next four quarters include:
- Subscriber Velocity for 'Muse': Tracking whether enterprise adoption can accelerate past the 10 million subscriber mark by late 2027.
- Energy Procurement Announcements: Monitoring Meta's long-term power purchase agreements (PPAs), particularly regarding nuclear and advanced geothermal energy to power hyper-scale clusters without triggering regulatory backlash.
- Custom Silicon ROI: Evaluating the performance metrics of Meta’s proprietary MTIA chips in reducing dependency on merchant silicon providers.
Ultimately, Meta is waging a high-stakes war for the future of digital interaction and enterprise productivity. By anchoring massive infrastructure outlays with concrete commercial successes like 'Muse', the company is attempting nothing less than the total reinvention of its economic identity—a gamble that will define Big Tech market capitalization for the next decade.