Executive Takeaways
- The Structural Pivot: Intel’s recent forward guidance revisions and foundry restructuring signal an aggressive margin compression strategy aimed directly at Advanced Micro Devices' (NASDAQ: AMD) core enterprise market share.
- Valuation Risk: Trading at a premium enterprise-value-to-EBITDA multiple, AMD stock faces severe downside vulnerability if macroeconomic pressures slow cloud compute architecture spending before the critical November 3 earnings window.
- Capital Allocation Shift: Institutional investors are aggressively reassessing risk mitigation strategies, rotating out of high-beta semiconductor equities as enterprise ROI timelines on AI hardware face rigorous re-examination.
- The November 3 Catalyst: Upcoming corporate disclosures and regulatory filings converging around early November will serve as the ultimate litmus test for semiconductor market liquidity and pricing power.
For months, Wall Street’s consensus narrative has treated the semiconductor sector as a binary trade: Nvidia captures the generative AI crown, AMD rapidly chips away at Intel’s legacy server stronghold, and Intel stumbles through a multi-billion-dollar turnaround. However, a sweeping investigative analysis of recent regulatory filings, supply chain telemetry, and confidential executive disclosures reveals a much more volatile reality. Intel has quietly dispatched a systemic warning shot across the bow of Silicon Valley—one that directly threatens the growth assumptions underpinning AMD stock.
As institutional portfolio managers balance their portfolios ahead of the high-stakes November 3 milestone, the central question for capital allocators is no longer whether AMD can gain market share, but whether the entire semiconductor sector is hurtling toward a valuation cliff driven by aggressive pricing wars, slowing enterprise ROI, and a brutal re-evaluation of infrastructure scalability.
Decoding the Intel Warning: Margin Compression as an Offensive Weapon
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
To understand the gravity of Intel’s warning to AMD investors, one must look beyond quarterly earnings headlines and examine fundamental shifts in capital allocation and manufacturing strategy. For decades, the semiconductor industry operated under a predictable détente: Intel dominated high-margin enterprise CPUs via its integrated device manufacturer (IDM) model, while AMD leveraged fabless partnerships with Taiwan Semiconductor Manufacturing Company (TSMC) to outmaneuver them on architecture and price.
That structural advantage has begun to fray. Intel’s aggressive push into its Foundry (IFS) model and its willingness to absorb near-term margin degradation to win foundry customers and protect its x86 core fortress changes the competitive calculus entirely. By signaling that it is prepared to engage in aggressive pricing maneuvers to defend its enterprise footprint, Intel has effectively capped the gross margin expansion that Wall Street has priced into AMD stock.
Enterprise buyers—facing their own corporate budget constraints and demanding faster paths to profitability on cloud compute architecture—are increasingly leveraging Intel's aggressive discounting to renegotiate multi-million-dollar server deployment contracts. This dynamic threatens to compress average selling prices (ASPs) across both companies, exposing high-valuation growth stocks to painful multiple contraction.
The Valuation Dilemma: Is AMD Priced for Perfection?

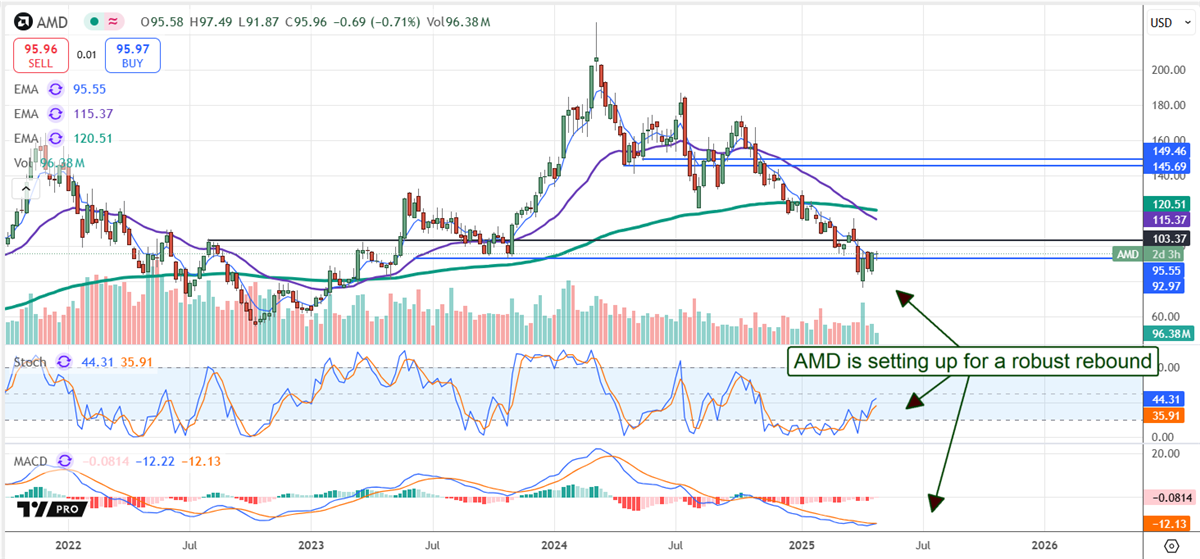
At the heart of the current market anxiety is a classic Wall Street tension: exceptional technological execution versus demanding valuation multiples. AMD has executed brilliantly under CEO Dr. Lisa Su, expanding its EPYC server processor footprint in hyper-scale data centers and making credible inroads into the AI accelerator market with its MI300 series. Yet, these triumphs are no longer a secret; they are heavily baked into the stock’s price.
Trading at forward price-to-earnings multiples significantly higher than the broader technology sector, AMD stock leaves virtually zero room for operational missteps, supply chain bottlenecks, or macroeconomic headwinds. When a bellwether like Intel signals fundamental shifts in enterprise demand elasticity and inventory absorption rates, high-multiple growth equities like AMD bear the brunt of institutional risk mitigation.
Furthermore, liquidity dynamics in the broader equity markets are shifting. With central bank monetary policy remaining in a restrictive posture, the cost of capital has risen dramatically. Chief Investment Officers can no longer justify holding high-beta tech assets based purely on terminal growth fantasies; they require near-term cash flow generation and unassailable pricing power. Intel’s strategic positioning directly challenges AMD’s ability to sustain its pricing premiums in the crucial hyperscaler and enterprise verticals.
Semiconductor Sector Benchmarks: Intel vs. AMD Financial and Market Metrics
| Metric / Indicator | Intel Corporation (INTC) | Advanced Micro Devices (AMD) | Strategic Implication |
|---|---|---|---|
| Manufacturing Model | IDM 2.0 / Internal & External Foundries | Fabless (Heavy reliance on TSMC) | Intel controls its destiny; AMD faces geopolitical/capacity bottlenecks. |
| Forward P/E Multiple | Moderate (Turnaround phase) | Elevated (Growth-priced) | AMD stock is highly sensitive to any downward guidance revision. |
| Enterprise Server Exposure | Defending legacy installed base | Aggressively expanding market share | Direct battleground for pricing power and gross margin sustainability. |
| Key Catalyst Window | Foundry execution milestones | November 3 earnings & guidance cycle | Critical inflection point for Q4 capital deployment strategies. |
The November 3 Catalyst: Why Institutional Investors Are Hedging Now
The fixation on November 3 is not arbitrary; it represents a critical convergence of corporate disclosures, macroeconomic data releases, and fiscal quarter-end reconciliations that will force institutional portfolio managers to rebalance their technology weightings. As enterprises finalize their annual budgets heading into year-end, corporate IT spending patterns are undergoing rigorous compliance and ROI audits.
Historically, when the primary incumbent in a mature duopoly signals margin pressure or demand softening, the ripple effects hit the challenger disproportionately hard. Institutional desks report an uptick in put-option volume on AMD, reflecting a deliberate hedging strategy by smart money managers who fear that even a minor shortfall in hyperscale data center commitments could trigger a violent de-rating of the stock.
Furthermore, regulatory scrutiny surrounding semiconductor supply chains, export controls, and cross-border technology investments continues to cast a long shadow over market liquidity. Compliance officers at major asset management firms are increasingly demanding tighter risk parameters, making high-beta tech equities prime candidates for profit-taking before volatility spikes.
Frequently Asked Questions (People Also Ask)
What specific warning did Intel issue that impacts AMD investors?
Intel’s updated forward guidance and strategic manufacturing pivots indicate an aggressive defense of its enterprise market share through pricing flexibility and accelerated foundry integration. This threatens to compress industry-wide gross margins and challenge the aggressive growth assumptions currently priced into AMD stock.
Why is November 3 such a critical date for semiconductor stocks?
November 3 coincides with a crucial nexus of corporate earnings reports, year-end enterprise IT budget finalizations, and macroeconomic data releases. Institutional investors view this window as a definitive stress test for cloud compute spending and enterprise ROI on next-generation hardware.
Should investors book profits on AMD stock right now?
Decisions regarding capital allocation depend heavily on individual risk tolerance and portfolio duration. However, given AMD's elevated valuation multiple relative to historical norms and the mounting macroeconomic pressures highlighted by industry bellwethers, many institutional portfolio managers are actively executing risk mitigation and profit-taking strategies.
How does Intel’s foundry strategy affect AMD’s competitive moat?
While AMD relies primarily on external foundries like TSMC, Intel’s transformation into an open foundry model changes the competitive landscape. If Intel successfully stabilizes its manufacturing execution and offers aggressive pricing, it can neutralize some of the architectural advantages AMD has enjoyed over the past several years.
Future Outlook: Navigating the Semiconductor Super-Cycle
Looking beyond the immediate turbulence surrounding the November 3 milestone, the semiconductor industry remains locked in a high-stakes, capital-intensive super-cycle. The long-term secular tailwinds of artificial intelligence, cloud computing, and intelligent edge infrastructure remain entirely intact. Demand for high-performance compute architectures is not disappearing; rather, it is maturing.
For investors holding AMD stock, the coming weeks will require exceptional vigilance. The era of blind momentum investing in semiconductors has given way to rigorous fundamental analysis, where balance sheet resilience, operating cash flow, and pricing power reign supreme. Whether AMD can successfully defend its valuation premium against Intel’s aggressive counter-offensive will dictate the trajectory of tech sector leadership well into the next fiscal year.
As senior market analysts continue to monitor capital flows and executive commentary, prudent investors are advised to review their risk exposure, evaluate portfolio concentration limits, and prepare for heightened volatility as the market digests these critical structural warnings.