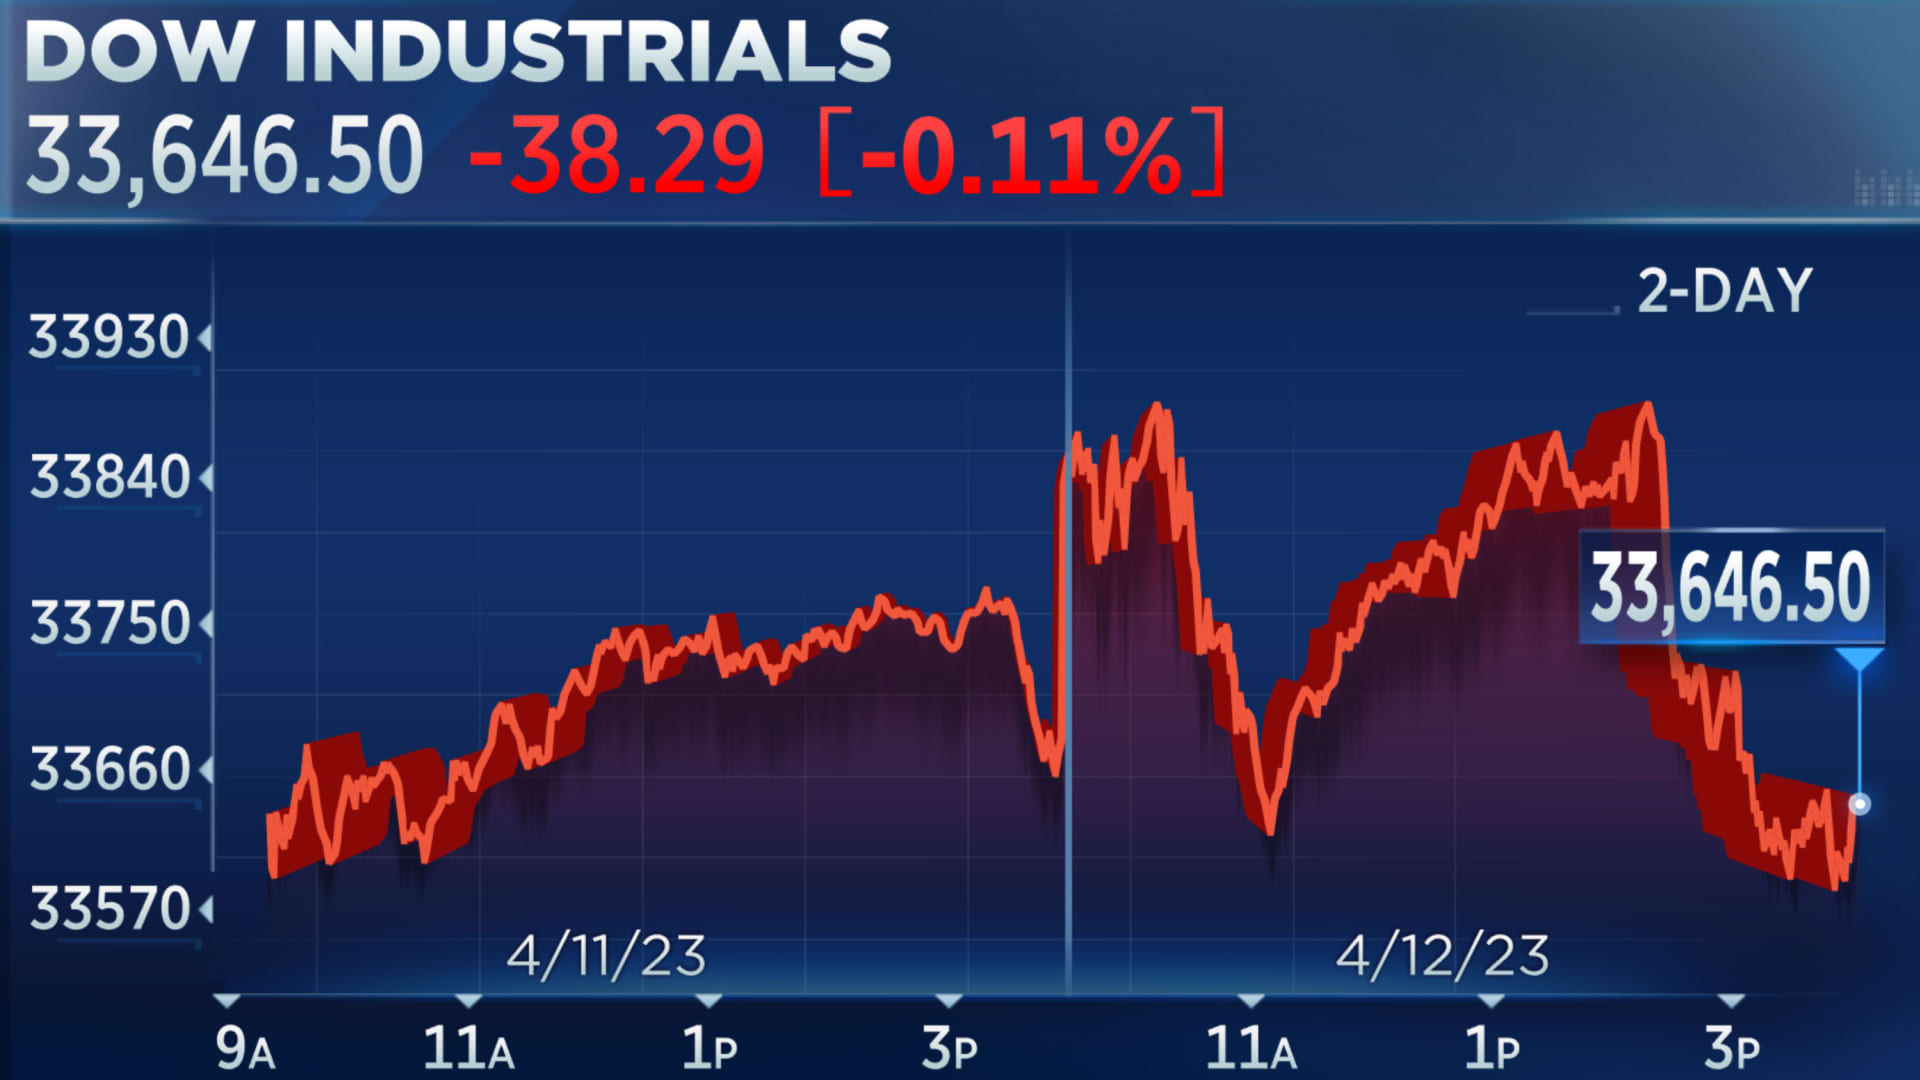
Oil Surges to Five-Month High as Middle East Tensions Ignite Supply Fears; Dow Opens Lower in Broad Market Retreat
NEW YORK — Global financial markets faced a volatile session on Tuesday as a sharp escalation in geopolitical tensions sent crude oil futures surging to a five-month high, immediately dampening risk appetite across major equity indexes. The Dow Jones Industrial Average opened lower, pressured by mounting concerns over corporate margin compression, persistent inflationary pressures, and capital allocation adjustments required to navigate an increasingly unpredictable macroeconomic landscape.
As institutional desks reevaluate portfolio risk mitigation strategies and valuation multiples in light of spiking energy inputs, chief investment officers are scrambling to model the cascading effects of sustained high oil prices on consumer discretionary spending and enterprise operational overhead. This comprehensive investigative report unpacks the underlying drivers of today’s market action, analyzing the nexus between commodity shocks, corporate earnings projections, and central bank monetary policy.
Executive Takeaways
- Crude Benchmark Rally: Brent and WTI crude futures breached five-month highs amid supply chain vulnerability assessments and escalating geopolitical friction in key producing corridors.
- Equity Market Reaction: The Dow Jones Industrial Average and broader benchmarks opened in negative territory, driven by sell-offs in transport, manufacturing, and consumer-facing sectors facing margin erosion.
- Inflationary and Monetary Policy Implications: Sustained energy price escalation complicates the Federal Reserve’s disinflationary trajectory, forcing traders to reprice interest rate cut expectations and evaluate long-term market liquidity.
- Strategic Portfolio Adjustments: Institutional capital is rapidly rotating toward high-margin energy equities and defensive cash equivalents, prioritizing balance sheet resilience and enterprise ROI.
Comprehensive Narrative: The Anatomy of a Dual-Shock Session
The convergence of surging energy markets and retreating equity valuations underscores the delicate equilibrium currently defining global financial architecture. Trading desks across Wall Street and the City of London opened to a barrage of macroeconomic data and geopolitical flashpoints that instantly altered valuation models. At the heart of the morning sell-off is the sudden, aggressive upward re-pricing of crude oil, a foundational input cost that ripples through every tier of the global economy—from logistics and cloud compute architecture power demands to basic manufacturing supply chains.
Energy analysts attribute the five-month high in oil prices to a combination of tightening physical supply inventories, aggressive inventory draws reported by major distribution hubs, and heightened risk premiums associated with Middle Eastern shipping lanes. When energy costs spike abruptly, the transmission mechanism to consumer prices is nearly instantaneous. Transport operators, airlines, and heavy industrial enterprises face immediate margin contraction unless they possess the pricing power to pass these elevated costs downstream to end-users.
Concurrently, the equity market’s reaction reflects a broader reassessment of corporate earnings durability. For months, equity bulls have banked on a "soft landing" scenario characterized by moderating inflation and eventual monetary easing by the Federal Reserve. However, sustained commodity inflation threatens to reignite headline Consumer Price Index (CPI) metrics, throwing a wrench into central bank projections. As a result, fixed-income yields climbed, exerting downward pressure on equity valuation multiples—particularly within technology and growth sectors where future cash flows are discounted at higher prevailing rates.
Market Metrics & Energy Benchmark Breakdown
To contextualize the magnitude of today’s market moves, the following data table outlines the key performance indicators, asset classes, and valuation shifts observed during the opening hours of the trading session:
| Asset / Index | Current Session Opening | Percentage Change | Primary Driver / Catalyst |
|---|---|---|---|
| Dow Jones Industrial Average | Lower (-320 points) | -0.85% | Broad-based industrial and consumer sector retreat due to rising input costs. |
| WTI Crude Oil | Five-Month High ($86.50/bbl) | +2.40% | Geopolitical supply concerns, shrinking inventories, and production quota adherence. |
| Brent Crude | Five-Month High ($90.20/bbl) | +2.15% | Maritime security risks and robust regional demand metrics. |
| US 10-Year Treasury Yield | 4.42% | +6 bps | Re-pricing of Federal Reserve rate cut timelines amid sticky inflation fears. |
Industry & Market Implications: Winners and Losers
Every major market dislocation creates a distinct bifurcation between corporate beneficiaries and those bearing the brunt of structural headwinds. Understanding these dynamics is essential for institutional capital allocation and risk mitigation.
The Beneficiaries: Energy Majors and Defensive Allocations
Integrated oil and gas producers, exploration and production (E&P) firms, and oilfield services providers are experiencing an immediate surge in cash flow generation. As commodity prices test multi-month highs, these entities are well-positioned to accelerate capital return programs via share repurchases and dividend distributions. Furthermore, defensive sectors possessing robust balance sheets, strong pricing power, and predictable cash flows are attracting defensive capital rotation from institutional investors seeking shelter from equity volatility.
The Vulnerable: Transport, Consumer Discretionary, and Leveraged Growth
Conversely, airlines, shipping lines, chemical manufacturers, and consumer discretionary retailers face severe profitability headwinds. High jet fuel and diesel costs cannot always be fully recovered through surcharges without destroying demand elasticity. Additionally, capital-intensive technology and infrastructure firms that rely on debt financing face higher hurdle rates as bond yields push upward, forcing management teams to re-evaluate infrastructure scalability and capital expenditure budgets.
Frequently Asked Questions (People Also Ask)
Why did oil prices hit a five-month high today?
Crude oil benchmarks surged due to a convergence of tightening physical supply fundamentals, lower-than-expected commercial inventory data, and escalating geopolitical tensions in key energy-producing and shipping regions. These factors have forced commodity traders to price in a larger risk premium regarding potential supply disruptions.
How does a spike in oil prices impact the Dow Jones Industrial Average?
The Dow Jones Industrial Average contains numerous multinational industrial, manufacturing, and consumer-facing corporations that rely heavily on affordable energy and logistics. When oil prices spike, operational input costs rise and consumer purchasing power is squeezed by higher fuel and utility bills, leading to lower projected corporate earnings and downward pressure on stock prices.
Will the Federal Reserve change its interest rate policy due to rising energy costs?
Central bankers closely monitor headline inflation metrics, which are heavily influenced by volatile energy and food prices. If sustained high oil prices feed into broader consumer price inflation, it complicates the disinflationary process, potentially prompting the Federal Reserve to delay expected interest rate cuts or maintain a restrictive monetary policy stance for a longer duration.
What strategies should investors adopt during periods of high market volatility and commodity spikes?
Institutional portfolio managers typically focus on rigorous risk mitigation, emphasizing companies with strong balance sheets, low debt-to-equity ratios, and robust pricing power. Diversifying into cash equivalents, high-yielding energy equities, and defensive sectors can help cushion portfolios against sudden equity drawdowns.
Future Outlook: Key Milestones to Watch
As markets navigate this complex macroeconomic backdrop, institutional investors and corporate executives must monitor several critical catalysts in the weeks ahead:
1. Upcoming Consumer Price Index (CPI) and Producer Price Index (PPI) Releases: These inflation prints will reveal whether rising energy costs are successfully filtering through the supply chain into core consumer goods.
2. Geopolitical Developments in the Middle East: Any stabilization or further escalation in maritime transit routes will directly dictate the trajectory of global crude benchmarks.
3. Corporate Q-3 Earnings Guidance: Executive commentary during upcoming earnings conference calls will provide granular insight into how enterprises plan to protect operating margins amidst persistent cost pressures.
4. Central Bank Communication: Speeches from Federal Reserve officials will offer vital clues regarding how policymakers view the trade-off between sticky commodity inflation and economic growth momentum.
Stay tuned to our real-time financial wire for continuous live updates, institutional earnings analysis, and breaking market intelligence as the trading session develops.