Exxon, Chevron, and Shell Deliver Historic Windfalls While Global Consumers Face Persistent Inflationary Pressures
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
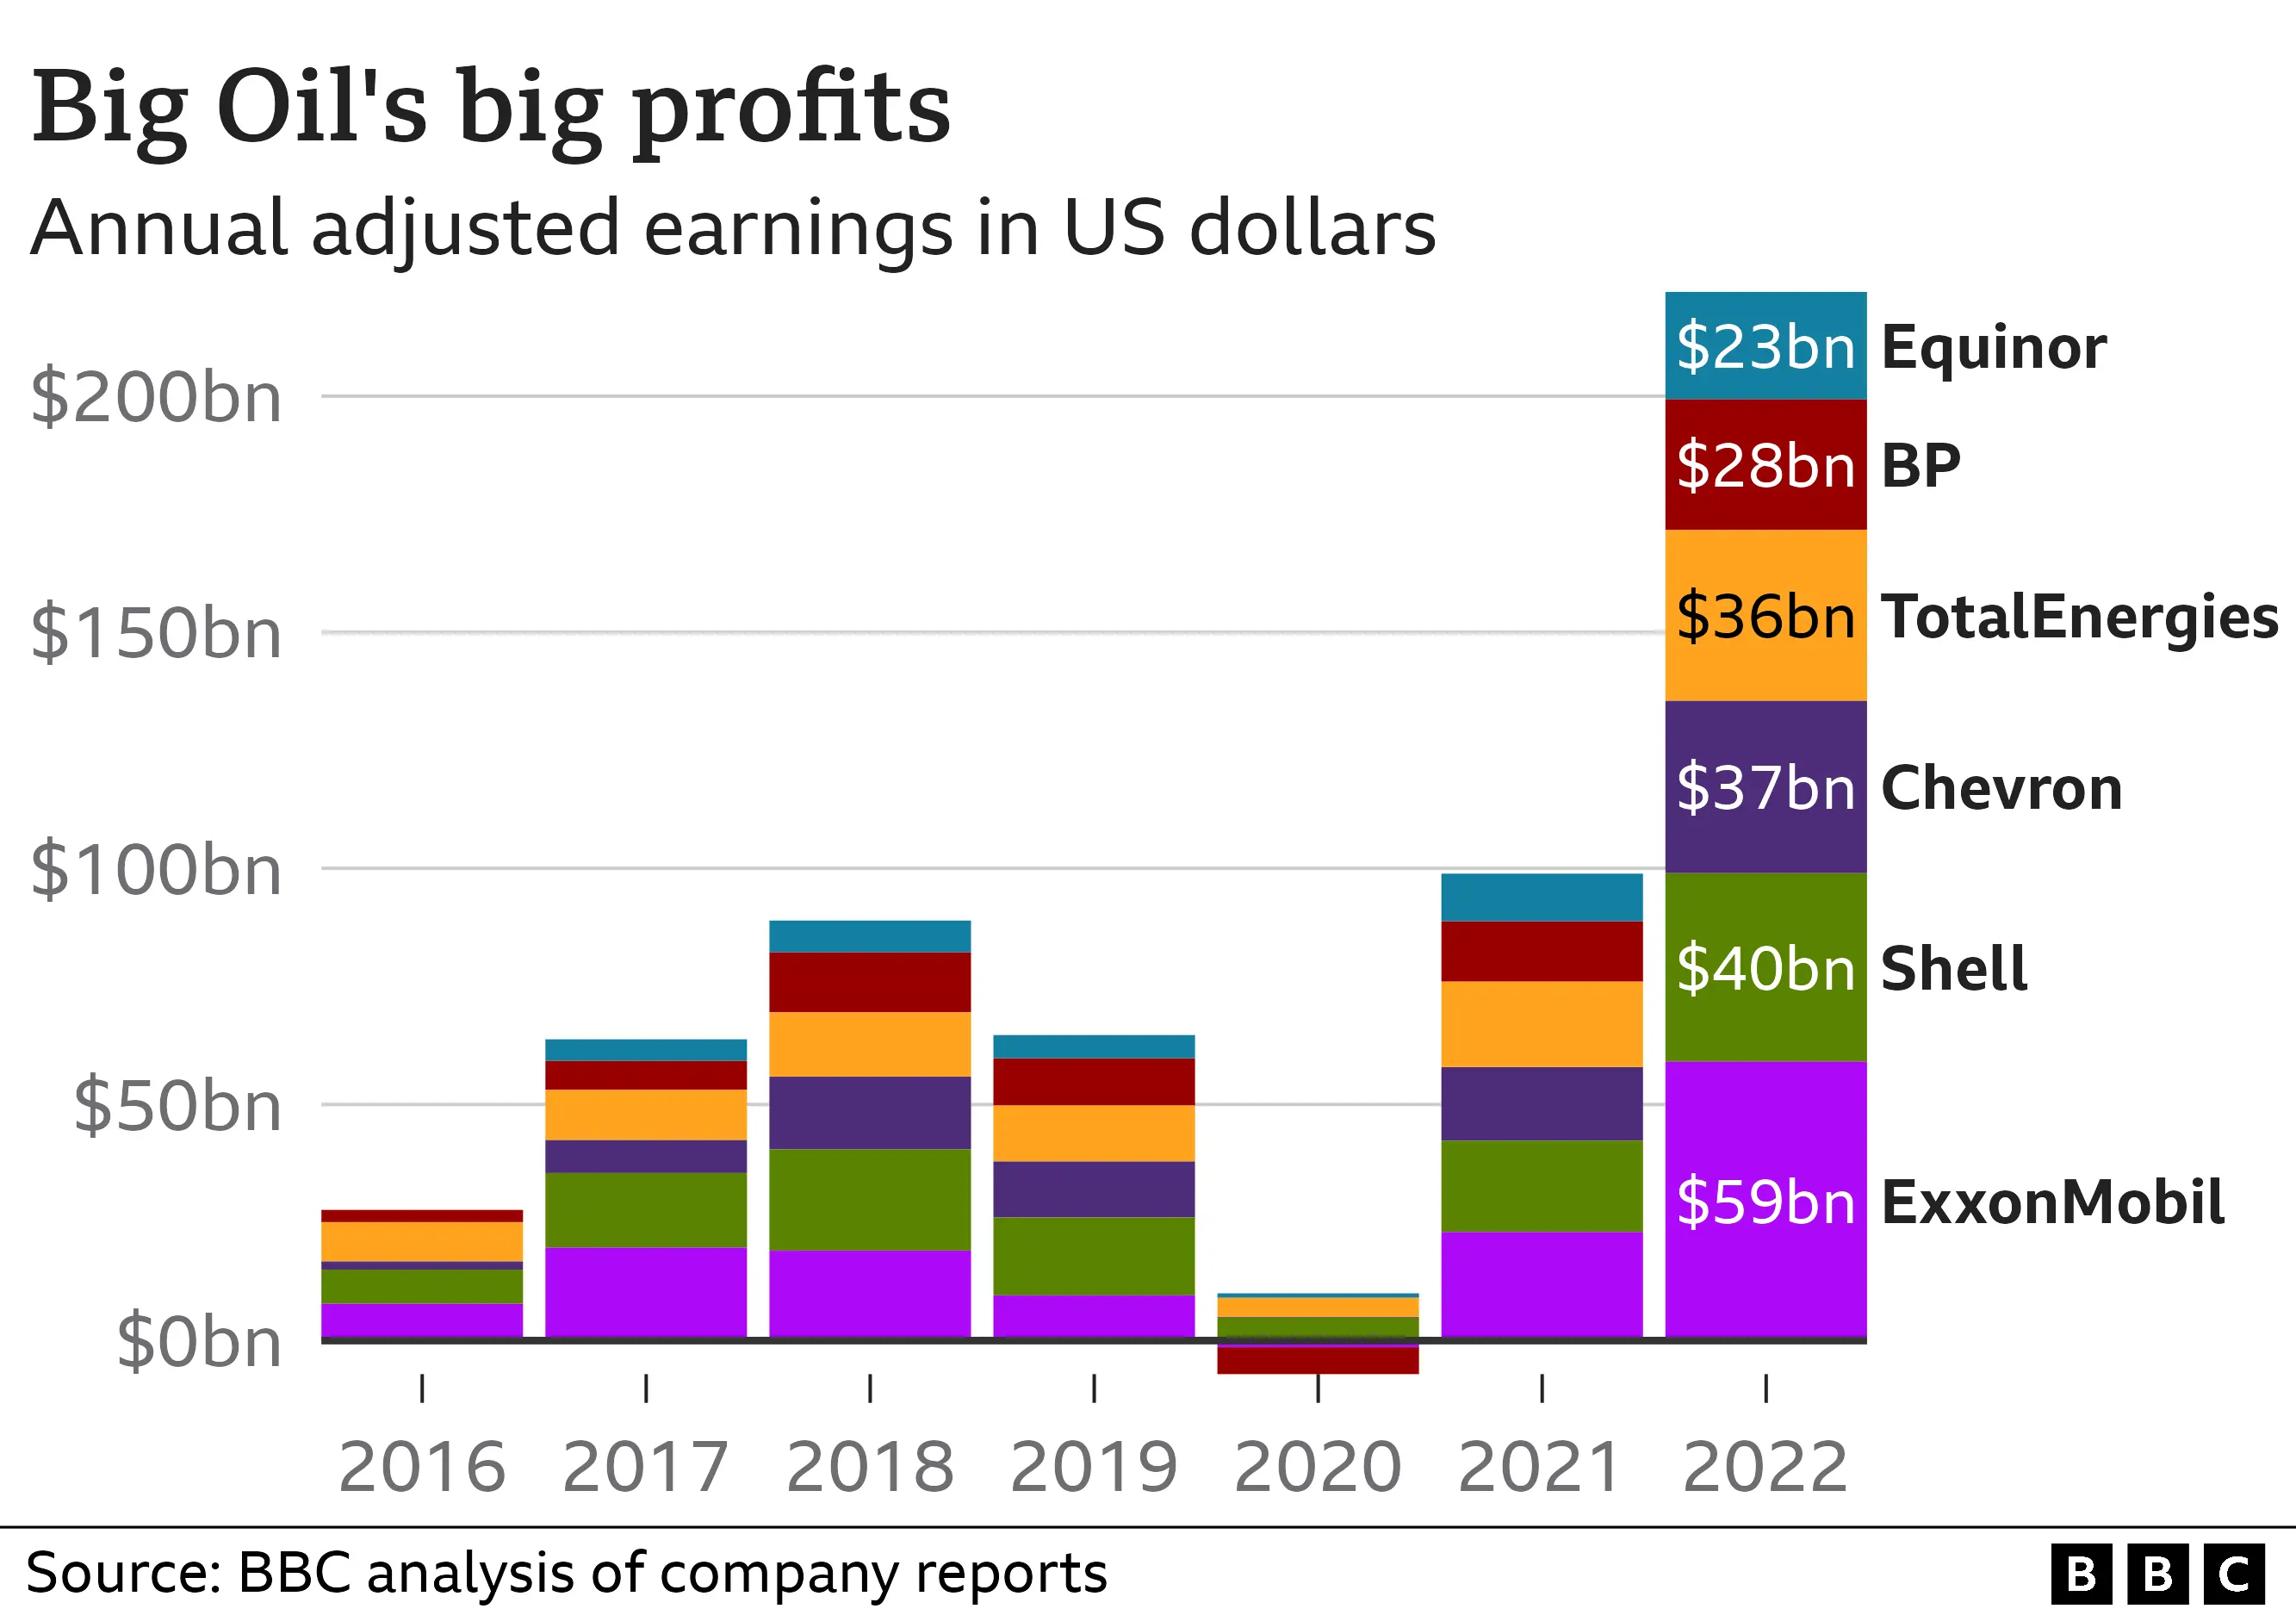
Global energy markets are experiencing a profound structural divergence. Even as central banks grapple with stubborn inflation and consumer spending power faces unprecedented contraction, the world's premier multinational hydrocarbon enterprises have once again reported staggering quarterly profits. This latest surge in corporate cash flow underscores a fundamental reality of the modern global economy: traditional energy infrastructure remains the primary engine of macroeconomic liquidity, capital distribution, and valuation multiples, despite aggressive global pushes toward decarbonization.
As investigative teams across the financial capitals of New York, London, and Houston analyze the latest balance sheets, a clear picture emerges. The resurgence in profitability is not merely a byproduct of volatile commodity pricing; it is the direct result of disciplined capital allocation, rigorous asset portfolio optimization, and an unwavering focus on enterprise ROI. This deep-dive report examines the mechanics behind the windfall, the underlying market catalysts, and the long-term implications for institutional investors, regulatory compliance frameworks, and global energy security.
Executive Takeaways
- Unprecedented Cash Generation: Major oil conglomerates have combined quarterly net incomes exceeding historic baselines, driven by optimized upstream extraction and high-margin refining spreads.
- shift in Capital Allocation Strategy: Unlike previous cycles of aggressive drilling expansion, current executive leadership is prioritizing shareholder distributions, equity buybacks, and balance sheet deleveraging over high-risk greenfield exploration.
- Macroeconomic Divergence: The widening gap between soaring corporate earnings and stagnant consumer purchasing power is intensifying political scrutiny and stoking renewed debates over windfall taxation and regulatory compliance.
- Technology Integration: Modern extraction operations are increasingly reliant on advanced cloud compute architecture, predictive maintenance algorithms, and real-time telemetry to minimize operational expenditures and maximize resource recovery rates.
The Catalytic Anatomy of the Profit Surge

To understand how oil majors are consistently outpacing market expectations, one must look beyond headline crude benchmarks such as Brent and West Texas Intermediate (WTI). The modern supermajor operates as an integrated global energy matrix spanning upstream exploration, midstream logistics, and downstream refining and petrochemical processing. When downstream margins expand concurrently with resilient upstream realizations, net income amplification is virtually guaranteed.
Over the past four quarters, geopolitical friction points across Eastern Europe and the Middle East have severely tested global supply chain resilience. Rather than panicking or flooding the market with excess supply—a historical tendency that often destroyed long-term valuation multiples—executive boards have maintained strict operational discipline. This risk mitigation strategy has effectively institutionalized a higher baseline for global energy pricing.
Furthermore, structural underinvestment in global oil and gas infrastructure over the preceding half-decade has created a supply inelasticity. When global demand recovers or holds steady in the face of macroeconomic headwinds, the lack of redundant production capacity acts as a natural price floor. Consequently, free cash flow (FCF) yields across the sector have decoupled from broader industrial indices, attracting substantial institutional capital seeking reliable yield and robust dividend sustainability.
Data & Metrics Breakdown
A rigorous examination of the recent earnings cycle reveals the sheer scale of the financial inflows. The following table contrasts the financial performance, operational metrics, and capital return strategies of the world's leading publicly traded energy titans during the most recent reporting period.
| Company | Net Income (Q3/Q4) | Free Cash Flow | Shareholder Distributions | Primary Capital Focus |
|---|---|---|---|---|
| ExxonMobil (XOM) | $9.1 Billion | $11.4 Billion | $8.1 Billion (Dividends & Buybacks) | Permian Basin expansion & Low-carbon ventures |
| Chevron (CVX) | $6.5 Billion | $8.7 Billion | $6.0 Billion (Dividends & Buybacks) | Hess acquisition integration & Permian assets |
| Shell plc (SHEL) | $6.0 Billion | $7.5 Billion | $5.5 Billion (Dividends & Buybacks) | Liquefied Natural Gas (LNG) & portfolio streamlining |
| TotalEnergies (TTE) | $5.1 Billion | $6.2 Billion | $4.8 Billion (Dividends & Buybacks) | Integrated LNG & Integrated Power portfolio |
Industry & Market Implications
The asymmetric financial performance of multinational energy enterprises carries profound systemic consequences across the global financial ecosystem.
Who Wins
- Institutional Equity Holders: Pension funds, mutual funds, and retail investors holding energy-weighted indices are reaping historically high dividend yields and capital appreciation.
- Energy Technology & Services Providers: Oilfield service giants benefiting from increased spending on brownfield optimization, digital oilfield infrastructure, and enhanced recovery techniques.
- Debt Holders & Creditors: With balance sheets flush with liquidity, corporate credit ratings have strengthened significantly, reducing borrowing costs and default risk across the sector.
Who Loses
- Retail Consumers: High refining margins and sustained crude prices directly translate into elevated retail fuel costs, compounding cost-of-living pressures globally.
- Energy-Intensive Manufacturing: Chemical, steel, and heavy manufacturing sectors face compressed operating margins due to high input costs for energy and feedstock.
- Aggressive Transition Advocates: Environmental policy groups argue that massive fossil fuel profits delay necessary capital deployment toward utility-scale renewable energy infrastructure and green hydrogen projects.
Frequently Asked Questions (People Also Ask)
Why are oil company earnings so high despite global efforts to transition to renewable energy?
Oil company earnings remain robust due to a combination of disciplined capital allocation, structural underinvestment in new fossil fuel production over the past several years, and strong global demand for liquid fuels and petrochemicals. Rather than prioritizing rapid volume growth, energy executives are focusing on high-margin assets, operational efficiencies, and maximizing free cash flow, which has institutionalized higher profitability floors.
How are oil majors returning capital to their shareholders?
Major energy enterprises are primarily distributing excess liquidity through a combination of stable, growing quarterly dividends and aggressive share repurchase (buyback) programs. This dual approach helps support equity valuations and rewards long-term institutional investors seeking reliable yield in an inflationary macroeconomic environment.
Are these soaring profits triggering increased government regulation or taxation?
Yes. The stark contrast between record-breaking corporate earnings and high consumer energy prices has intensified political pressure in Washington, Brussels, and other capitals. Lawmakers frequently revisit proposals for windfall profit taxes, increased environmental compliance burdens, and stricter oversight of refining margins, though legislative outcomes vary significantly by jurisdiction.
What role does technology play in modern oil company profitability?
Digital transformation has become a critical profit driver. Energy firms utilize advanced cloud compute architecture, IoT telemetry sensors, and artificial intelligence models for predictive maintenance, seismic imaging, and automated drilling. These technological investments significantly lower finding and development (F&D) costs, boosting enterprise ROI.
Future Outlook & Strategic Milestones
Looking ahead, the trajectory of oil company earnings will depend heavily on three critical variables: macroeconomic growth trajectories in key consuming nations like China and the United States, geopolitical stability in major producing regions, and the speed of monetary policy adjustments by central banks.
Key milestones to watch in the upcoming quarters include:
- Consolidation Waves: Regulatory rulings and final shareholder votes on multi-billion dollar M&A transactions currently pending in the Permian and offshore basins.
- Energy Transition CapEx Adjustments: How executive boards balance short-term shareholder return expectations with long-term capital commitments to carbon capture, utilization, and storage (CCUS) and low-carbon hydrogen.
- Inventory and Storage Data: Weekly commercial crude and product inventory reports issued by the Energy Information Administration (EIA) as indicators of real-time market balance.
Ultimately, while political rhetoric surrounding fossil fuel profitability will remain fierce, financial markets continue to reward companies that demonstrate disciplined capital stewardship, technological agility, and robust free cash flow generation. The latest earnings super-cycle proves that traditional energy remains an indispensable pillar of global economic stability.