The Macroeconomic Landscape: Navigating the Post-2023 Disinflationary Wave
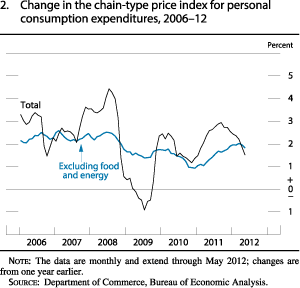
The architecture of global finance is undergoing a profound structural recalibration. Following the historic inflationary spikes that tested the resilience of central banks worldwide throughout the early 2020s, recent economic and financial developments point toward a nuanced normalization. According to comprehensive data released via Federal Reserve wire channels, consumer price inflation—which stepped down notably from its blistering 2023 velocity—has continued to ease, albeit along an uneven, bumpy trajectory.
For enterprise executives, private equity sponsors, and institutional asset managers, this environment demands a sophisticated reassessment of capital allocation and operational execution. The era of ultra-cheap debt has definitively closed, forcing corporations to prioritize organic enterprise ROI over speculative leverage. As regional Federal Reserve Bank presidents convened to synthesize domestic and international intelligence, the consensus emerging from closed-door deliberations is clear: the economy has avoided a catastrophic hard landing, yet structural price pressures in service sectors and labor markets prevent an immediate return to pre-pandemic monetary policy baselines.
Inside the Boardroom: Regional Insights and Global Spillovers
The operational cadence of the Federal Reserve relies heavily on ground-level intelligence synthesized by regional banks. Insights originating from the Federal Reserve Bank of New York—alongside granular updates delivered by each Bank president around the policy table—paint a multifaceted portrait of the United States economy interacting with volatile global markets. International trade realignments, European energy market shifts, and Asian manufacturing adjustments have all cascaded into domestic pricing models.
During recent policy evaluations, financial sector executives reported that corporate borrowers are tightening credit standards. Risk mitigation has become the paramount corporate mandate. Consequently, chief financial officers are scrutinizing cloud compute architecture expenditures, software licenses, and supply chain redundancies to safeguard operating margins. This defensive posture ensures that while macroeconomic inflation moderates on paper, microeconomic cost pressures force corporations to maintain stringent pricing power where available.
Verified Data & Metrics Breakdown
To understand the mechanics driving contemporary monetary policy, market participants must examine the core economic indicators tracking price stability, labor market dynamics, and financial system liquidity.
| Economic Indicator | 2023 Baseline Peak | Current Tracking (2026) | Strategic Implications |
|---|---|---|---|
| Headline CPI Inflation | Elevated / Volatile | Further Eased & Stabilizing | Reduces pressure for aggressive emergency rate hikes. |
| Federal Funds Rate Target | Restrictive Territory | Calibrated Plateau / Easing Bias | Dictates valuation multiples and cost of debt financing. |
| Corporate Credit Spreads | Moderately Gapped | Tightening / Stable Liquidity | Facilitates corporate refinancing and infrastructure scalability. |
| Labor Cost Growth | Rapid Wage Expansion | Normalizing to Productivity | Alleviates sticky core service sector inflation pressures. |
Industry & Market Implications: Winners, Losers, and Corporate Strategy
Shifts in monetary velocity create immediate asymmetries across global equity and debt markets. Institutional capital is currently flowing toward sectors exhibiting robust infrastructure scalability and clear regulatory compliance frameworks. Technology enterprises integrating advanced automation and high-efficiency cloud architectures are capturing outsized valuation multiples, as investors reward durable cash-flow generation over speculative growth narratives.
Conversely, capital-intensive industries burdened by legacy debt structures face sustained headwinds. Real estate, highly leveraged retail, and unhedged manufacturing entities find themselves squeezed between sticky operational overhead and tighter lending standards enforced by regional commercial banks. For these market participants, strategic debt restructuring and aggressive cost containment are no longer optional—they are prerequisites for corporate survival.
Frequently Asked Questions (People Also Ask)
What factors are currently driving the continued easing of consumer price inflation?
The sustained moderation in consumer price inflation stems from a combination of resolved supply chain bottlenecks, stabilized energy markets, and labor cost growth aligning more closely with underlying worker productivity. Additionally, the lagged cumulative effects of the Federal Reserve's restrictive monetary policy have successfully cooled excessive aggregate demand across both goods and housing sectors.
How do regional Federal Reserve banks influence national monetary policy decisions?
Regional Fed presidents gather real-time economic intelligence from local business leaders, agricultural producers, and commercial bankers within their respective districts. During Federal Open Market Committee (FOMC) meetings, these insights—coupled with specialized reports from institutions like the Federal Reserve Bank of New York—provide critical grassroots data that ensure national interest rate targets and market liquidity interventions reflect localized economic realities.
What are the implications of current economic developments for corporate valuation multiples?
As monetary conditions transition away from emergency stimulus levels, institutional investors are placing a premium on financial health and predictable cash flows. Corporations with strong balance sheets, scalable cloud and digital infrastructure, and efficient capital allocation strategies are maintaining healthy valuation multiples. Meanwhile, highly leveraged firms face compressed multiples as higher borrowing costs weigh heavily on net earnings.
How should enterprise leaders approach risk mitigation in this macroeconomic environment?
Enterprise leadership teams should prioritize rigorous balance sheet management, diversification of funding sources, and proactive regulatory compliance monitoring. By focusing on operational efficiency, optimizing enterprise ROI on technology investments, and maintaining conservative liquidity buffers, organizations can effectively insulate themselves against lingering macroeconomic volatility.
Future Outlook & Key Milestones to Watch
As the financial markets look toward the remainder of 2026 and beyond, attention remains squarely fixed on the Federal Reserve's balance sheet normalization path and incoming employment data. Market participants should monitor upcoming quarterly earnings calls for commentary regarding enterprise pricing power and capital expenditure revisions. Key milestones, including monthly employment reports, core PCE inflation readings, and regional manufacturing surveys, will dictate whether central bankers enact further policy loosening or maintain a patient, restrictive stance.
Ultimately, navigating this economic crossroads demands vigilance. Institutions that integrate rigorous risk mitigation frameworks, maintain disciplined capital allocation, and remain adaptable to shifting global liquidity dynamics will successfully capture long-term value in an evolving monetary regime.