Executive Takeaways
- Macro Valuation Contraction: Disappointing Q3 and Q4 enterprise tech earnings have triggered a valuation compression across private secondary markets, directly depressing SpaceX’s liquidity metrics and implied market capitalization.
- The Musk Bar Fallacy: Elon Musk’s internal capital allocation frameworks and hyper-growth expectations have created an operational standard that virtually no other aerospace, defense, or enterprise software competitor can match.
- Infrastructure Scalability Bottlenecks: While Starlink and Starship continue aggressive deployment schedules, broader market volatility highlights vulnerabilities in capital expenditure financing, cloud compute architecture, and regulatory compliance.
- Secondary Market Liquidity Shift: Institutional investors are recalibrating risk mitigation strategies, pulling back from speculative growth plays to favor balance sheet fortification and proven enterprise ROI.
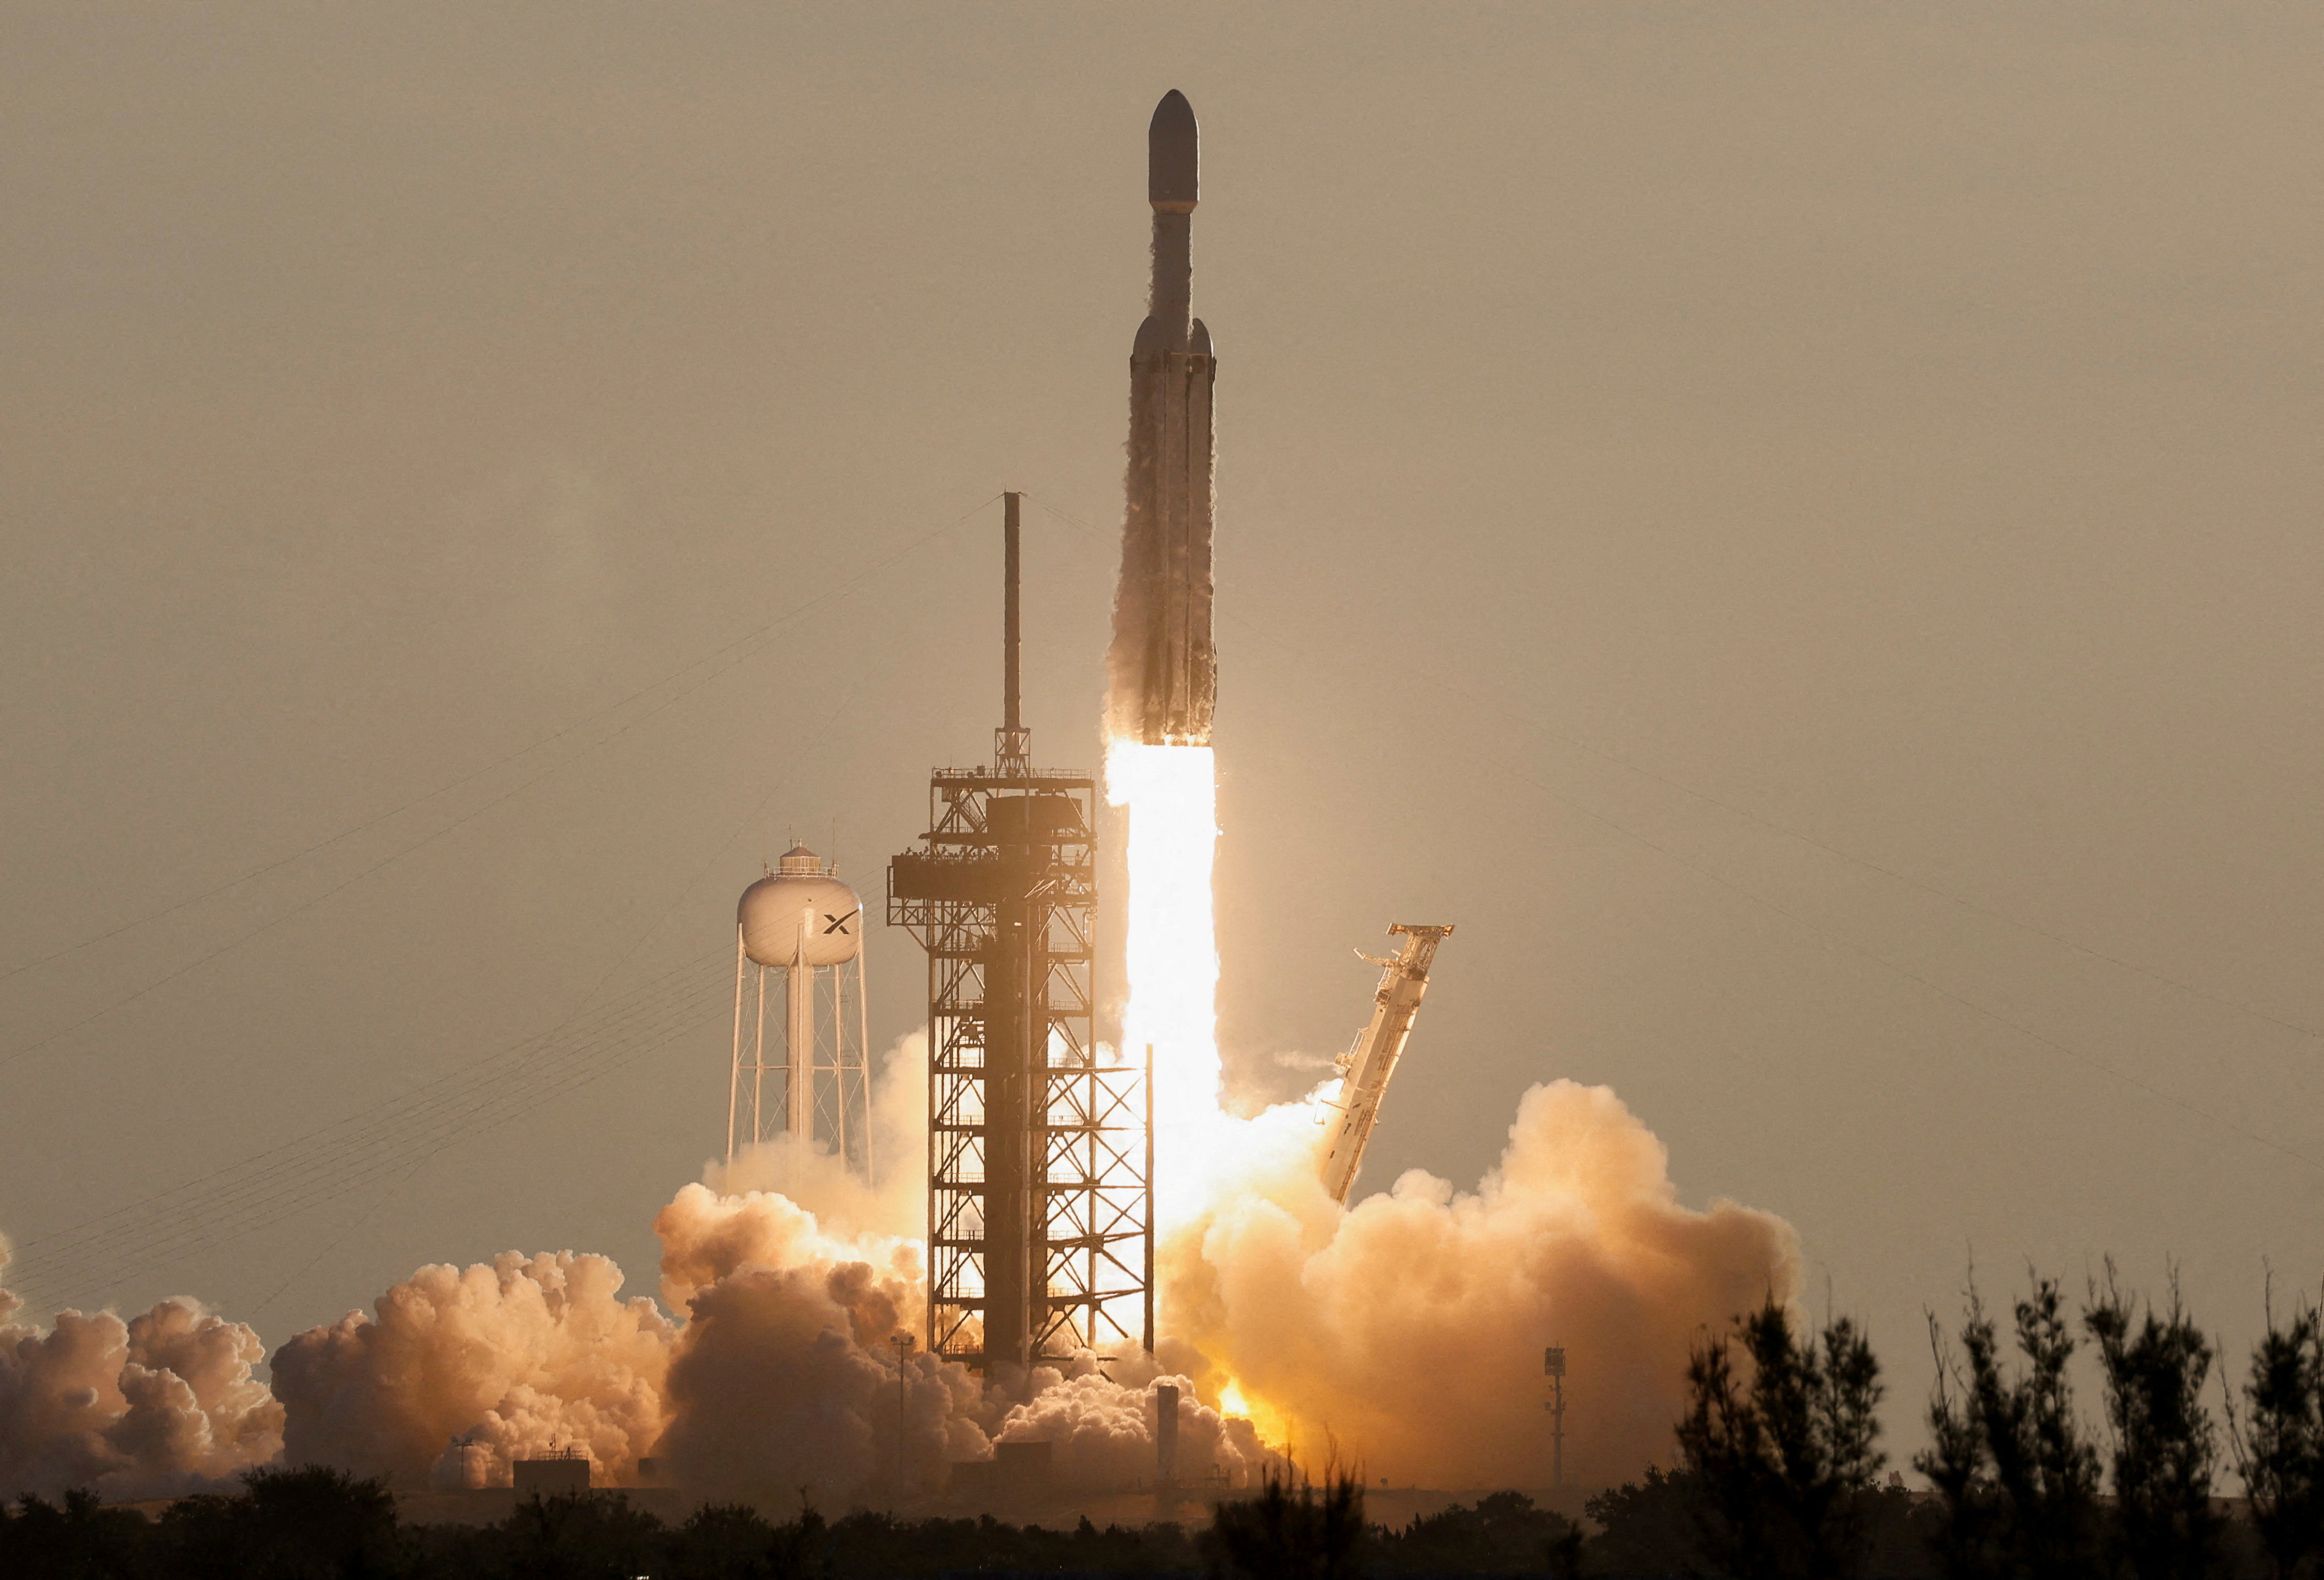
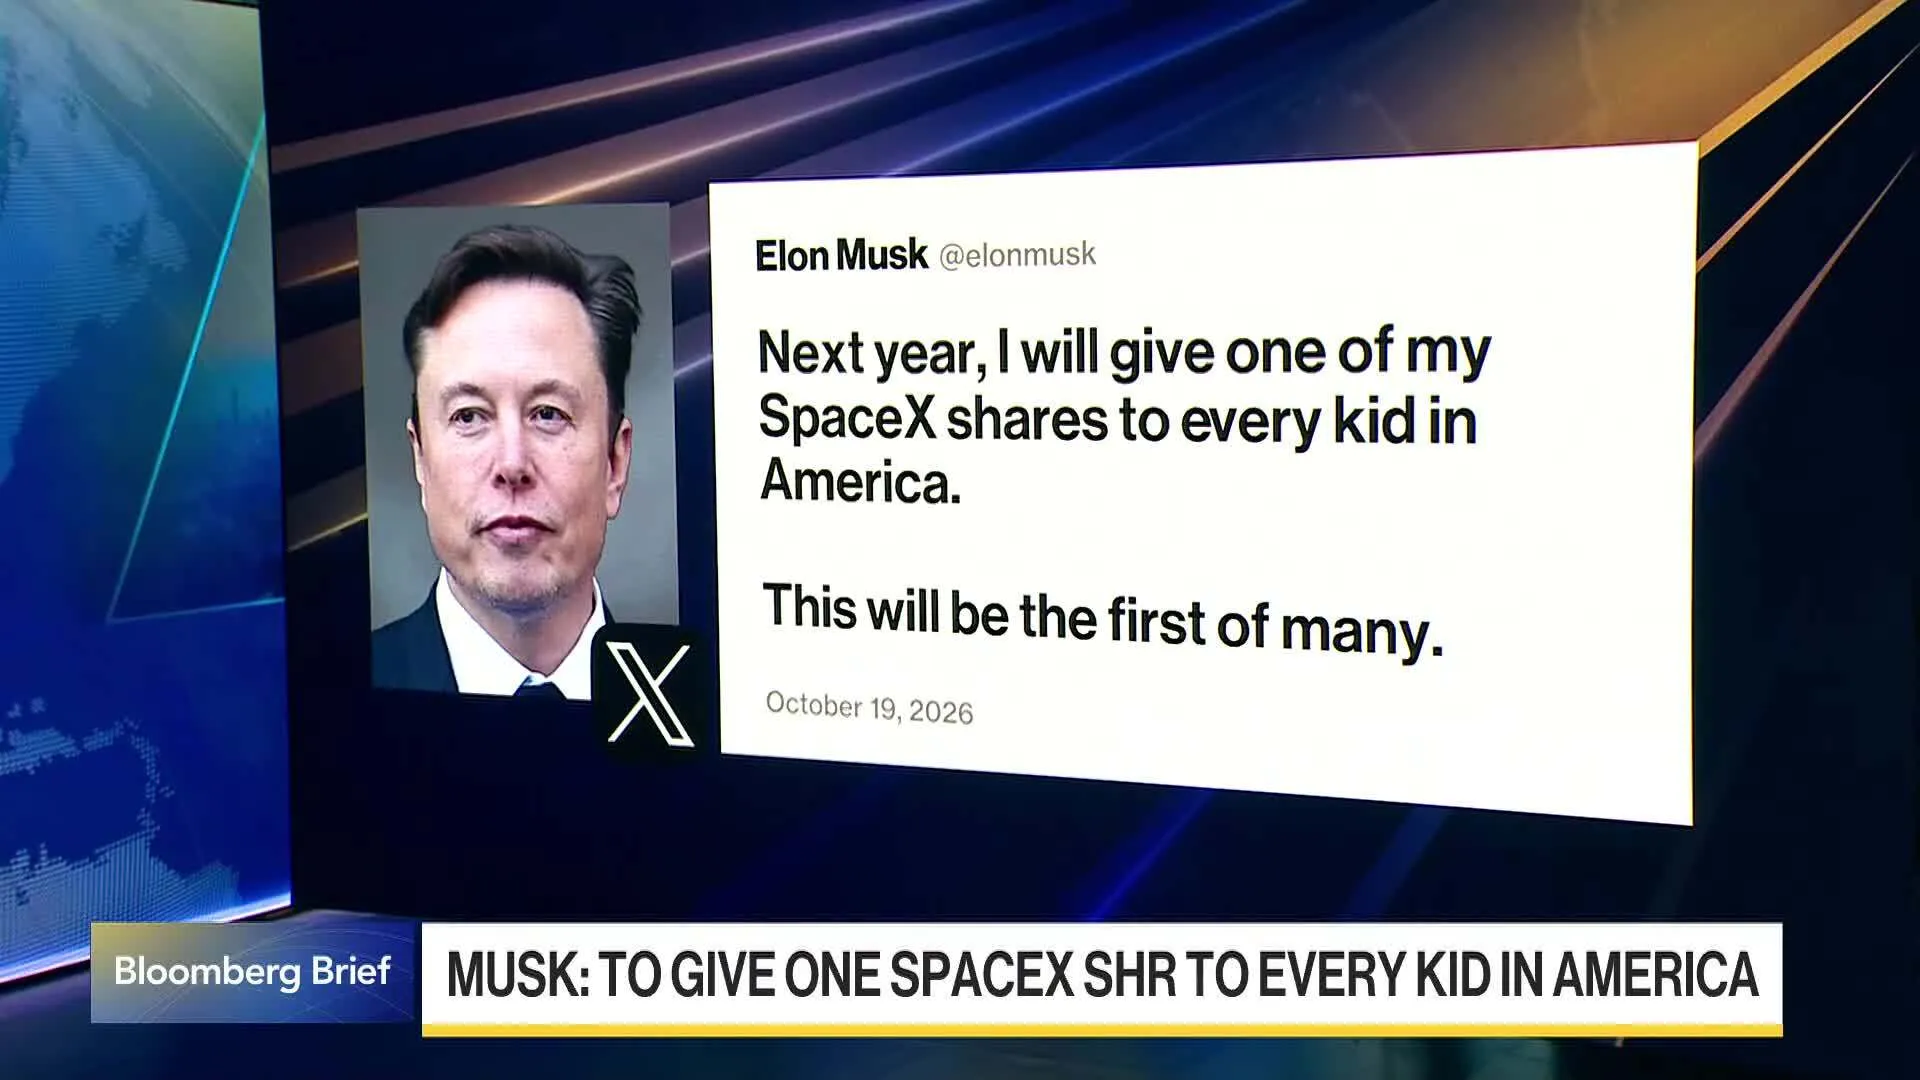
The global financial ecosystem is undergoing a violent tectonic shift. In the wake of a turbulent corporate earnings season characterized by compressed margins, inflated cloud compute architecture costs, and cautious executive guidance across the technology sector, private market sentiment has experienced a profound correction. At the epicenter of this valuation re-rating is SpaceX—the world's most valuable private enterprise, helmed by billionaire entrepreneur Elon Musk. Recent secondary market transactions reveal a startling reality: tech earnings have dragged down SpaceX stock momentum, laying bare a stark reality that institutional investors are only now beginning to price in—no other company in the modern industrial complex meets Elon Musk’s uncompromising operational and financial bar.
For months, financial analysts, venture capitalists, and hedge fund allocators viewed SpaceX as an unassailable macroeconomic hedge. Immune to standard public market volatility due to its private status and the compounding dominance of the Starlink satellite internet constellation, the company commanded staggering valuation multiples. However, as public tech bellwethers reported earnings that signaled slowing enterprise adoption, constrained infrastructure scalability, and tighter capital allocation, the gravity of the broader market caught up to Hawthorne. The ripple effects have redefined how Wall Street evaluates hyper-growth engineering firms, forcing a rigorous examination of capital efficiency, cash flow conversion, and the true cost of orbital dominance.
The Catalytic Disconnect: How Public Tech Earnings Poisoned Private Valuations
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
The mechanics linking public tech earnings to private aerospace and defense valuations are rooted in institutional liquidity and portfolio rebalancing. When major enterprise technology providers—spanning cloud infrastructure, artificial intelligence compute providers, and enterprise SaaS platforms—miss revenue expectations or guide down capital expenditure (CapEx) forecasts, institutional limited partners (LPs) feel immediate pressure.
These LPs, which include massive sovereign wealth funds, pension systems, and endowment managers, rely on public market liquidity to fund private market capital calls. As public tech valuations contracted, portfolios became overallocated to illiquid assets, triggering a liquidity crunch. To rebalance portfolios, institutional investors turned to secondary marketplaces—such as Forge Global and EquityZen—to offload shares in private giants like SpaceX, Stripe, and OpenAI at discounted valuations.
This forced selling pressure exposed a fundamental vulnerability: SpaceX’s valuation has long been tethered not just to its own cash flow generation, but to the broader risk appetite of tech-heavy equity portfolios. When tech earnings sink, the valuation multiples assigned to future-state cash flows—such as those projected for global satellite-based cellular services and Martian colonization logistics—shrink accordingly. The market is no longer willing to pay an infinite premium for pure technological potential; it demands near-term margin expansion, verified enterprise ROI, and undeniable regulatory compliance.
The Musk Standard: An Impossibly High Bar for Global Competitors
At the core of the current market anxiety is the realization that Elon Musk operates under an economic and engineering paradigm that cannot be replicated by legacy aerospace contractors, state-backed agencies, or venture-backed startups. Musk’s management philosophy hinges on radical vertical integration, extreme risk tolerance, and relentless iterative design—a combination that demands staggering upfront capital deployment offset by exponential future cost reductions.
Consider the competitive landscape:
- Legacy Defense Contractors: Firms bound by cost-plus government contracting models struggle with innovation velocity. Their capital allocation strategies prioritize share buybacks and predictable dividends over iterative, high-failure hardware development.
- New Space Startups: Dozens of rocket and satellite ventures attempting to challenge SpaceX face a severe funding winter. With venture capital dry powder drying up due to poor tech sector realizations, these competitors lack the balance sheet strength to survive prolonged capital expenditure cycles.
- Telecommunications Giants: Traditional terrestrial and geostationary satellite operators find themselves structurally unable to match the launch cadence and unit economics of Falcon 9 and Starship, rendering their infrastructure scalability obsolete in the face of low-earth-orbit (LEO) saturation.
Yet, even against this backdrop of unrivaled dominance, SpaceX is not entirely insulated. The capital intensity of developing a fully reusable, multi-planetary transport system like Starship requires continuous access to deep capital markets. When tech earnings stumble and investor enthusiasm cools, the cost of capital rises, forcing even Musk’s empire to navigate a more disciplined financial landscape.
Verified Market Data & Valuation Metrics Breakdown
To understand the magnitude of the recent secondary market adjustments and the divergence between SpaceX's operational performance and macroeconomic pressures, examine the following comparative metrics:
| Metric / Indicator | SpaceX (Private Market) | Public Tech Sector Average | Traditional Aerospace & Defense |
|---|---|---|---|
| Implied Valuation Multiple | High Growth / Premium (Compressed 8-12%) | Declining (Multiple contraction across P/E) | Stable / Moderate (15x - 22x earnings) |
| Capital Expenditure Focus | Heavy R&D, Starship, LEO Constellation | AI Compute Infrastructure & Data Centers | Government-backed Defense Contracts & R&D |
| Secondary Market Liquidity | Restricted / Subject to Institutional Rebalancing | High Liquidity (Daily Public Exchange Volume) | High Institutional Ownership & Dividends |
| Operational Margin Profile | Starlink Gross Margin Expansion; Heavy CapEx | Pressure on Operating Margins due to AI Costs | Predictable, Low-Double-Digit Margins |
Industry & Market Implications: Winners, Losers, and Economic Fallout
The broader economic implications of this valuation correction extend far beyond SpaceX’s Hawthorne headquarters. As institutional investors recalibrate their risk mitigation strategies, several structural shifts are reshaping the global financial and industrial landscape:
The Losers: Speculative Startups and Undercapitalized Competitors
The primary casualties of this environment are early-to-mid-stage space and deep-tech companies that relied on loose monetary policy and exuberant venture funding. Without clear paths to profitability or immediate enterprise contracts, these firms face existential threats. Mergers, acquisitions, or outright liquidations will dominate the sector as venture capitalists prioritize portfolio triage over new investments.
The Winners: Cash-Rich Dominators and Disciplined Enterprises
SpaceX, despite near-term valuation headwinds, remains structurally positioned to outlast competitors. Because Starlink is rapidly scaling its consumer and enterprise subscriber base, generating robust recurring cash flow, the company possesses the internal financial engine required to weather public market turbulence. Furthermore, mature defense primes with stable government cash flows will continue to secure conservative institutional backing.
Broader Economic Impact
The tightening of capital markets serves as a reality check for the entire technology ecosystem. The era of unchecked burn rates and speculative valuations driven by hype rather than fundamental economics has officially closed. Corporate boards across tech, telecommunications, and aerospace are shifting toward rigorous capital efficiency, demanding clear proof of operational resilience before unlocking funds for expansion.
Frequently Asked Questions (People Also Ask)
Why are tech earnings impacting the private valuation of SpaceX?
While SpaceX is a privately held company and not directly traded on public exchanges, its valuation is deeply influenced by institutional investor liquidity. When public tech earnings decline, institutional LPs face portfolio imbalances and capital crunches, forcing them to sell private shares on secondary markets to raise cash. This secondary market selling pressure leads to a valuation compression across top-tier private assets like SpaceX.
Does any competitor currently match SpaceX’s operational and financial model?
No. Competitors in the aerospace, defense, and satellite internet sectors either operate under restrictive government cost-plus contracting models or lack the massive balance sheet strength required for rapid iterative engineering. SpaceX’s vertical integration and proprietary launch capabilities give it an unmatched competitive moat.
How does Starlink affect SpaceX’s overall market valuation?
Starlink serves as the primary cash-flow catalyst for SpaceX. As the satellite constellation scales its subscriber base globally—expanding into enterprise, maritime, aviation, and direct-to-cell markets—it transforms SpaceX from a capital-intensive launch provider into a high-margin global telecommunications powerhouse, insulating it somewhat from macroeconomic shocks.
What is next for SpaceX’s valuation and capital strategy?
SpaceX will likely continue to optimize its capital allocation, balancing the massive infrastructure expenditures required for Starship development with the steady revenue inflows of Starlink. Market watchers will closely monitor secondary market pricing trends and potential corporate restructuring, such as a future public spin-off of the Starlink division, to unlock shareholder value.
Future Outlook: Milestones and Strategic Watchpoints
As the global economy navigates the fallout from compressed tech earnings, the trajectory of SpaceX will depend heavily on execution across several critical operational milestones over the next 12 to 24 months:
- Starship Orbital Catch and Full Reusability: Achieving rapid, full reusability for the Starship system will dramatically reduce cost-per-ton to orbit, cementing SpaceX’s technological supremacy and widening the gap against any nascent competition.
- Starlink Direct-to-Cell Commercial Rollout: Scaling cellular-to-satellite partnerships with major global telecom operators will unlock massive new total addressable markets (TAM), driving recurring enterprise revenue that appeals directly to conservative institutional investors.
- Regulatory Compliance and Spectrum Allocation: Navigating increasingly complex international spectrum rights, orbital debris mitigation mandates, and national security compliance will be critical to maintaining uninterrupted global operations.
- Secondary Market Stabilization: Monitoring whether secondary market pricing rebounds in tandem with stabilizing public tech earnings will provide a clear gauge of institutional risk appetite moving forward.
Ultimately, while tech earnings have temporarily dragged down SpaceX stock momentum on private secondary desks, the company's fundamental engineering prowess and infrastructure dominance remain unparalleled. Elon Musk’s high bar may be impossible for competitors to clear, but for SpaceX, meeting that standard is the only option to secure its multi-planetary future.