Executive Takeaways
- Earnings Inflection: Hon Hai posted a Q2 net income of NT$60 billion, up 35% year-over-year, beating consensus forecasts on the back of aggressive shipments of high-density AI server platforms and advanced cloud compute architectures.
- Accelerating Top-Line Momentum: July consolidated revenue surged 54% year-over-year, signaling that the mass manufacturing ramp of next-generation GPU server racks is progressing faster than Street models anticipated.
- Structural Margin Transformation: The contract manufacturing titan is successfully executing an aggressive transition away from low-margin consumer electronics assembly toward vertically integrated, high-margin AI computing components, including liquid cooling manifolds, power shelves, and high-speed interconnect switches.
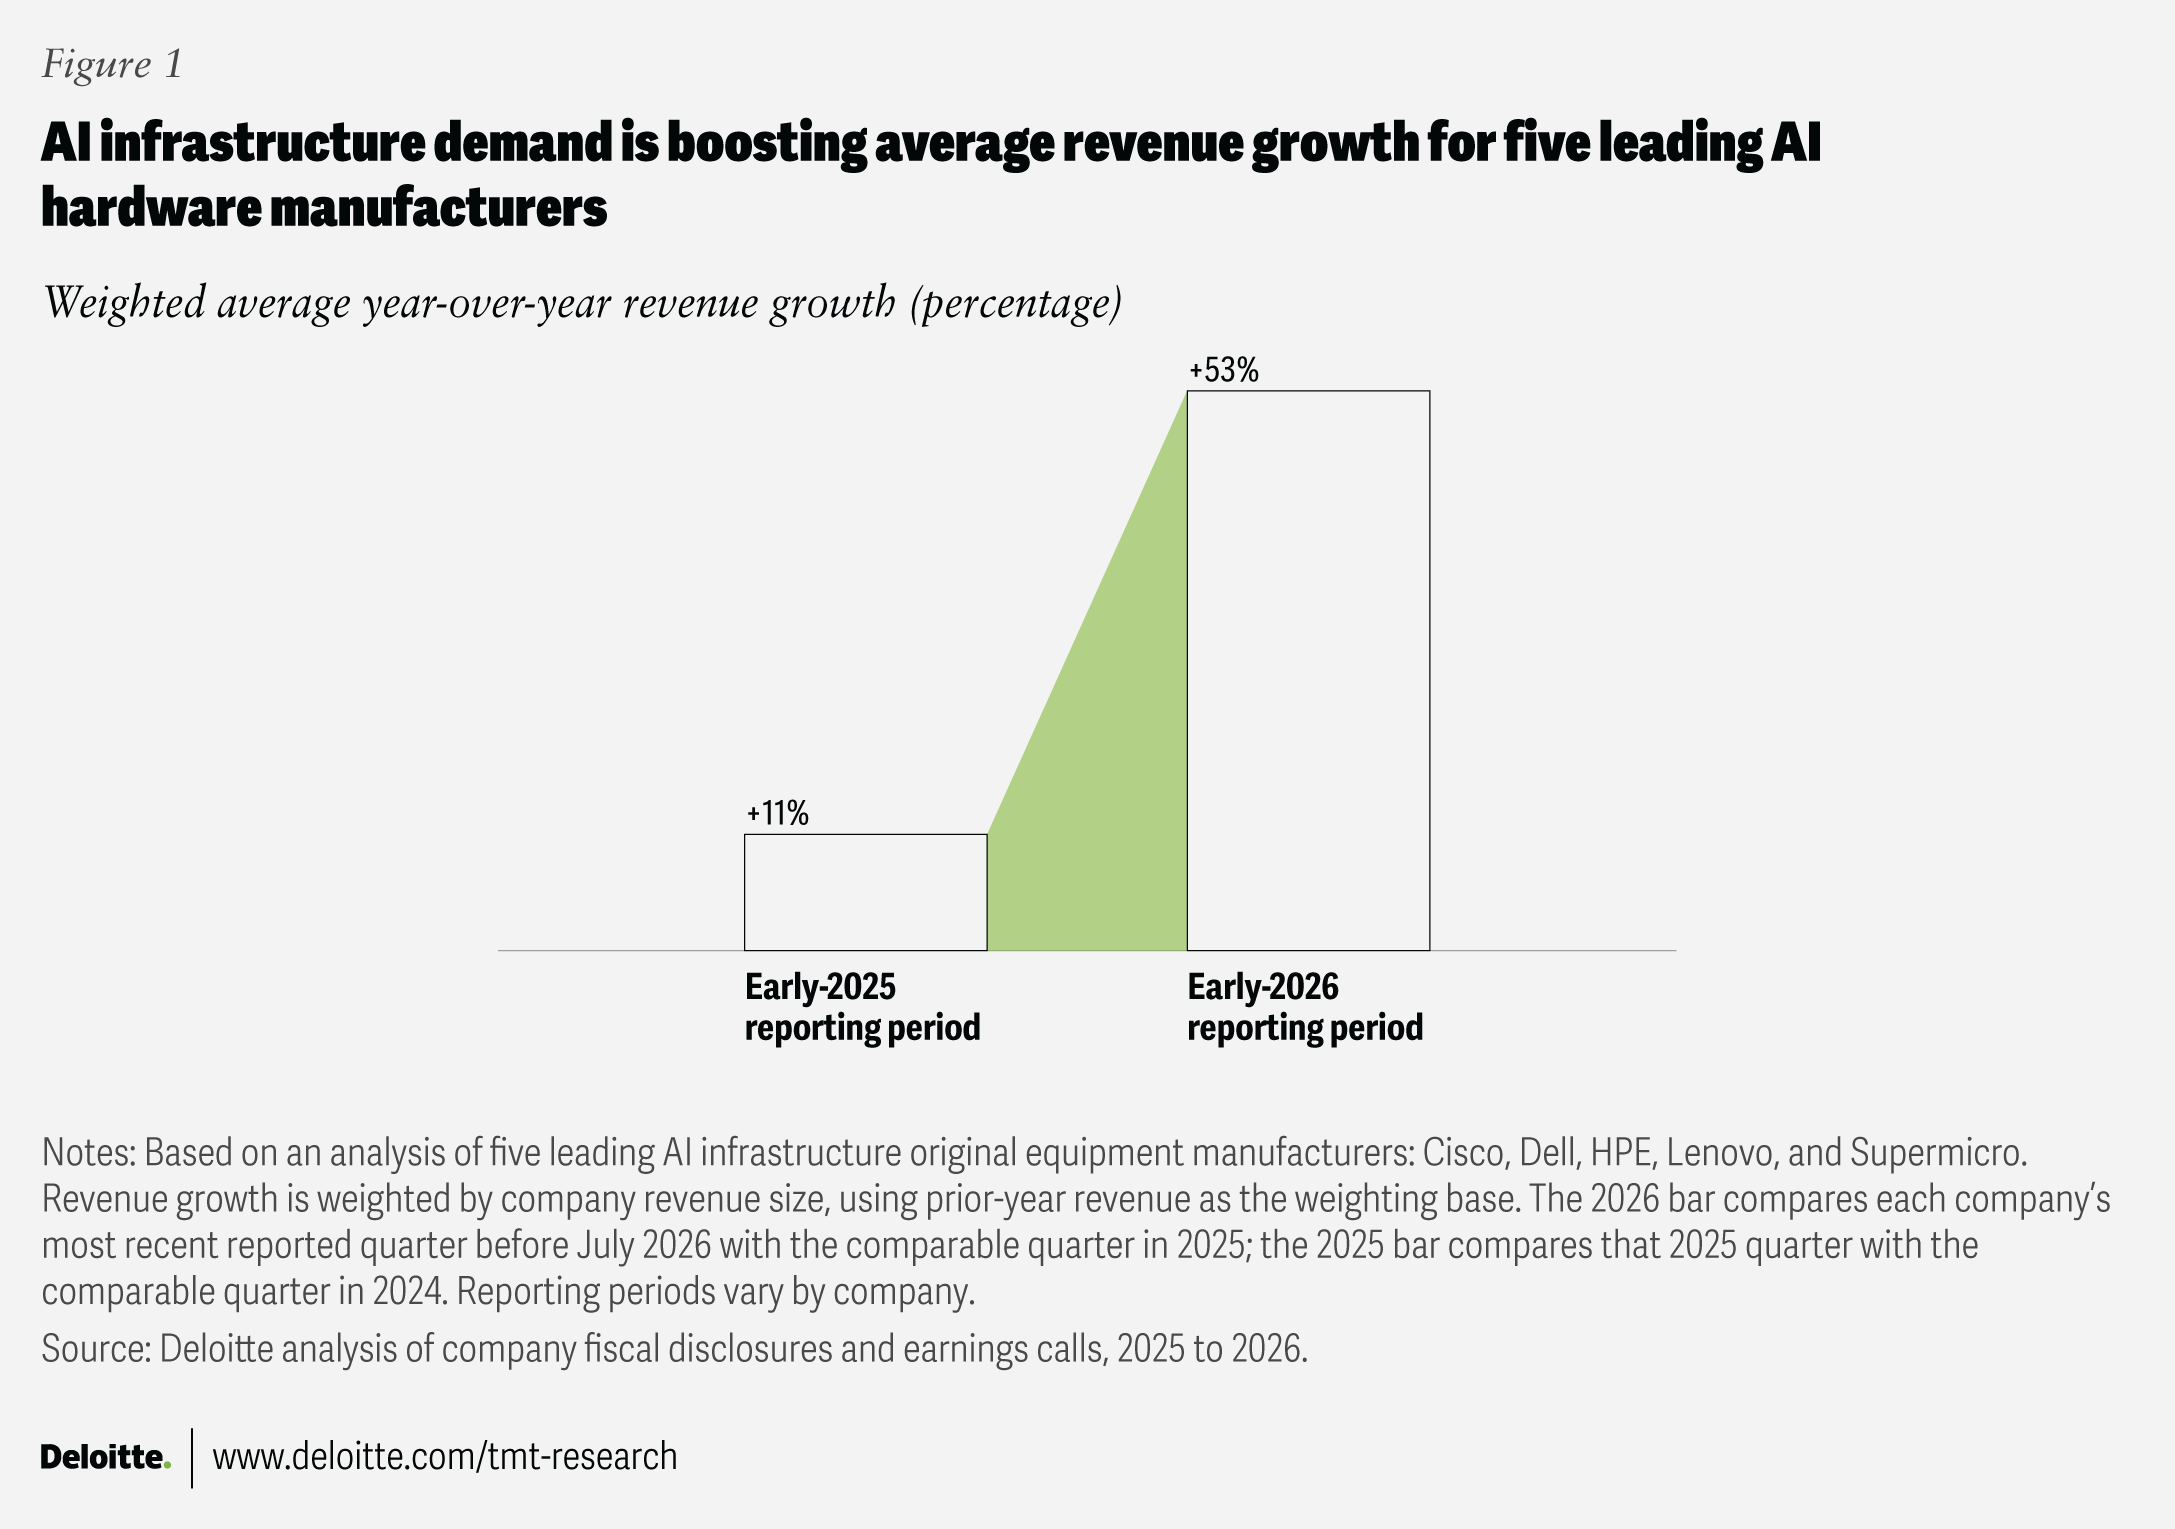
- Hyperscale Capex Validation: The metrics offer pristine real-world verification that Big Tech capital expenditure—surpassing $200 billion across Microsoft, Alphabet, Meta, and Amazon—is translating directly into cash flows for tier-one original design manufacturers (ODMs).
The AI Compute Barometer: How Hon Hai Captured the Hyperscale Wave
For decades, Hon Hai was viewed by institutional investors through a singular, restrictive lens: the quintessential assembly engine for Apple Inc.’s iPhone, subject to the seasonality of consumer replacement cycles and tight margin compressions. Today, the world’s largest contract electronics manufacturer has converted its balance sheet and immense manufacturing footprint into an indispensable tollbooth for global generative AI deployment.
Widely monitored by institutional trading desks as the ultimate "AI Computing Demand Barometer," Hon Hai's results reflect an unprecedented wave of procurement orders from global hyperscalers and sovereign wealth funds racing to secure GPU capacity. The Taiwanese conglomerate has leveraged its sprawling industrial footprint across Taiwan, North America, and Southeast Asia to capture dominant market share in the assembly and systemic integration of cutting-edge AI server racks, including Nvidia Corp.’s flagship architectures.
The catalytic catalyst behind the quarterly outperformance stems from the sheer complexity of current computing enclosures. While standard x86 enterprise servers are largely modular and commoditized, modern AI clusters—such as the liquid-cooled, multi-node NVL systems—require bespoke thermal management, extreme power distribution efficiency, advanced motherboard layouts, and ultra-high-speed network fabrics. By engineering and fabricating these structural and electrical sub-components in-house, Hon Hai captures incremental gross margin at nearly every tier of the physical rack assembly, insulating its operating margins from traditional contract-assembly dilution.
Deconstructing July's 54% Top-Line Breakout: A Supply Chain Squeeze Relieved
While the second-quarter net profit of NT$60 billion provided a high-water mark for earnings execution, Hon Hai’s July revenue print—leaping 54% year-over-year—sent shockwaves through sell-side desks in London, New York, and Hong Kong. The magnitude of this acceleration points to a major easing of previously choked upstream semiconductor bottlenecks.
Over the past four quarters, the primary headwind capping ODM server throughput was not demand elasticity, but severe capacity constraints in advanced packaging—specifically Taiwan Semiconductor Manufacturing Co.’s (TSMC) Chip-on-Wafer-on-Substrate (CoWoS) technology—and spot shortages of specialized high-bandwidth memory (HBM3e). Institutional channel checks indicate that substantial CoWoS capacity additions brought online by merchant foundries during the first half of the year are finally hitting production assembly lines in industrial volumes.
With component supply lines running fluidly, Hon Hai was able to transition from low-volume engineering builds to full-scale commercial manufacturing runs. The 54% July revenue surge represents the monetization of massive institutional backlog orders, with system integrators delivering turnkey compute clusters directly to data centers in Virginia, Silicon Valley, Ireland, and Singapore.
Comparative Metrics: Financial & Operational Performance
To fully contextualize Hon Hai's structural turnaround, the performance metrics must be contrasted against prior periods and historical enterprise hardware averages:
| Metric / Indicator | Q2 2026 Reported | Q2 2025 Comparative | YoY Delta | Strategic Driver & Analysis |
|---|---|---|---|---|
| Net Profit (Consolidated) | NT$60.0 Billion | NT$44.4 Billion | +35.1% | Surge in high-margin AI cluster integration and thermal component manufacturing. |
| July Monthly Revenue | NT$612.3 Billion (Est.) | NT$397.6 Billion | +54.0% | Resolution of CoWoS packaging bottlenecks; ramp of next-gen GPU rack platforms. |
| AI Server Contribution to Total Server Rev. | > 45% | ~ 28% | +1,700 bps | Accelerated enterprise and hyperscale migration toward parallel accelerated compute. |
| Server Business Blended Gross Margin | 8.2% – 8.8% (Est.) | 5.8% – 6.3% | +240 bps | Direct monetization of high-value subsystems (cold plates, power shelves, chassis). |
| Hyperscale Server Market Share | ~ 42% | ~ 34% | +800 bps | Consolidation of tier-one contracts due to global factory footprint and execution speed. |
Capital Allocation, Liquid Cooling, and The Battle for High-Density Systems
Beneath the headline financial numbers lies an intensive engineering paradigm shift. As silicon densities breach thermodynamic limits, the transition from legacy air-cooled server rooms to direct-to-chip liquid cooling architectures has become a mandatory technical hurdle for hyperscale operators. Hon Hai's forward-deployed research and development strategy has turned this thermal bottleneck into an extraordinary competitive moat.
Rather than acting solely as a passive system integrator assembling third-party kits, Hon Hai has built proprietary manufacturing capabilities across the entire thermal stack:
- Coolant Distribution Units (CDUs): Manufacturing advanced pumping mechanisms and fluid loop manifolds capable of circulating dielectric fluids without leakage risk across 100-kilowatt-plus enterprise racks.
- Advanced Power Topologies: As single rack demands escalate toward 120kW and beyond, legacy alternating-current (AC) distribution is yielding to direct 48V-to-point-of-load direct-current (DC) power shelves. Hon Hai has internalized the production of these high-efficiency power supplies, capturing margin previously surrendered to specialty power electronic vendors.
- High-Speed Interconnect Optimization: With petabyte-scale data throughput traversing compute nodes every millisecond, systemic network integrity is paramount. Hon Hai’s components division produces the internal backplanes, optical transceivers, and high-density copper cabling required to maintain low-latency connectivity within the cluster.
This vertical integration directly increases the company's content per box. In a standard enterprise server, an ODM might capture a low-single-digit percentage of total bill-of-materials (BOM) value. In a complex, liquid-cooled, multi-million-dollar AI computing rack, Hon Hai’s proprietary component share swells dramatically, amplifying return on invested capital (ROIC) and elevating the firm's overall valuation multiples.
Macro Implications: Who Wins, Who Loses in the Infrastructure Super Cycle?
Hon Hai’s blow-out earnings and mid-summer acceleration crystallize a clear set of macro winners and losers across the global technology and institutional investment landscape.
The Beneficiaries
- Tier-1 Hyperscale Infrastructure Suppliers: Hon Hai’s results corroborate guidance from upstream semiconductor giants like TSMC, Nvidia, and Broadcom. The pipeline of sustained infrastructure investment is locked in for the foreseeable future.
- Cooling & Thermal Specialists: The industrialization of liquid-cooled racks signals an enduring, multi-year upgrade cycle for data center facilities globally, validating massive capital allocations toward precision engineering and thermal fluid suppliers.
- Institutional Equity Holders in "Value Hardware": Traditional ODMs trading at mid-tier price-to-earnings (P/E) multiples of 10x to 14x are undergoing an aggressive multiple re-rating toward 18x to 22x as institutional allocators recognize the sustained durability of AI-driven operating cash flows.
The Vulnerable Segments
- Pure-Play Legacy PC/Smartphone Component Makers: As enterprise budgets disproportionately channel cash into server compute racks, consumer edge device upgrades remain uninspired. Component manufacturers reliant exclusively on consumer hardware volume run the risk of continued margin stagnation.
- Sub-Scale ODMs: The immense working capital requirements needed to build multi-million-dollar racks—purchasing billions of dollars worth of cutting-edge GPUs and high-spec memories ahead of invoicing—creates an insurpassable barrier to entry. Smaller tier-two assemblers are effectively priced out of tier-one hyperscale tenders due to balance sheet constraints.
Frequently Asked Questions (People Also Ask)
Why is Hon Hai considered the premier barometer for global AI computing demand?
Hon Hai Precision Industry (Foxconn) controls the largest manufacturing and assembly share of enterprise server infrastructure globally. Because it directly interfaces with chipmakers like Nvidia and end-market hyperscalers like Microsoft, Amazon, Google, and Meta, its revenue trends and order backlogs provide unfiltered, real-time insight into actual deployment rates and capital spending trends across the AI hardware supply chain.
What drove the dramatic 54% year-over-year revenue increase in July?
The July expansion was driven by a combination of two critical factors: the easing of severe upstream packaging constraints (notably TSMC’s CoWoS packaging) which unlocked mass production lines, and the rapid ramp-up of next-generation, high-density AI rack architecture shipments. This allowed Hon Hai to fulfill an immense backlog of multi-node enterprise compute clusters.
How does AI server manufacturing improve Hon Hai’s operating margins compared to consumer electronics?
Traditional smartphone or PC assembly offers thin margins because ODMs primarily perform labor-intensive final assembly of customer-supplied parts. In AI supercomputing clusters, Hon Hai vertically integrates proprietary components—including liquid cooling cold plates, manifold distribution systems, high-efficiency power shelves, and high-speed copper/optical connectors. This higher content-per-rack significantly elevates gross and operating margins relative to legacy consumer assembly.
Are there major risks to Hon Hai’s AI growth trajectory heading into late 2026?
The primary systemic risks include potential geopolitical volatility surrounding cross-strait supply chains, prospective enterprise capex digestion if end-market software return on investment (ROI) stalls, and localized power grid bottlenecks in North America and Europe that could delay new data center activations and compute installations.
Strategic Outlook: The Milestones That Matter Next
As Hon Hai heads into the second half of the fiscal year, institutional eyes will pivot toward the execution of its international footprint diversification and the structural longevity of Big Tech’s capex runway.
The company’s capital investments into massive server production complexes in North America (including Mexico and the United States) are nearing peak utilization. This localized footprint offers significant risk mitigation against escalating cross-strait tensions and ensures streamlined logistics for North American hyperscalers facing strict data center delivery deadlines.
Wall Street will closely monitor three specific operational catalysts over the next two quarters: first, the pace of high-margin liquid cooling adoption across enterprise customers; second, whether sovereign AI buildouts in the Middle East, Japan, and Western Europe compensate for any potential moderation in US corporate hyperscale growth; and third, the sustained expansion of operating cash flows relative to heavy inventory working-capital demands.
For now, Hon Hai’s blistering 35% profit surge and 54% July revenue jump have silenced skeptics. The AI infrastructure super cycle is not a speculative narrative—it is an unprecedented capital expenditure wave, and Hon Hai has cemented its position at its absolute operational center.