Executive Takeaways
- Valuation Compression Creates Entry Points: Recent market rotations and "anything-but-AI" sentiment shifts have suppressed multiples across top-tier large-cap technology equities, providing institutional investors with an attractive capital allocation window.
- Infrastructure Scaling & Backlog Surges: Enterprise demand remains decoupled from consumer hype, underscored by historic order book expansions—exemplified by massive corporate backlogs exceeding half a trillion dollars across foundational hardware and cloud compute architectures.
- Monetization Moves Downstream: Capital expenditure is rapidly transitioning from pure R&D and hardware acquisition toward high-margin enterprise SaaS integration, cloud infrastructure scalability, and direct operational ROI.
The artificial intelligence investment thesis has officially graduated from speculative euphoria to hard economic reality. Over the past several quarters, Wall Street has grappled with a volatile macro-economic backdrop, fluctuating interest rate expectations, and bouts of sector-specific fatigue. Yet, beneath the surface of day-to-day market volatility, a structural transformation is unfolding. According to recent comprehensive equity research published by Morningstar editors and senior analysts—including insights spearheaded by Tori Brovet—market corrections and temporary contractions in sentiment have created generational entry points for discerning investors targeting the best AI stocks to buy now.
For institutional allocators and private wealth managers alike, the core question is no longer whether generative AI will reshape global commerce, but rather which corporate balance sheets, cloud compute architectures, and proprietary ecosystems possess the structural moats required to capture sustainable, multi-year compounding cash flows. As enterprise ROI hurdles tighten and boards demand measurable productivity gains from software deployment, the market is separating foundational infrastructure monopolies from consumer-facing novelty plays.
The Catalytic Shift: Backlogs, Infrastructure Scaling, and Market Sentiment
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
To understand the current positioning of the AI equity landscape, one must analyze the unprecedented velocity of enterprise capital commitments. Market sentiment underwent a violent recalibration when enterprise infrastructure bellwethers revealed staggering forward-looking metrics, most notably highlighted by corporate disclosures showing nearly half a trillion dollars in cumulative backlog orders. This immense pipeline signals that corporate IT budgets are no longer dabbling in experimental proofs-of-concept; they are executing massive, multi-year digital transformations.
Concurrently, the broader market has periodically swung between over-enthusiasm and unwarranted skepticism regarding AI monetization timelines. This cyclical push-and-pull has driven down valuation multiples on several elite tier-1 equities. Analysts note that these temporary valuation compressions offer an optimal risk-mitigation framework for long-term investors looking to build concentrated or diversified exposure without paying peak-bubble premiums.
Decoding the Core Beneficiaries: From Silicon to Cloud Compute
The AI value chain is stratified into distinct operational layers: semiconductor manufacturing and hardware acceleration, hyperscale cloud infrastructure, and software applications. Each layer presents unique risk-reward profiles:
- Semiconductor & Hardware Acceleration: Companies commanding dominant market shares in graphics processing units (GPUs), custom application-specific integrated circuits (ASICs), and high-bandwidth memory continue to dictate industry margins. Their pricing power remains exceptionally resilient due to supply chain complexities and astronomical barriers to entry.
- Hyperscale Cloud Providers: Giants operating globally distributed data center footprints are uniquely positioned to rent compute capacity at scale. They benefit from massive free cash flow generation that funds both aggressive internal R&D and strategic acquisitions.
- Diversified Enterprise Software Monopolies: Firms embedding machine learning models directly into legacy enterprise resource planning (ERP), customer relationship management (CRM), and workplace productivity suites are seeing rapid acceleration in annual recurring revenue (ARR).
Verified Data & Metrics Breakdown
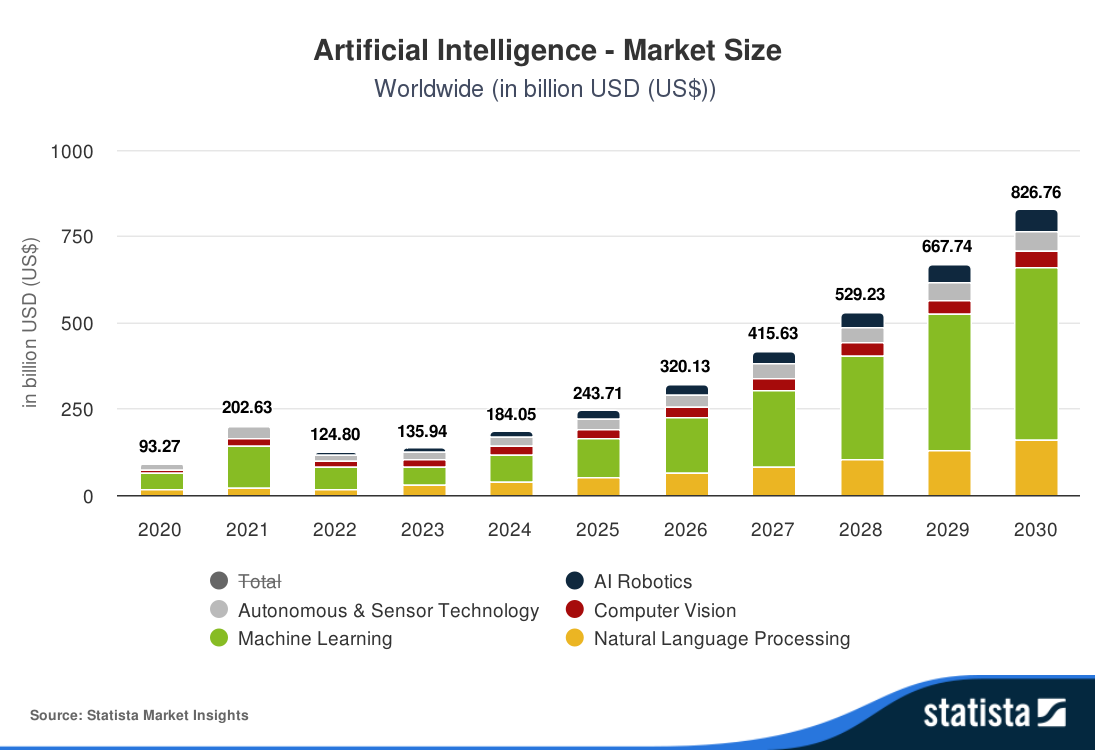
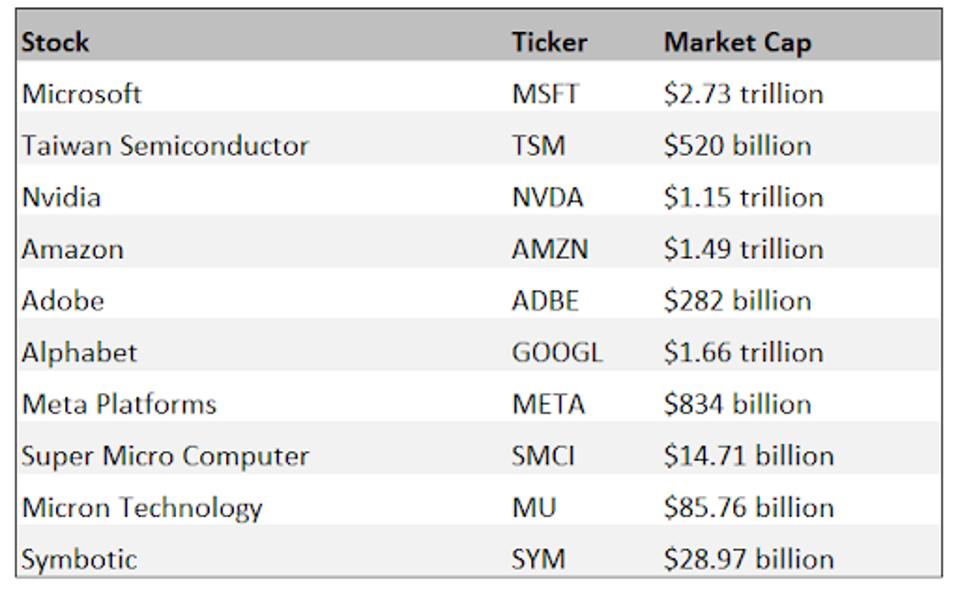
A rigorous comparative analysis of the leading artificial intelligence equities requires evaluating critical balance sheet strength, infrastructure scaling capabilities, and market positioning:
| Company Name | Ticker | Primary AI Value Driver | Competitive Moat | Market Position |
|---|---|---|---|---|
| Nvidia Corporation | NVDA | Hardware Acceleration & CUDA Software Ecosystem | Insurmountable hardware-software co-design lock-in | Dominant Infrastructure Supplier |
| Microsoft Corporation | MSFT | Azure Cloud Compute & Copilot Integration | Deep enterprise relationships & exclusive AI partnerships | Enterprise Software Leader |
| Amazon.com, Inc. | AMZN | AWS Machine Learning Services & Custom Silicon | Global cloud infrastructure scale & logistics integration | Cloud & E-commerce Giant |
| Alphabet Inc. | GOOGL | Gemini Models, TPU Architecture & Search Monetization | Proprietary data scale & advanced AI research talent | Data & Search Apex Predator |
| Taiwan Semiconductor Manufacturing | TSM | Advanced Node Semiconductor Foundry Services | Monopolistic mastery of leading-edge wafer fabrication | Essential Manufacturing Gatekeeper |
Industry & Market Implications: Winners, Losers, and Economic Repercussions
The macroeconomic ramifications of the artificial intelligence super-cycle extend far beyond the technology sector. As capital allocation aggressively funnels into data center construction, high-voltage electrical grid enhancements, and cooling infrastructure, traditional industrial, energy, and real estate sectors are experiencing secondary and tertiary tailwinds.
The Winners: Enterprise software firms that successfully transition from seat-based pricing models to consumption- and value-based AI monetization are capturing expanding operating margins. Furthermore, specialized utility providers and nuclear energy operators positioned near major data center hubs are experiencing unprecedented structural demand.
The Laggards & Vulnerable Segments: Conversely, legacy IT service providers and software companies slow to integrate native generative capabilities into their product roadmaps face severe obsolescence risks. Companies burdened by high debt-to-equity ratios that fail to demonstrate clear operational efficiency gains from AI adoption are being severely penalized by institutional credit markets.
Frequently Asked Questions (People Also Ask)
1. Why are current market pullbacks considered attractive entry points for AI stocks?
Periodic sector rotations and transient "anything-but-AI" market sentiments have caused valuation multiples for elite technology companies to compress from historical highs. Because enterprise demand, robust balance sheets, and multi-year backlogs remain exceptionally strong, these price corrections allow institutional and retail investors to acquire foundational assets at more reasonable risk-adjusted valuations.
2. How do hardware providers like Nvidia differ from software giants like Microsoft in the AI value chain?
Hardware providers (such as Nvidia and TSMC) operate at the infrastructure foundation, supplying the raw computational power, advanced silicon chips, and manufacturing capacity required to train and run complex models. Software giants (such as Microsoft, Alphabet, and Amazon) operate higher up the stack, utilizing that hardware to build cloud infrastructure, proprietary models, and enterprise applications that directly monetize end-user productivity.
3. What role do corporate backlogs play in evaluating the financial health of AI equities?
Corporate backlogs represent contracted, future revenue that has not yet been formally recognized on the income statement. In the context of AI infrastructure and cloud computing, massive order backlogs provide exceptional forward visibility, reassuring investors that capital expenditures by enterprise clients will translate into sustained cash flow growth over the medium to long term.
4. How should investors manage regulatory and compliance risks when building an AI stock portfolio?
Regulatory scrutiny regarding data privacy, antitrust concerns, intellectual property rights, and cross-border semiconductor trade restrictions represents a persistent risk factor. Investors can mitigate these risks by favoring geographically diversified large-cap enterprises with robust legal compliance frameworks, substantial balance sheet reserves, and diversified revenue streams that are not overly reliant on a single product or jurisdiction.
Future Outlook & Strategic Milestones to Watch
Looking ahead over the next 12 to 24 months, the trajectory of the AI equity market will be dictated by several pivotal operational milestones. First, market observers must monitor enterprise capital expenditure ROI disclosures: corporate boards will increasingly demand tangible proof that multi-million dollar AI deployments are compressing operational expenditures and accelerating revenue growth.
Second, supply chain bottlenecks in advanced packaging, high-bandwidth memory, and electrical grid power availability will test the production ceilings of hardware manufacturers. Companies that successfully navigate these physical constraints while expanding operating margins will solidify their market dominance.
Ultimately, while market sentiment will inevitably experience short-term oscillations, the structural bedrock of the artificial intelligence economy remains intact. For investors adhering to disciplined capital allocation strategies, focusing on companies with unassailable technological moats, immense cash generation, and massive order visibility offers the most reliable path to long-term capital appreciation in this transformative era.