Executive Takeaways
- Holding Pattern: US benchmark indices remain tightly consolidated near record highs as institutional desks adjust capital allocation strategies ahead of the Federal Open Market Committee (FOMC) pronouncement.
- Valuation Multiples Under Scrutiny: Elevated equity valuations, particularly within large-cap technology and growth sectors, face immediate repricing risks depending on the central bank’s forward guidance and terminal rate projections.
- Liquidity & Risk Mitigation: Corporate treasuries and institutional asset managers are actively deploying hedging mechanisms, prioritizing risk mitigation, and reevaluating debt refinancing schedules.
- Macroeconomic Divergence: Persistent labor market resilience set against moderating inflationary prints complicates the Federal Reserve's path toward optimizing monetary policy without triggering systemic shocks.
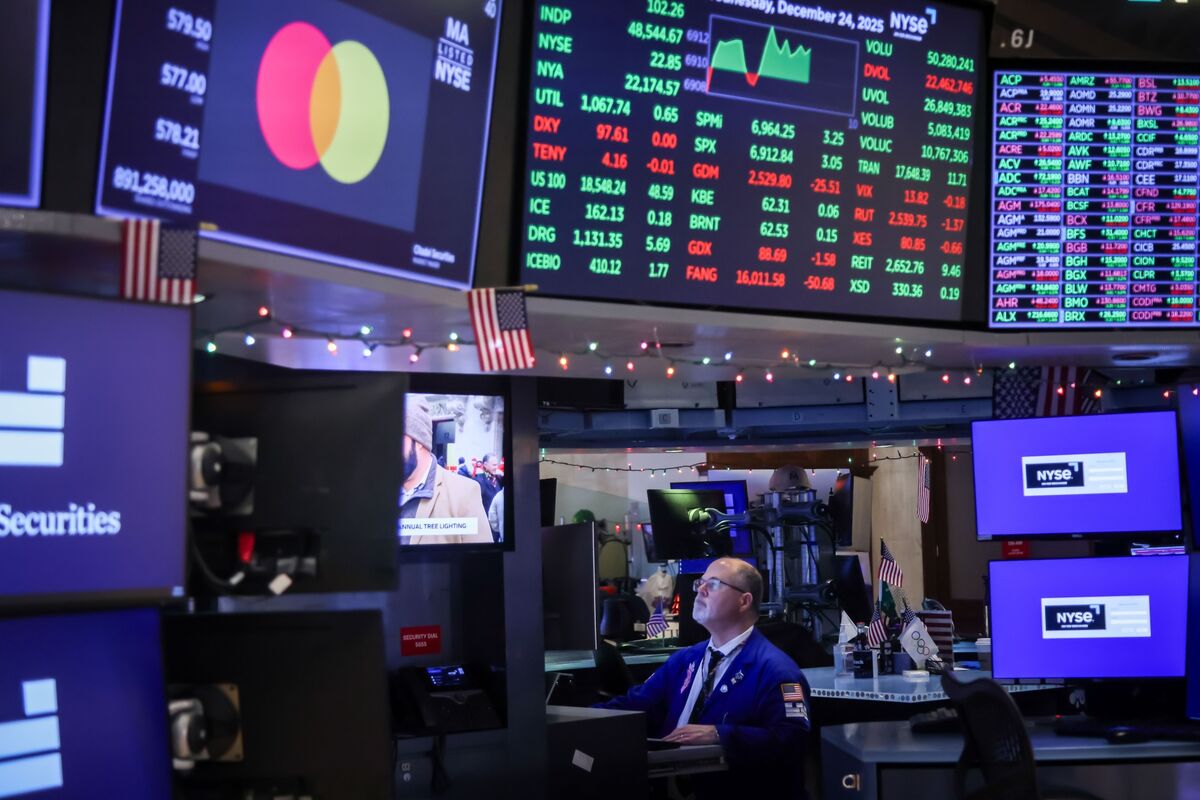
As the countdown to the Federal Reserve’s definitive monetary policy announcement enters its final hours, Wall Street trading floors present an image of calm exterior composure masking intense underlying calculations. Major US stock indices—including the S&P 500, the Nasdaq Composite, and the Dow Jones Industrial Average—are holding remarkably steady. Yet, beneath this placid surface, institutional investors, corporate balance sheet architects, and macroeconomic strategists are executing aggressive portfolio realignments. The central question dominating trading desks from lower Manhattan to Mayfair is not merely whether the central bank will adjust its benchmark federal funds rate, but how aggressively Chairman Jerome Powell will signal the trajectory of monetary easing for the remainder of the fiscal year.
The current market equilibrium reflects a delicate standoff. On one side, sustained corporate earnings resilience, robust cloud compute architecture expenditures, and surging enterprise artificial intelligence deployment have kept valuation multiples elevated. On the other side, the structural cost of capital remains at multi-decade highs, forcing corporations to fundamentally rethink capital allocation, infrastructure scalability, and debt service coverage ratios. As WAVY.com and primary wire feeds indicate, market participants are pricing in various policy paths, ranging from a conservative stance to a more accommodative pivot designed to protect broader economic growth.
The Catalytic Anatomy of the Current Market Hold
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
To understand why US equities are hovering in a state of suspended animation, one must examine the convergence of macroeconomic indicators that have defined the preceding quarter. Inflation, while retreating significantly from its post-pandemic peaks, has proven sticky within core service sectors. Concurrently, labor market prints continue to defy pessimistic forecasts, demonstrating persistent vitality that complicates the Federal Reserve’s dual mandate of price stability and maximum employment.
Institutional risk committees are currently reviewing comprehensive risk mitigation frameworks. For months, corporate financial officers have navigated an environment where traditional borrowing costs dictate operational expansion. Enterprises that successfully locked in low-coupon fixed-rate debt during the 2020–2021 window have largely insulated their operational margins. However, mid-cap firms and enterprises facing near-term debt maturities are encountering a starkly different reality, where refinancing mandates severely impact net income margins and enterprise ROI.
Equity market behavior over the past week underscores a profound wait-and-see mentality. Trading volumes in derivative markets have spiked, specifically in options contracts tied to the Cboe Volatility Index (VIX), signaling that institutional accounts are purchasing downside protection even as spot prices remain range-bound. This structural dichotomy—passive index stability paired with aggressive hedging activity—reveals an underlying anxiety regarding the FOMC’s updated economic projections, commonly known as the "dot plot."
Verified Data & Metrics Breakdown
A comparative analysis of key macroeconomic indicators and market valuations highlights the pressures currently influencing Federal Reserve deliberations and institutional portfolio management:
| Economic / Market Indicator | Current Status / Level | Historical Context (12-Mo. Average) | Implication for Federal Reserve Policy |
|---|---|---|---|
| Federal Funds Target Rate | 5.25% – 5.50% | Maintained flat across past 6 meetings | Restrictive stance required to anchor core inflation expectations. |
| S&P 500 Forward P/E Ratio | ~21.5x | 19.2x | Elevated multiples leave little margin for disappointment in forward guidance. |
| Core PCE Inflation | 2.6% YoY | 3.4% YoY | Approaching the 2% target, justifying discussions of policy normalization. |
| 10-Year US Treasury Yield | ~4.28% | 4.15% | Reflects persistent bond market recalibration of long-term neutral rates. |
Industry & Market Implications: Winners, Losers, and Capital Flows
Monetary policy shifts never impact all market segments equally. As institutional capital managers prepare for the Fed's imminent decision, distinct sectors stand to gain or lose based on the anticipated trajectory of interest rates and market liquidity.
The Beneficiaries: Sectors Poised for Outperformance
- Mega-Cap Technology & Growth: While sensitive to discount rates, companies with pristine balance sheets, massive cash reserves, and secular tailwinds in enterprise software and cloud infrastructure stand to benefit from a lower cost of capital, which enhances long-term discounted cash flow (DCF) valuations.
- Financial Services & Private Credit: Commercial banks with stable deposit bases and private credit funds navigating liquidity constraints will find renewed clarity on loan-loss provisioning and deal-flow origination pipelines once rate trajectories are formalized.
- Utilities and Real Estate Investment Trusts (REITs): High-dividend-paying sectors, which have suffered relative capital outflows due to attractive short-term Treasury yields, are expected to experience renewed institutional accumulation as yield curves normalize.
The Vulnerabilities: Headwinds for Leveraged Entities
- Small-Cap Equities (Russell 2000): Smaller enterprises reliant on floating-rate debt and regional banking lending facilities remain acutely vulnerable if the Federal Reserve signals "higher-for-longer" parameters, squeezing operating margins and restricting expansion capital.
- Highly Leveraged Cyclicals: Consumer discretionary and industrial sub-sectors with heavy debt burdens will face compressed valuation multiples if macroeconomic momentum slows concurrently with restrictive monetary policy.
Frequently Asked Questions (People Also Ask)
Why are US stocks holding steady right before a major Federal Reserve announcement?
Equities are maintaining stability due to a balance between resilient corporate earnings and cautious positioning by institutional investors. Most market participants have already priced in a baseline scenario, choosing to execute risk-mitigation strategies in options and fixed-income markets rather than aggressively liquidating equity positions before official guidance is released.
How do interest rate decisions directly impact enterprise valuation multiples?
Interest rates determine the discount rate applied to future corporate cash flows in valuation models. When rates remain elevated, future earnings are discounted more heavily, compressing price-to-earnings (P/E) multiples—particularly for growth and technology companies whose projected earnings are concentrated further out in the future.
What is the significance of the Federal Reserve’s "dot plot" for market liquidity?
The dot plot outlines individual FOMC members' expectations for the federal funds rate over the medium and long term. Institutional asset allocators rely on this projection to calibrate portfolio duration, assess corporate debt refinancing risks, and determine overall market liquidity allocations across global asset classes.
Which sectors are most sensitive to shifts in the federal funds rate?
Capital-intensive industries, commercial real estate, regional banking, and small-cap companies with floating-rate debt obligations are exceptionally sensitive. Conversely, cash-rich mega-cap technology firms and defensive sectors exhibit lower relative volatility to intermediate rate fluctuations.
Future Outlook: What Comes Next and Key Milestones to Watch
As the Federal Reserve prepares to publish its statement and Chairman Powell steps up to the podium for his post-meeting press conference, the immediate aftermath will likely trigger a sharp wave of market price discovery. Algorithmic execution engines and human portfolio managers alike will parse every nuance of the central bank's language, searching for shifts in phrasing regarding labor market slack, inflation persistence, and balance sheet normalization.
Looking past the immediate headline risk, market strategists are already shifting focus to subsequent macroeconomic milestones. Key data releases—including upcoming employment reports, monthly Consumer Price Index (CPI) prints, and corporate guidance reports for the upcoming quarter—will test the validity of the Fed’s policy stance. For institutional investors, maintaining rigorous regulatory compliance, enforcing disciplined capital allocation, and prioritizing enterprise risk mitigation will remain paramount as financial markets navigate the next phase of the economic cycle.