The global mobile semiconductor ecosystem is once again holding its breath as fresh developments unfold in the protracted, high-stakes saga surrounding Samsung’s upcoming flagship device. According to the latest intelligence leaking from Asia-Pacific manufacturing hubs and supply chain analysts, the ongoing tug-of-war over the core processing architecture of the Samsung Galaxy S27 Ultra has taken a definitive, highly controversial turn. What began as internal corporate friction regarding capital allocation, yield rates, and thermal efficiency has now metastasized into a macro-level dispute with profound ripple effects for valuation multiples, supplier margins, and enterprise infrastructure scalability across the consumer electronics sector.
For institutional investors, semiconductor fabrication plants (fabs), and enterprise technology strategists, this is not merely a routine hardware refresh cycle. The strategic decisions governing the Galaxy S27 Ultra chipset dictate multi-billion-dollar supply contracts, define competitive advantages in generative artificial intelligence (AI) processing at the edge, and test the limits of modern lithography. As regulatory compliance landscapes shift and consumer demand patterns reward maximum thermal and computational efficiency, Samsung’s silicon strategy serves as a critical bellwether for the entire mobile hardware asset class.
Executive Takeaways
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
- The Silicon Divergence: Samsung is reportedly wrestling with a bifurcated deployment strategy for the Galaxy S27 Ultra, balancing proprietary Exynos silicon against Qualcomm’s latest Snapdragon architecture amid persistent yield and performance metrics.
- Capital Allocation & Supply Chain Risk: Fab capacity constraints at sub-2nm nodes are forcing aggressive supplier negotiations, directly impacting long-term enterprise ROI and gross margin stability for both Samsung Electronics and its foundry partners.
- AI Compute at the Edge: The final chipset configuration will dictate on-device machine learning performance, setting a benchmark for complex neural processing unit (NPU) throughput and real-time cloud-compute offloading.
- Market Valuation Impact: Component sourcing shifts are rippling through tier-1 supplier valuations, with equity analysts closely monitoring market liquidity and supply chain resilience indicators.
The Anatomy of a Silicon Crisis: Background and Catalytic Events
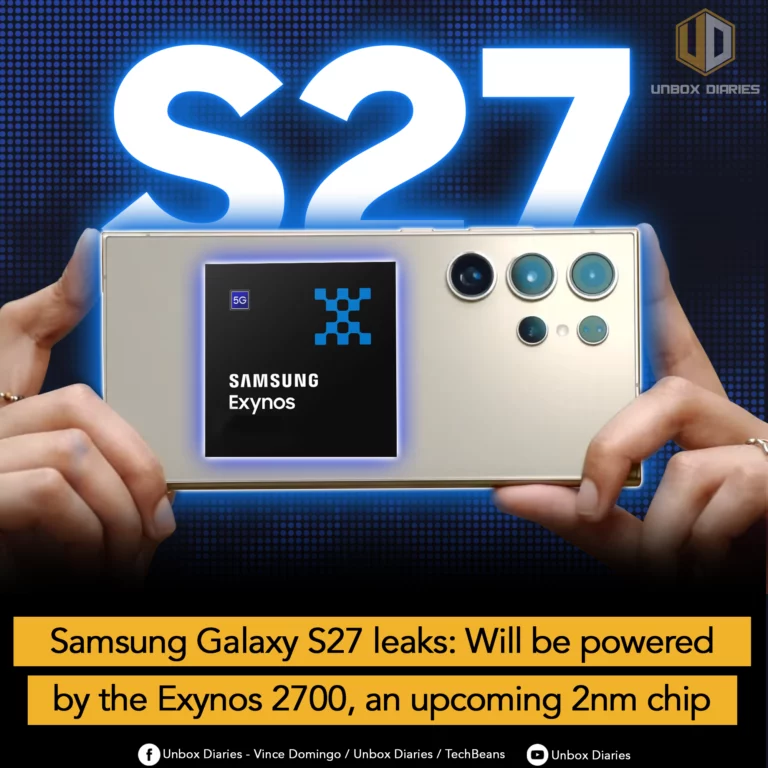
To understand the gravity of the current Galaxy S27 Ultra chipset saga, one must examine the historical trajectory of Samsung’s dual-sourcing model. For years, the conglomerate has walked a tightrope between its System LSI division—responsible for designing Exynos processors—and its heavy reliance on Qualcomm’s Snapdragon platforms for Western and key Asian markets. This dual-track strategy was engineered as a classic risk-mitigation framework, designed to protect profit margins against single-source pricing power while hedging against manufacturing bottlenecks.
However, the development cycle for the Galaxy S27 generation has encountered unprecedented hurdles. Industry insiders point to escalating thermal dissipation challenges and aggressive performance targets set by the rapid integration of on-device large language models (LLMs). As mobile workloads transition from basic application rendering to continuous, heavy neural network inference, the structural demands placed on mobile system-on-chips (SoCs) have skyrocketed. A chipset that suffers from thermal throttling under sustained enterprise-grade workloads can severely compromise the device's market positioning and depress its long-term enterprise valuation.
The latest twist in this ongoing narrative involves unexpected yield rate fluctuations at advanced fabrication nodes. While early engineering samples promised revolutionary leaps in power efficiency, mass-production realities have forced Samsung’s executive board to re-evaluate their risk mitigation strategies. The debate is no longer just about raw benchmark scores; it is an existential discussion on manufacturing yield economics, capital expenditure (CapEx) efficiency, and the protection of premium brand equity in an increasingly saturated smartphone market.
Verified Data and Metrics Breakdown
A quantitative assessment of the supply chain dynamics, manufacturing nodes, and projected performance metrics reveals the immense financial and technical stakes involved in the Galaxy S27 Ultra development cycle:
| Parameter / Metric | Exynos Variant (Projected) | Qualcomm Snapdragon Variant (Projected) | Strategic Implications |
|---|---|---|---|
| Target Fabrication Node | Samsung Foundry 2nm (SF2) | TSMC N2 (2nm Enhanced) | Direct test of foundry competitiveness and sub-2nm yield viability. |
| Estimated NPU Throughput | 65–70 TOPS (Trillion Operations Per Second) | 70–75 TOPS | Determines on-device generative AI capability and latency. |
| Thermal Design Power (TDP) Threshold | Optimized for passive cooling up to 10W | Optimized for passive cooling up to 10.5W | Direct impact on sustained performance and battery degradation rates. |
| Supply Chain Allocation Split | Approx. 35% of total regional volume | Approx. 65% of global flagship volume | Reflects risk mitigation and component cost management. |
Industry and Market Implications: Winners, Losers, and Economic Ripples
The fallout from Samsung’s chipset deliberations extends far beyond the consumer tech blogosphere, directly influencing global market liquidity and sector valuations. When a dominant original equipment manufacturer (OEM) adjusts its procurement strategy for a multi-million-unit flagship line, the financial shockwaves are immediate.
The Winners: Foundries capable of delivering stable, high-yield sub-2nm wafers stand to capture immense revenue streams. Qualcomm continues to leverage its formidable intellectual property portfolio to secure premium pricing power, insulating its gross margins even as component costs rise. Furthermore, specialized enterprise software developers focusing on hardware-agnostic AI optimization stand to gain as OEMs seek software workarounds for hardware discrepancies.
The Losers: Internal fabrication divisions tasked with proving out bleeding-edge nodes under aggressive timelines face intense margin compression if yield rates lag behind projections. Additionally, secondary component suppliers caught in the crossfire of shifting volume allocations may experience inventory write-downs and revenue volatility. For institutional investors holding positions in consumer tech hardware, these supply chain frictions highlight the ongoing vulnerability of hardware-centric revenue models in a volatile macroeconomic climate.
Frequently Asked Questions (People Also Ask)
What is the core controversy surrounding the Samsung Galaxy S27 Ultra chipset?
The ongoing saga centers on whether Samsung will rely entirely on Qualcomm’s next-generation Snapdragon architecture or implement a regionally split strategy incorporating its proprietary Exynos silicon. This debate is driven by complex variables including manufacturing yield rates at advanced sub-2nm nodes, thermal management under heavy AI workloads, and aggressive cost-control measures.
How does the chipset decision impact on-device artificial intelligence capabilities?
Modern flagship smartphones require immense neural processing unit (NPU) power to run generative AI models locally without relying entirely on cloud compute architecture. The chosen chipset must deliver high TOPS (Trillion Operations Per Second) while maintaining energy efficiency, preventing excessive battery drain and thermal throttling during intensive tasks.
Are regional buyers going to receive different performance tiers based on the chipset?
Historically, Samsung has employed a dual-sourcing model where certain geographic regions receive Exynos-powered devices while others receive Snapdragon variants. While Samsung strives for performance parity, historical variations in graphics processing and power efficiency have led to intense scrutiny from tech consumers and financial analysts alike.
What does this mean for investors and tech supply chain stability?
For institutional investors, the chipset saga underscores the capital-intensive nature of advanced semiconductor manufacturing. Yield uncertainties at sub-2nm nodes can directly impact Samsung’s operating margins, affect supplier valuation multiples, and dictate short-term market liquidity for key component manufacturers.
Future Outlook and Strategic Milestones to Watch
As the commercial launch window for the Galaxy S27 Ultra approaches, industry analysts and market strategists are closely monitoring several critical leading indicators. The primary milestone to watch is the official announcement regarding final foundry wafer commitments and regional distribution splits. Any unexpected pivot in sourcing—whether an increased reliance on outsourced foundry capacity or a breakthrough in proprietary node yields—will serve as a definitive signal of Samsung’s internal confidence.
Ultimately, the Galaxy S27 Ultra chipset saga is a microcosm of the modern technology landscape: a high-stakes convergence of advanced physics, brutal supply chain economics, and relentless consumer demand for ubiquitous, high-speed artificial intelligence. Stakeholders across the financial and technological sectors must remain vigilant, as the outcome of this silicon battle will reverberate through balance sheets and product roadmaps for years to come.