Executive Takeaways
- The Core Catalyst: Wall Street enters a high-stakes trading week capped by Wednesday’s crucial Consumer Price Index (CPI) release, which threatens to derail a relentless technology-driven equity rally.
- Valuation Pressures: US stock indices sit at record highs, driven by aggressive capital allocation into AI infrastructure scalability and cloud compute architecture, leaving little margin for error if interest rate expectations sour.
- Macroeconomic Crosscurrents: Surging energy markets, highlighted by West Texas Intermediate (WTI) crude hovering near $83.38 per barrel alongside persistent commodity pressures (such as agricultural inputs like eggs), complicate the Federal Reserve's path to monetary easing.
- Risk Mitigation: Institutional portfolio managers are aggressively reevaluating risk exposure, hedging against sudden duration shocks, and recalculating equity valuation multiples ahead of the critical mid-week inflation data.
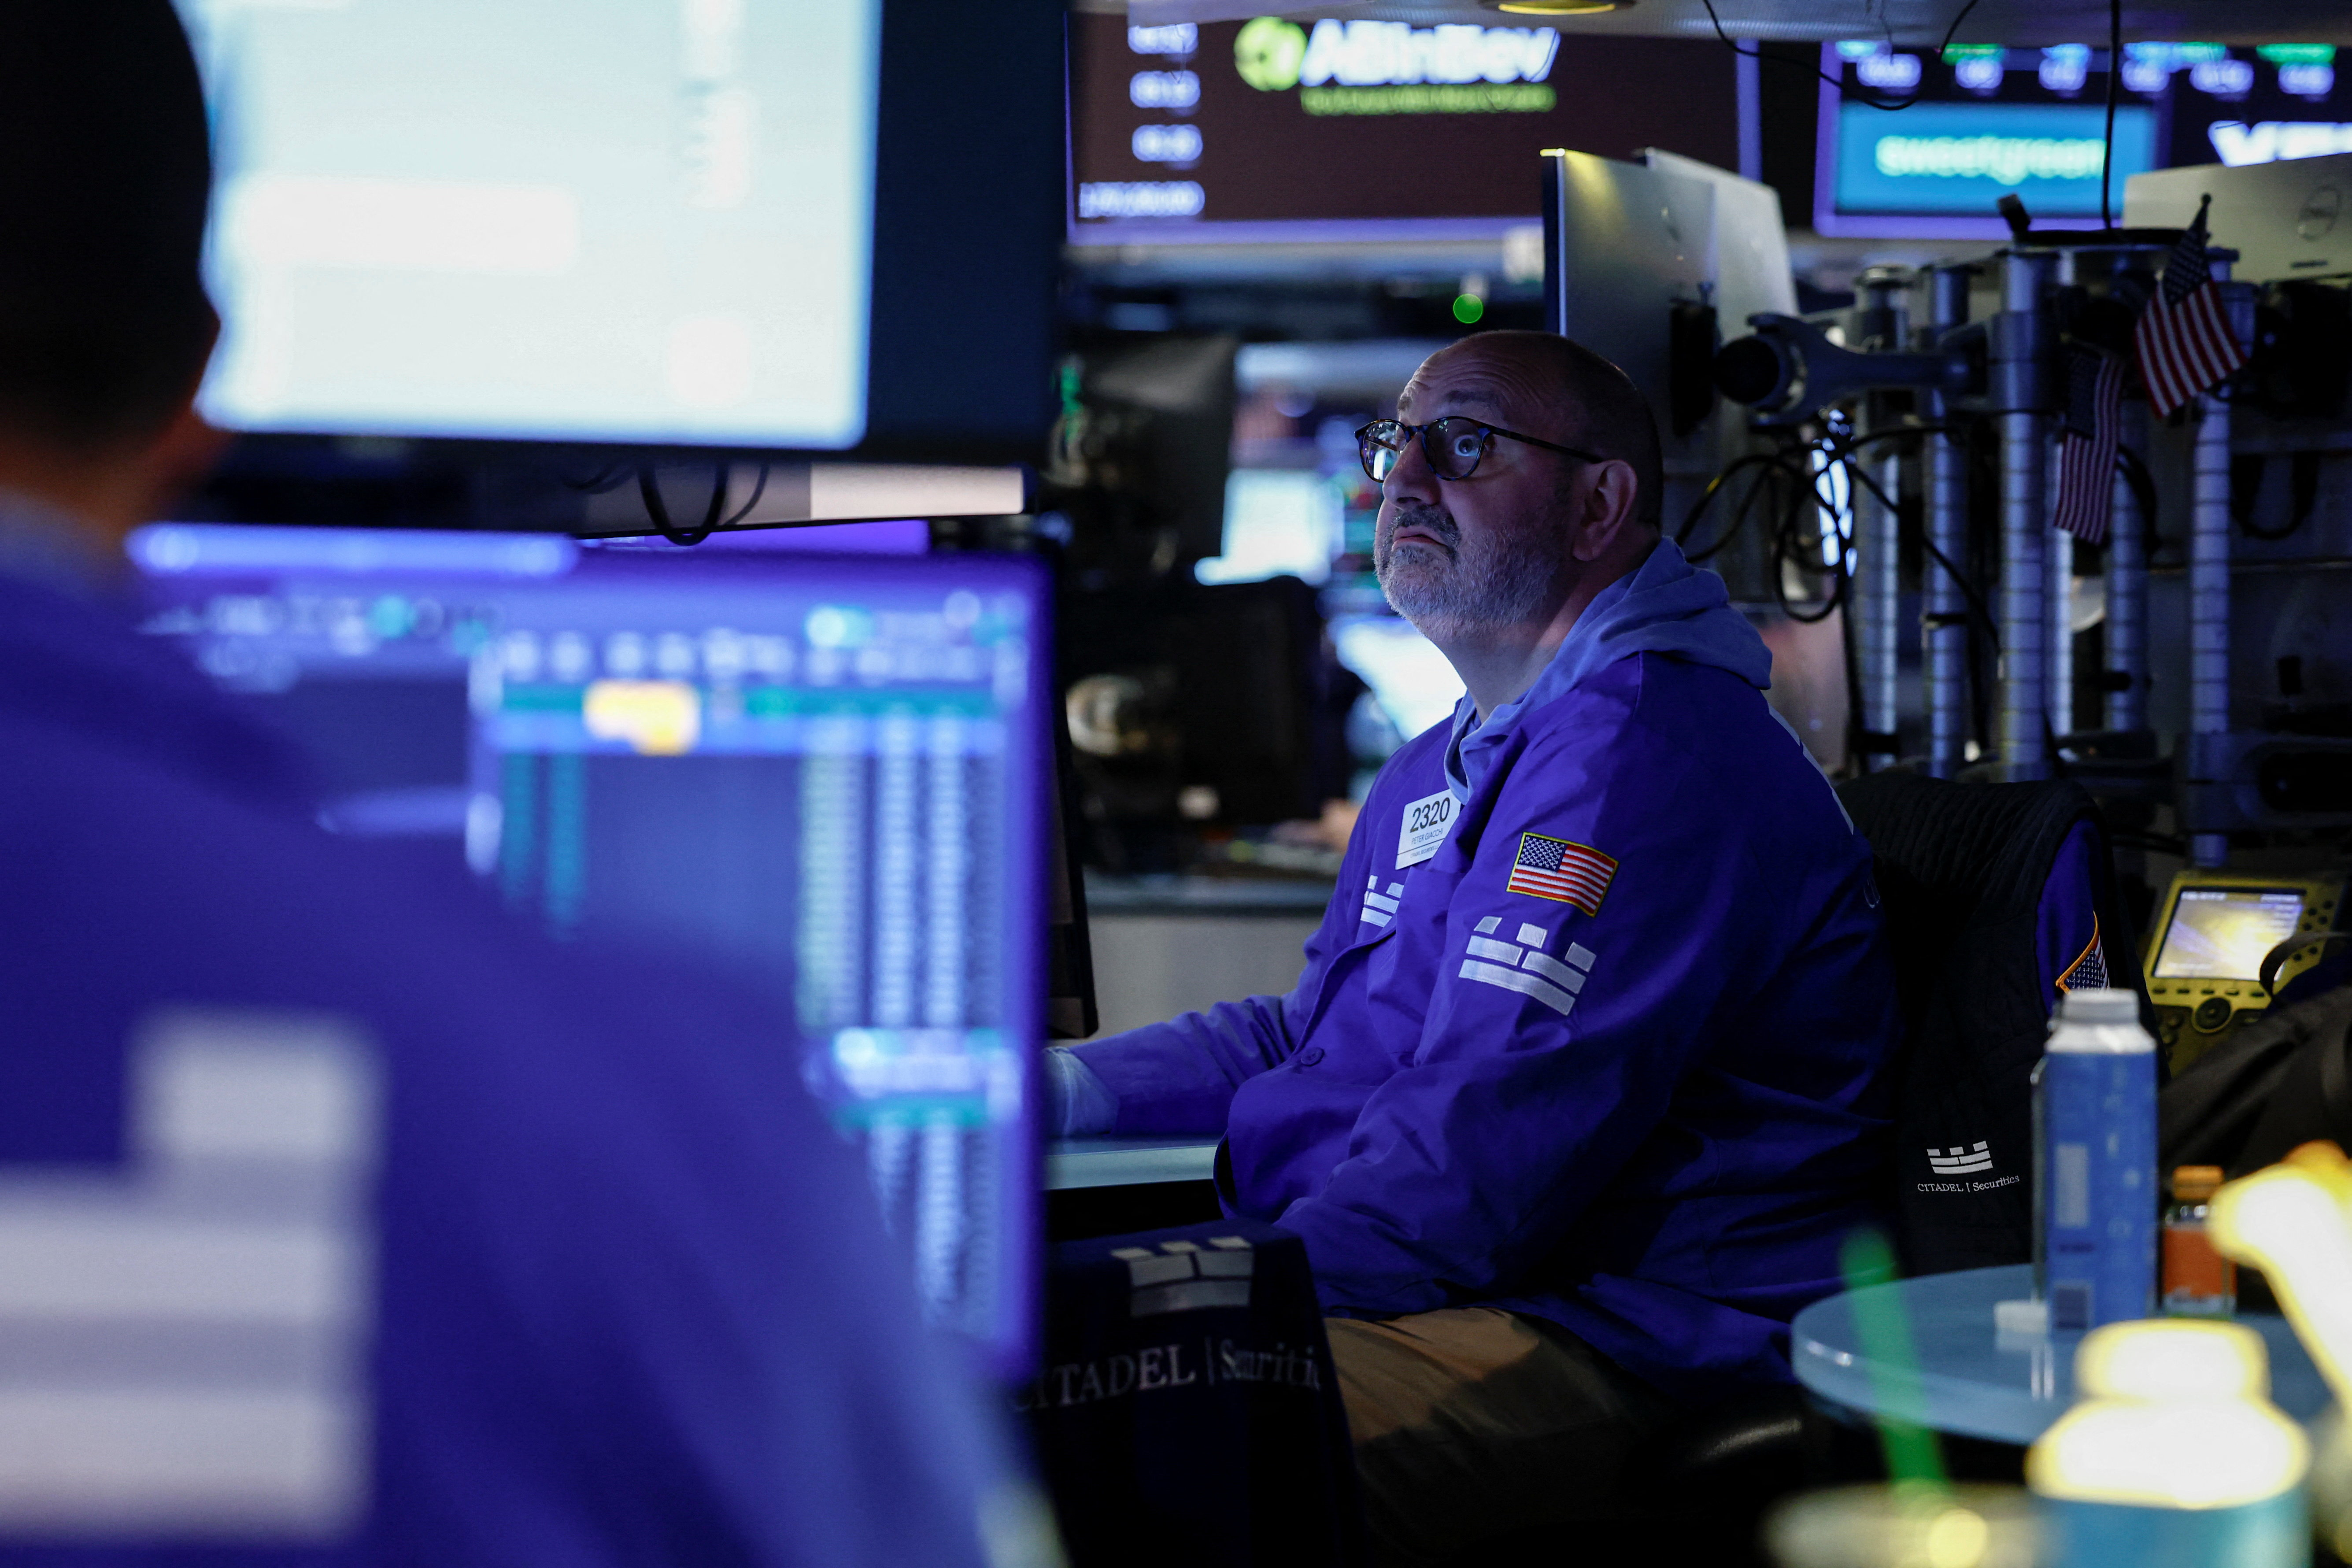
NEW YORK — As the trading bell rings to open a pivotal mid-August session, Wall Street finds itself suspended in a delicate equilibrium. Propelled by an aggressive, technology-led rally, major U.S. stock indices continue to test uncharted territory, scaling record-setting heights that defy lingering macroeconomic anxieties. Yet, beneath the veneer of market euphoria lies an acute vulnerability. This Wednesday’s release of the Consumer Price Index (CPI) report stands as the ultimate stress test for this bull market, threatening to force a brutal reassessment of Federal Reserve rate views, Treasury yields, and corporate valuation multiples.
For months, institutional investors and retail participants alike have embraced a risk-on posture, channeling capital into high-beta equities, artificial intelligence darlings, and digital infrastructure plays. This concentration of capital allocation has relied heavily on a singular, foundational assumption: that inflation is definitively tamed, paving the way for aggressive monetary policy easing by the Federal Reserve. However, as crude oil benchmarks tick upward and baseline commodity prices show stubborn resilience, that core thesis faces its most severe examination yet.
The Anatomy of a Record-Setting Rally Meets Macro Reality
The current market architecture is built upon high expectations of enterprise ROI derived from technological transformation. Venture capital and corporate treasuries alike have poured billions into cloud compute architecture, data center expansion, and semiconductor fabrication, treating high capital expenditure as a mandatory toll for future dominance. This enthusiasm has compressed risk premia, pushing price-to-earnings (P/E) ratios to historical extremes.
Yet, the broader macroeconomic machinery operates on variables far outside the control of Silicon Valley boardrooms. Energy markets have reasserted their influence, with West Texas Intermediate (WTI) crude settling at $83.38 per barrel. Simultaneously, everyday consumer goods—exemplified by volatile agricultural inputs such as wholesale egg prices—demonstrate that pipeline price pressures have not been entirely eradicated.
When Wednesday's Bureau of Labor Statistics CPI data hits the wire, it will not merely be a retrospective glance at consumer prices; it will serve as a referendum on the entire trajectory of asset prices for the remainder of the fiscal year. A hotter-than-expected print will instantly challenge the prevailing narrative of a smooth macroeconomic landing, forcing fixed-income desks to reprice terminal rate expectations and triggering an immediate spike in benchmark Treasury yields.
Analyzing Market Pressures: Key Indicators

To understand the magnitude of this week's impending data release, one must examine the interlocking variables currently dictating institutional risk mitigation strategies. The table below outlines the primary macroeconomic and market metrics defining the current financial landscape:
| Indicator / Asset Class | Current Level / Status | Market Implication & Sensitivity |
|---|---|---|
| S&P 500 / NASDAQ Composite | Record-Setting Highs | Vulnerable to multiple compression if discount rates rise due to sticky inflation. |
| Crude Oil (WTI Benchmark) | $83.38 / Barrel | Acts as an immediate tax on consumer discretionary spending and supply chain logistics. |
| Wednesday CPI Release | Pending (Mid-August) | Directly dictates Federal Reserve rate-cut probabilities for the upcoming FOMC meeting. |
| Corporate Bond Yields / Spreads | Tight / Compression | High market liquidity has masked credit risk; vulnerable to sudden widening on rate shocks. |
Industry & Market Implications: Who Wins and Who Loses
A divergence in asset performance is almost certain to follow Wednesday's CPI print. The bifurcated nature of the current market means that different sectors face vastly asymmetrical risks:
- Technology & Growth Equities (The Vulnerable Giants): Mega-cap tech and semiconductor firms have led the market higher. However, because their valuations rely heavily on discounted cash flows projected far into the future, any upward shock in discount rates driven by stubborn inflation will disproportionately impact their valuation multiples.
- Energy & Commodity Producers (The Hedged Beneficiaries): With WTI crude holding firm near $83.38, energy conglomerates and exploration companies stand positioned to benefit from inflationary tailwinds, serving as an effective portfolio hedge against broader market drawdowns.
- Fixed Income & Yield-Sensitive Sectors: Utilities and real estate investment trusts (REITs), which have languished as bond yields remained elevated, face further downside if the inflation report dashes hopes of imminent, aggressive central bank rate cuts. Conversely, a soft print would ignite a relief rally across these capital-intensive industries.
Frequently Asked Questions (People Also Ask)
Why is Wednesday's CPI report so critical for record-setting US stocks?
The current stock market highs are predicated on the expectation that inflation is fully normalized, allowing the Federal Reserve to implement multiple interest rate cuts. A hotter-than-expected CPI print would challenge this outlook, forcing bond yields higher and triggering a sharp repricing of equity valuation multiples, particularly in high-flying technology sectors.
How do crude oil prices and commodities impact current Fed rate views?
Energy commodities like WTI crude ($83.38/bbl) directly influence headline inflation figures and transportation costs. When commodity prices remain elevated or tick upward, it complicates the Federal Reserve's mandate, making central bankers much more hesitant to loosen monetary policy prematurely.
What tactical steps are institutional investors taking for risk mitigation ahead of the data?
Institutional desks are increasing their allocation to short-duration fixed income, purchasing protective equity index puts, and rotating capital into cash-generative, defensive sectors with strong balance sheets to insulate portfolios against potential volatility spikes.
Future Outlook: Navigating the Post-Report Landscape
As Wall Street braces for the Bureau of Labor Statistics' figures, the overarching narrative is clear: the era of effortless equity appreciation is colliding with macroeconomic reality. Whether Wednesday’s report validates the market’s aggressive pricing or shatters the prevailing consensus, institutional capital allocation strategies will undergo an immediate realignment.
Chief investment officers and portfolio managers must maintain rigorous risk mitigation protocols, monitoring not only the headline CPI figures but also core components, labor market resilience, and secondary commodity indicators. In an environment where asset prices sit at historic peaks, the margin for policy error is virtually non-existent, making the upcoming days a defining watershed for the 2026 financial markets.