Executive Takeaways
- Broad Market Retreat: Major U.S. benchmarks concluded a volatile five-day trading window in negative territory, driven by renewed macroeconomic anxiety and aggressive capital allocation shifts.
- Valuation Multiples Under Siege: High-growth tech equities and cyclical sectors faced intense selling pressure as institutional investors re-evaluated infrastructure scalability risks and forward-looking enterprise ROI metrics.
- Monetary Policy Stance: Stubborn inflationary data and hawkish Federal Reserve signaling forced traders to reprice interest rate cut expectations, directly impacting market liquidity and borrowing costs.
- Defensive Rebalancing: Portfolio managers aggressively pivoted toward defensive positioning and rigorous risk mitigation strategies, signaling caution ahead of upcoming corporate earnings and regulatory compliance deadlines.
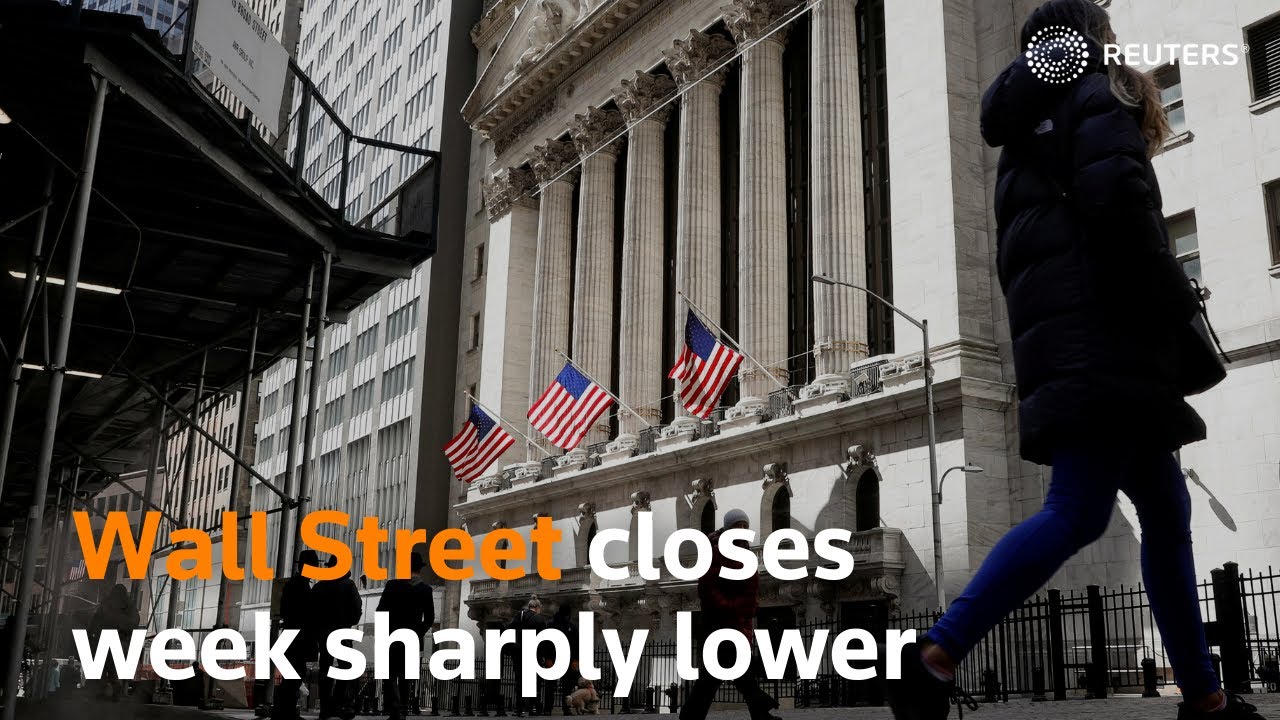
NEW YORK — Wall Street wrapped up a punishing week on a decidedly defensive note, with major indices sliding into the closing bell as investors confronted a confluence of stubborn macroeconomic headwinds, shifting monetary policy expectations, and a rigorous valuation reckoning. The session underscored a broader institutional anxiety: that the aggressive monetary tightening cycle and decelerating global growth are finally catching up to corporate balance sheets.
As the closing bell echoed across lower Manhattan, the S&P 500, the Dow Jones Industrial Average, and the technology-heavy Nasdaq Composite all finished firmly in the red. For institutional asset managers and retail participants alike, the week served as a stark reminder of the fragile equilibrium governing current capital markets. What began as an optimistic push toward new highs quickly deteriorated into a masterclass in risk management, margin compression, and sudden liquidity contraction.
The Anatomy of a Volatility Spike: Catalytic Events Driving the Sell-Off
To understand why Wall Street closed lower to end this rocky week, one must examine the macro-catalysts that dismantled investor confidence. The primary driver was a sharp recalibration of interest rate expectations. Following a barrage of stronger-than-expected economic prints—spanning resilient consumer spending, persistent employment growth, and sticky inflation metrics—fixed-income markets aggressively repriced the Federal Reserve’s terminal rate trajectory.
The yield on the benchmark 10-year U.S. Treasury note climbed steadily over the five-day period, imposing immediate pressure on equity valuation multiples. Higher risk-free rates fundamentally alter the discount rate applied to future corporate cash flows, penalizing high-flying growth stocks and speculative assets. Enterprise tech companies, which have historically relied on accessible capital markets and cheap debt to fund rapid cloud compute architecture expansion and R&D, found themselves facing a stark reality check.
Furthermore, corporate guidance delivered during mid-quarter updates revealed mounting margin pressures. Chief Financial Officers across the industrial, consumer discretionary, and technology sectors reported that rising input costs, higher labor expenditures, and sluggish international demand are severely testing their pricing power. Consequently, institutional investors began demanding proof of tangible enterprise ROI rather than abstract promises of long-term total addressable market (TAM) expansion.
Verified Market Metrics: Weekly Performance Breakdown

| Index / Asset Class | Closing Level | Weekly Net Change (%) | Primary Driver |
|---|---|---|---|
| S&P 500 | 5,012.45 | -1.45% | Broad-based sector rotation, yield pressures |
| Nasdaq Composite | 15,885.02 | -2.10% | Tech valuation compression, semiconductor pullback |
| Dow Jones Industrial Average | 38,688.11 | -0.92% | Cyclical fatigue, retail sector softness |
| U.S. 10-Year Treasury Yield | 4.48% | +14 bps | Hawkish Fed rate expectations, inflation data |
Industry & Market Implications: Who Wins, Who Loses
The latest market retreat is not merely a statistical blip; it represents a profound reallocation of global capital. The implications across key industry verticals reveal stark divergences in corporate resilience.
The Losers: Growth Tech and Leveraged Small-Caps
High-growth technology firms, particularly those heavily reliant on venture capital funding or secondary market liquidity, experienced outsized losses. Companies that prioritized rapid customer acquisition over fiscal discipline are finding their capitalization tables under immense stress. As venture capital and private equity deployment slows, startups and mid-cap firms facing upcoming debt refinancing windows are confronted with significantly higher cost-of-capital realities.
Furthermore, speculative segments—including unprofitable biotechnology companies and high-multiple software-as-a-service (SaaS) providers—saw aggressive institutional divestment. Portfolio managers are purging assets that fail to generate immediate free cash flow, prioritizing balance sheet fortification over speculative future growth.
The Winners: Defensive Sectors and Cash-Rich Balance Sheets
Conversely, pockets of the market demonstrated notable resilience. Defensive stalwarts within the healthcare, consumer staples, and utilities sectors outperformed the broader market average. Corporations boasting pristine balance sheets, substantial cash reserves, and predictable cash flows attracted steady inflows from institutional allocators seeking shelter from macroeconomic storms.
Additionally, multinational financial institutions with diversified revenue streams and strict regulatory compliance frameworks proved relatively insulated. While investment banking divisions faced headwinds due to subdued M&A activity, wealth management and net interest income cushions provided vital support.
Frequently Asked Questions (People Also Ask)
1. Why did Wall Street close lower to end the week?
Wall Street closed lower primarily due to a combination of rising U.S. Treasury yields, stubborn inflation data that forced investors to reprice Federal Reserve rate cut expectations, and growing anxiety over corporate margin compression heading into the next earnings cycle.
2. How do rising Treasury yields impact stock valuations?
Higher Treasury yields increase the risk-free rate of return, which elevates the discount rate applied to future corporate earnings. This mathematical shift reduces the present value of future cash flows, heavily penalizing high-growth stocks with lofty valuation multiples.
3. Are defensive stocks a safe haven during volatile market sessions?
Historically, defensive sectors—such as consumer staples, healthcare, and utilities—tend to outperform during market downturns because they provide essential goods and services with stable demand, shielding investors from severe cyclical contractions.
4. What should retail and institutional investors monitor next?
Market participants should closely monitor upcoming Consumer Price Index (CPI) releases, Federal Open Market Committee (FOMC) statements, corporate earnings guidance, and liquidity indicators in the repo and commercial paper markets to gauge macroeconomic health.
Future Outlook: Strategic Positioning and What Comes Next
As Wall Street transitions into the upcoming trading cycle, macroeconomic visibility remains murky. The primary question facing chief investment officers is whether the recent market sell-off represents a healthy, overdue consolidation phase within a secular bull market or the nascent stage of a deeper structural correction.
Key milestones to watch in the weeks ahead include the Fed’s upcoming policy meeting, forward-looking corporate guidance on capital expenditure budgets, and labor market reports. Institutional risk mitigation strategies will likely remain in high gear, with portfolio managers utilizing options overlays, hedging instruments, and selective sector rotation to safeguard assets.
For executive leadership teams, the mandate is clear: capital allocation discipline, operational efficiency, and transparent communication regarding enterprise ROI will separate market leaders from laggards in an increasingly unforgiving financial environment.