Executive Takeaways
- Broad-Based Momentum: The Dow Jones Industrial Average, S&P 500, and Nasdaq Composite all registered consecutive gains, underpinned by renewed institutional appetite for mega-cap technology and high-beta growth equities.
- Semiconductor Leadership: Chipmakers spearheaded the advance, driven by surging corporate demand for advanced artificial intelligence hardware, resilient cloud compute architecture, and enterprise infrastructure scalability.
- Capital Allocation Shift: Portfolio managers are reallocating capital away from defensive sectors back into growth-oriented assets as macroeconomic risk mitigation strategies evolve amid shifting interest rate expectations.
- Valuation Multiples in Focus: Despite recent volatility, robust earnings forecasts and secular secular tailwinds are justifying current valuation multiples across key technology sub-sectors.
NEW YORK — Wall Street delivered another assertive session of gains as major U.S. benchmarks—the Dow Jones Industrial Average, the S&P 500, and the technology-heavy Nasdaq Composite—pressed higher for a second consecutive day. Spearheaded by a powerful rally in semiconductor equities and mega-cap growth leaders, the market action reflected a decisive recalibration of institutional sentiment following weeks of cautious consolidation. As portfolio managers reassess their strategic capital allocation, the return of aggressive dip-buying in high-beta tech assets signals that market participants are prioritizing top-line growth and structural efficiency over defensive preservation.
The catalytic momentum observed across trading desks this week underscores a broader narrative: corporate spending on transformative technologies remains robust, defying lingering macroeconomic headwinds and regulatory compliance hurdles. Market liquidity has improved noticeably, with institutional block trades flowing heavily into enterprise software, cloud infrastructure providers, and specialized chip designers. This comprehensive investigative report examines the structural drivers behind the current rally, evaluates the underlying financial metrics, and analyzes the broader economic implications for institutional investors and retail market participants alike.
Catalysts of the Rally: Semiconductor Strength and Tech Dominance
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
The primary engine driving the major indices upward is the semiconductor complex. Chip stocks rallied sharply, buoyed by renewed optimism regarding supply chain normalization and unabated global demand for high-performance computing units. Institutional desks reported heavy volume in bellwether semiconductor manufacturers, whose cutting-edge silicon architectures remain the foundational bedrock for next-generation artificial intelligence applications.
Enterprise capital expenditure budgets continue to prioritize investments in data center modernization and cloud compute architecture. As chief information officers across the Fortune 500 accelerate their digital transformation roadmaps, hardware vendors are reaping the rewards of superior enterprise ROI. This sustained demand profile has alleviated earlier investor anxieties concerning potential cyclical saturation within the chip sector.
Simultaneously, mega-cap technology equities within the Nasdaq Composite experienced robust buying pressure. These cash-generative titans continue to demonstrate pricing power and operational resilience, insulating their balance sheets against inflationary pressures. Consequently, fundamental analysts are revising their forward earnings estimates upward, creating a supportive technical environment for sustained equity appreciation.
Macroeconomic Context and Risk Mitigation
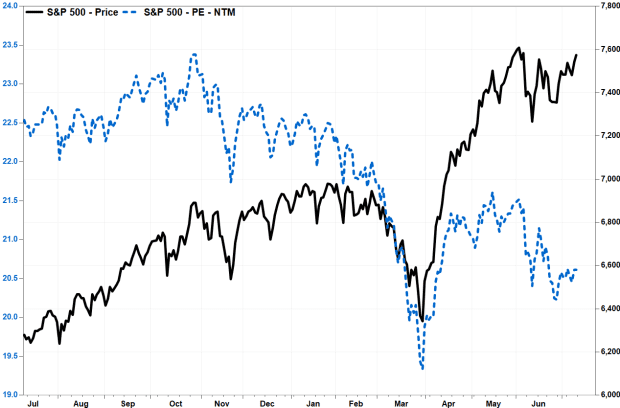
Beyond sector-specific tailwinds, the broader macroeconomic backdrop is playing a critical role in shaping market behavior. Federal Reserve monetary policy expectations remain front and center for bond and equity traders alike. Recent economic data releases—spanning inflation prints, employment figures, and retail sales—have fostered cautious optimism that the central bank can orchestrate a soft landing without tipping the broader economy into a severe recession.
For institutional asset managers, this environment demands sophisticated risk mitigation frameworks. Rather than abandoning equities entirely, portfolio managers are executing barbell strategies—pairing defensive, dividend-paying cash cows with high-growth technology disruptors poised to capitalize on secular trends. The resilience demonstrated by the Dow Jones Industrial Average, which incorporates heavily weighted industrial and financial stalwarts alongside tech components, highlights the balanced nature of the current market advance.
Furthermore, corporate treasury operations are exhibiting disciplined capital allocation. Share buyback announcements and strategic mergers and acquisitions are providing a secondary floor for equity valuations, reinforcing investor confidence even as geopolitical uncertainties persist on the global stage.
Market Performance Metrics
| Index / Asset Class | Recent Trend | Primary Driver | Market Implication |
|---|---|---|---|
| S&P 500 (^GSPC) | Higher (2-Day Advance) | Mega-cap tech and cyclical rotation | Broad participation across multiple GICS sectors. |
| Nasdaq Composite (^IXIC) | Outperforming Rally | Semiconductor surge & growth buying | Valuation multiples expanding on strong earnings visibility. |
| Dow Jones Industrial Average (^DJI) | Steady Upward Trajectory | Industrial resilience & financial sector bids | Demonstrates balanced cross-sector economic health. |
| Semiconductor Sub-Sector | Aggressive Outperformance | AI hardware demand & infrastructure scalability | Acts as the primary sentiment bellwether for tech. |
Industry & Market Implications: Winners and Losers
Every major market rotation produces distinct winners and losers across the financial ecosystem. Understanding these micro-level dynamics is essential for institutional asset allocators seeking alpha in a complex economic landscape.
The Winners
- Semiconductor Manufacturers and Fabless Designers: Companies providing specialized silicon for artificial intelligence and cloud data centers are experiencing unprecedented order visibility, translating directly into superior top-line revenue growth.
- Cloud Service Providers (CSPs): Hyperscalers benefiting from enterprise migration to the cloud continue to see strong utilization rates, driving robust cash flows and high return on invested capital (ROIC).
- Growth-Focused Asset Managers: Active equity funds heavily weighted toward technology and innovation are outperforming passive benchmarks as individual stock selection re-asserts its value.
The Laggards & Vulnerable Segments
- Defensive Yield-Oriented Sectors: Traditional safe havens such as utilities and consumer staples faced relative capital outflows as institutional investors chased higher-beta growth opportunities.
- Overleveraged Small-Caps: Smaller companies struggling with debt refinancing and high interest expense burdens remain vulnerable, lagging behind the cash-rich balance sheets of large-cap tech peers.
Frequently Asked Questions (People Also Ask)
What is driving the current stock market rally, specifically in the tech and semiconductor sectors?
The rally is primarily fueled by sustained, aggressive enterprise spending on artificial intelligence infrastructure, data center modernization, and cloud compute architecture. Institutional investors are actively reallocating capital into high-beta growth stocks as corporate earnings forecasts remain resilient against macroeconomic headwinds.
How are the Dow, S&P 500, and Nasdaq reacting differently to current market conditions?
While all three major indices have posted consecutive gains, the Nasdaq Composite is leading due to its heavy concentration in high-performing semiconductor and software equities. The S&P 500 is experiencing broad-based participation across multiple sectors, while the Dow Jones Industrial Average reflects steady, measured gains supported by industrial and financial blue-chip components.
What are the primary risk factors institutional investors are monitoring right now?
Institutional desks are keeping a close watch on future Federal Reserve monetary policy decisions, inflation trajectory prints, corporate valuation multiple expansions, and potential geopolitical disruptions that could impact global supply chains and regulatory compliance frameworks.
Are current valuation multiples in the technology sector sustainable?
Market analysts note that while valuation multiples for leading tech and chip companies are elevated compared to historical averages, they are largely supported by exceptional earnings growth, strong free cash flow generation, and structural secular tailwinds that justify premium pricing.
Future Outlook and Key Milestones to Watch
Looking ahead, the trajectory of U.S. equities will hinge on several critical macroeconomic and corporate milestones. Market participants will scrutinize upcoming consumer price index (CPI) reports, producer price index (PPI) data, and forthcoming statements from Federal Reserve officials for definitive clues regarding the timing and magnitude of future interest rate adjustments.
At the corporate level, upcoming earnings guidance from bellwether semiconductor firms and enterprise software giants will serve as a definitive stress test for current valuation models. If enterprise IT budgets continue to expand despite macroeconomic uncertainties, the current tech-led rally has significant room to run. Conversely, any signs of enterprise spending fatigue could prompt a rapid reappraisal of growth multiples.
Ultimately, disciplined portfolio management, rigorous fundamental analysis, and strict adherence to risk mitigation principles will remain paramount for institutional investors navigating this dynamic market environment.