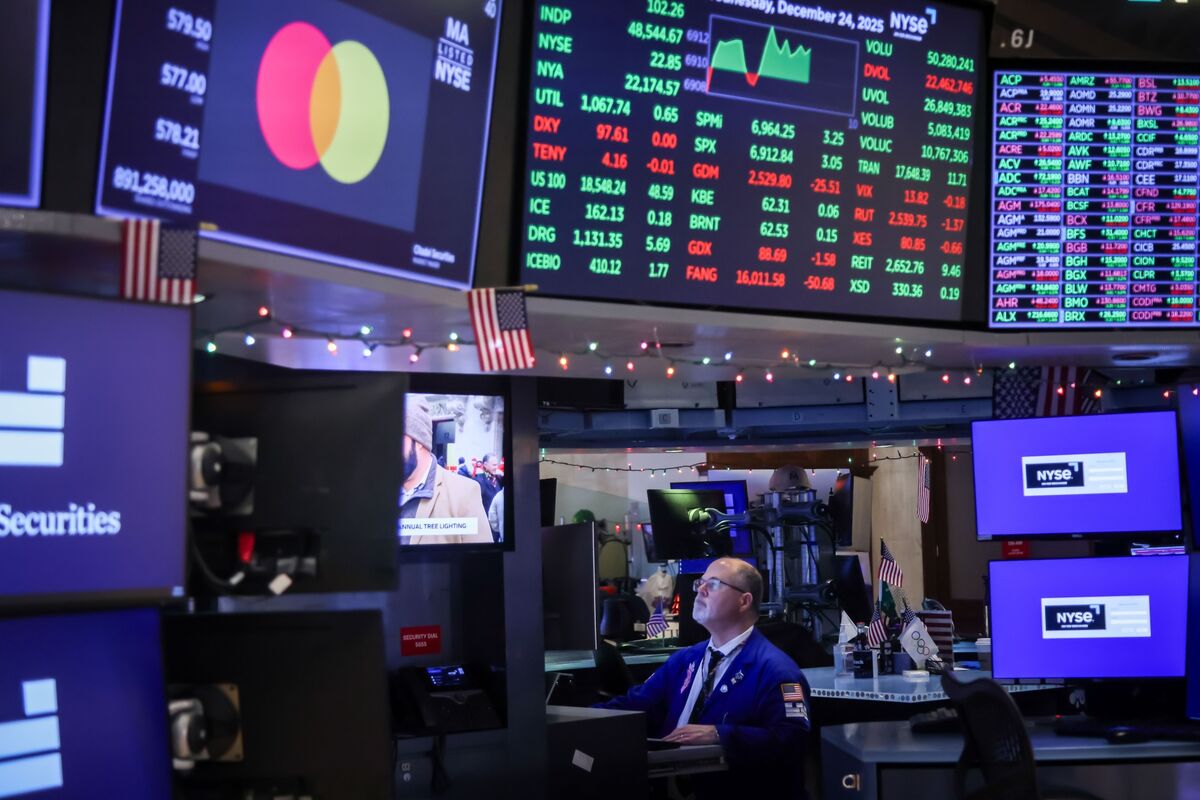
Global financial markets entered a state of tense equilibrium as an initial risk-on equities rally abruptly lost momentum. Institutional desks and systematic macro funds squared their books ahead of a high-impact cascade of macroeconomic releases. The shifting sentiment underscores a fragile market architecture where shifting valuation multiples, aggressive capital allocation strategies, and incoming labor and consumer data collide.
According to primary wire reports from Bloomberg, a cooling in retail sales figures immediately bolstered the structural investment case for monetary policy easing. This macroeconomic signal catalyzed an aggressive flight to quality, driving a sustained rally in Treasuries as fixed-income traders aggressively re-priced terminal interest rate expectations and recalibrated their duration risk profiles.
Executive Takeaways
The Macroeconomic Catalyst: Retail Sales Softness and the Fixed-Income Response

The macroeconomic narrative shifted abruptly following the release of domestic retail sales data, which pointed toward a deceleration in consumer spending momentum. For months, resilient consumer demand had served as the primary bulwark against recessionary fears, supporting corporate revenue growth and justifying elevated equity valuation multiples. However, the latest figures revealed a distinct cooling trend, prompting institutional investors to reassess the health of the broader economy.
In response, the fixed-income complex moved swiftly. Treasury yields experienced downward pressure as buying volume surged across benchmark maturities. Rates strategists noted that the weak retail print forced a recalibration of futures pricing, with interest-rate derivatives markets moving to price in a higher probability of monetary easing.
This flight to safety highlighted the intricate relationship between consumer health and capital market liquidity. As bond prices climbed, the yield curve experienced notable shifts, signaling that institutional portfolio managers are actively locking in medium- and long-term yields. This reallocation strategy serves as a classic risk mitigation play, insulating portfolios against potential equity drawdowns should upcoming labor market data disappoint.
Equities Lose Steam: Valuation Pressures and Institutional Hesitation
While the debt markets celebrated the prospect of looser monetary policy, the equity complex displayed clear signs of exhaustion. Major Wall Street indices, which had initially attempted to extend previous session gains, stalled out as trading desks realized that a slowing consumer could eventually translate into compressed corporate profit margins.
Chief Investment Officers and equity derivatives traders pointed to stretched valuations in key sectors—particularly technology and discretionary consumer goods—as primary drivers for the sudden loss of momentum. With cloud compute infrastructure spend, enterprise ROI metrics, and corporate guidance facing heightened scrutiny, institutional investors are demanding greater visibility into future earnings quality.
Furthermore, algorithmic trading programs and high-frequency market makers amplified the intraday volatility. As key technical resistance levels held firm, systematic trend-following funds were forced to unwind long positions, exacerbating the fade in the broader stock rally. The prevailing sentiment across Wall Street trading floors is one of calculated patience: no major capital allocation decisions will be finalized until the upcoming data deluge is fully digested and analyzed by economic research teams.
Verified Data & Metrics Breakdown
| Economic Indicator / Asset Class | Previous Period Reading | Current Market Print / Consensus | Market Impact & Strategic Implication |
|---|---|---|---|
| Retail Sales (MoM) | +0.6% | Below Consensus / Cooling | Triggers Treasury rally; validates slowing consumer demand thesis. |
| Benchmark 10-Year Treasury Yield | Elevated Multi-Week Range | Sharply Lower (Yield Compression) | Reflects aggressive duration buying and re-priced rate cut expectations. |
| S&P 500 / NASDAQ Momentum | Bullish Continuation | Stalled / Range-Bound | Reflects profit-taking and defensive positioning ahead of labor data. |
| Implied Volatility (VIX) | Suppressed | Modest Tick Up | Indicates rising hedging demand and options buying by institutional desks. |
Industry & Market Implications: Winners, Losers, and Systemic Risk
The ongoing market transition has created a sharp divergence between asset classes and economic sectors. Fixed-income desks, primary dealers, and bond-focused asset managers stand out as clear tactical winners in the immediate term, capturing strong capital inflows as institutional money flees equity risk.
Conversely, high-beta growth equities, venture capital-backed technology firms, and discretionary consumer brands face significant headwinds. As investors demand stricter regulatory compliance, demonstrable enterprise ROI, and robust balance sheets, unprofitable growth stories are being heavily penalized. Capital allocators are pivoting away from speculative assets in favor of cash-generative industry leaders with pricing power.
On a macro scale, the heightened sensitivity to incoming economic data underscores the precarious nature of the current economic cycle. Central bankers are walking a tightrope between tamping down persistent inflationary pressures and preventing an abrupt contraction in economic growth. Every data point—from employment figures to retail spending—now carries outsized weight, driving immediate volatility across global forex, equity, and debt markets.
Frequently Asked Questions (People Also Ask)
Why did the stock rally fade despite falling Treasury yields?
While falling Treasury yields typically support equity valuations by lowering borrowing costs, the stock rally stalled because the yield decline was driven by weak retail sales data. Investors interpreted this retail softness as an early warning sign of slowing consumer demand, which could negatively impact corporate earnings and profit margins going forward.
How do macroeconomic data releases impact institutional capital allocation?
Institutional asset allocators rely on macroeconomic data to assess economic momentum, inflation trends, and monetary policy trajectories. Surprises in retail sales, employment, or inflation force portfolio managers to adjust their risk parameters, often rotating capital out of risk-on assets like equities and into defensive fixed-income instruments.
What role do algorithmic traders play during periods of high-impact data releases?
Algorithmic and systematic trading desks execute rapid trades based on predefined quantitative models and technical resistance levels. During data-heavy periods, these programs can amplify intraday market movements, causing sudden rallies or sell-offs as stop-loss orders are triggered and liquidity depth shifts.
How are corporate earnings and enterprise ROI tied to current market volatility?
As economic growth moderates, institutional investors closely examine corporate spending efficiency, particularly in capital-intensive areas like cloud compute architecture and enterprise technology. Companies that fail to demonstrate clear, measurable enterprise ROI face severe valuation compression during periods of broader market uncertainty.
Future Outlook: Milestones and What Comes Next
As Wall Street prepares for the remainder of the reporting cycle, market participants are keeping a laser focus on upcoming labor market metrics, wage growth statistics, and central bank commentary. The upcoming employment situation report will serve as the definitive stress test for the current macroeconomic thesis.
If employment data confirms a resilient labor market alongside cooling consumer spending, the narrative may shift toward a coveted "soft landing" scenario, providing a renewed foundation for equity outperformance. However, any unexpected weakness in job creation could trigger heightened recessionary fears, accelerating the flight to safety and pressuring risk assets.
Ultimately, disciplined risk mitigation, rigorous balance-sheet analysis, and agile capital allocation will define institutional success in the weeks ahead. Traders and portfolio managers must maintain rigorous liquidity management protocols to navigate the rapid valuation adjustments characteristic of today’s complex macro environment.