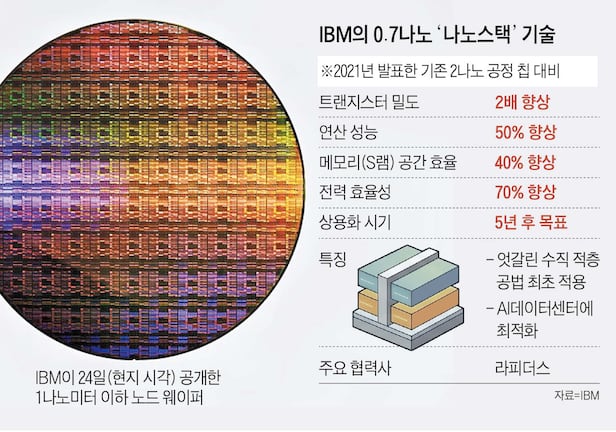
ALBANY, N.Y. & SEOUL — June 26, 2026 — In a seismic shift for the global technology ecosystem, IBM Research has announced the development of the world’s first operational sub-1-nanometer (sub-1nm) semiconductor process technology. Unveiled at the Albany Nanotech Complex, the breakthrough promises a staggering 50% boost in processing performance or up to a 75% reduction in power consumption compared to current 2nm production nodes. The milestone effectively shatters long-standing physics barriers associated with quantum tunneling and silicon scaling, signaling a fundamental realignment in hyper-scale cloud computing architecture, enterprise AI hardware economics, and sovereign semiconductor supply chains.
As major foundries navigate the exorbitant capital intensity of sub-2nm node transitions, IBM’s IP disclosure provides a critical blueprint for the entire semiconductor equipment and design ecosystem. The timing is paramount: with enterprise demand for artificial intelligence infrastructure squeezing datacenter power grids globally, a 50% jump in compute density directly translates to game-changing capital allocation strategies and enterprise return on investment (ROI) for global hyperscalers.
Executive Takeaways
- Architectural Breakthrough: IBM has successfully demonstrated sub-1nm physical transistor geometry utilizing a novel Complementary Field-Effect Transistor (CFET) architecture coupled with High-NA Extreme Ultraviolet (EUV) lithography.
- Performance & Efficiency Delta: The sub-1nm node delivers a 50% gain in operating frequency at equivalent power envelopes, or a 75% power reduction at baseline operational speeds versus state-of-the-art 2nm processors.
- Economic Infrastructure Shift: For enterprise cloud operators, the leap promises to lower Total Cost of Ownership (TCO) across AI training clusters by as much as 40%, optimizing power-density limits currently bottlenecking tier-1 datacenters.
- Foundry & Equipment Tailwinds: The technical validation provides immense momentum for semiconductor equipment vendors specializing in atomic layer deposition (ALD) and High-NA lithography, while placing immense pressure on pure-play foundries to license or accelerate competing sub-angstrom roadmaps.
The Engineering Marvel: Transcending the Physical Limits of Silicon

For over five decades, Moore’s Law has served as the baseline economic rhythm of the global technology sector. However, as transistor gate lengths approached atomic dimensions, standard silicon structures hit a critical roadblock: quantum tunneling. At sub-2nm scales, electrons routinely leak across ultra-thin gate oxide barriers, generating unacceptable levels of parasitic heat and rendering conventional GAA (Gate-All-Around) nanosheet architectures economically and thermally inefficient.
IBM’s sub-1nm process overcomes these fundamental physical constraints through a radical evolution in transistor topology and material science. Building upon its pioneering 2nm nanosheet work in 2021, IBM’s research team transitioned to a vertically stacked 3D Complementary Field-Effect Transistor (CFET) design. By stacking n-channel and p-channel field-effect transistors directly on top of one another rather than side-by-side, the architectural layout yields a dramatic 2x increase in logic density per unit area.
Atomic Layer Control & Advanced Lithography Integration
Achieving structural integrity at sub-1nm scales required unprecedented precision in patterning and material synthesis. The process leverages ASML’s high-numerical-aperture (0.55 NA) High-NA EUV systems, allowing single-exposure patterning of features that previously required cost-prohibitive multi-patterning techniques. Furthermore, IBM replaced standard silicon channels in select critical paths with 2D transition metal dichalcogenides (TMDs)—monolayer atomic semiconductor materials that maintain high electron mobility even at sub-nanometer channel thicknesses.
To eliminate inter-wire bottlenecking and resistive voltage drops, the sub-1nm node natively integrates a Backside Power Delivery Network (BSPDN). By relocating all power routing to the reverse side of the silicon wafer, power lines no longer contend with signal lines on the top interconnect layers. This structural decoupling reduces IR drop (voltage drop) by roughly 30%, directly facilitating the reported 50% frequency boost.
Data & Performance Metrics Breakdown
The comparative matrix below details the performance, density, and physical scaling metrics of IBM’s sub-1nm milestone against previous baseline process nodes:
| Process Metric | 7nm (Baseline) | 2nm (Nanosheet Era) | IBM Sub-1nm (3D-CFET Era) | Variance vs. 2nm Target |
|---|---|---|---|---|
| Transistor Density (MTr/mm²) | ~90 to 100 | ~330 | >600 | +81.8% Density Gain |
| Performance @ Fixed Power | 1.0x Baseline | +45% vs. 7nm | +50% vs. 2nm | +50% Frequency Increase |
| Power Draw @ Fixed Clock | 1.0x Baseline | -75% vs. 7nm | -75% vs. 2nm | 75% Lower Energy Draw |
| Transistor Topology | FinFET | Horizontal Nanosheet (GAA) | Stacked 3D-CFET + BSPDN | Vertical Cell Stacking |
| Lithography Requirement | EUV (0.33 NA) | EUV Multi-patterning | High-NA EUV (0.55 NA) | Single-pass High-NA Integration |
Industry & Market Implications: Re-Engineering Capital Allocation
IBM’s unveiling comes at a pivotal juncture for global capital allocation in tech. As artificial intelligence models scale exponentially, datacenter operators face immediate limits on electrical power access, cooling infrastructure, and floor space. A process node that delivers a 50% performance uplift at half the power requirement rewrites the valuation multiples and return projections for hyperscale capital expenditure (CapEx).
Foundry Dynamics: Pressure on TSMC, Samsung, and Intel
While IBM operates as an R&D power and ecosystem architect rather than a high-volume merchant foundry, its intellectual property disclosures set the operational target for the global ecosystem. TSMC (Taiwan Semiconductor Manufacturing Co.), Samsung Electronics, and Intel Foundry Services (IFS) are all racing to commercialize sub-2nm and sub-1.5nm (A14/A10) nodes by late 2027 or 2028.
IBM’s successful pilot at Albany accelerates the timeline for competitive adaptation. Foundries that fail to integrate stacked CFET designs rapidly risk margin compression and customer defection among top fabless AI designers (e.g., NVIDIA, AMD, Apple). Analysts expect commercial foundries to seek strategic IP cross-licensing partnerships or joint development agreements with IBM to mitigate the astronomical R&D costs—now exceeding $20 billion per leading-edge node platform.
Enterprise ROI & Cloud Compute Scaling
For cloud service providers (CSPs) like Microsoft Azure, Amazon Web Services (AWS), and Google Cloud, sub-1nm processing silicon represents a fundamental lowering of the TCO curve for generative AI inference and training. Datacenter power efficiency directly constrains compute capacity in key strategic regions. By doubling logic density while dramatically suppressing heat generation, CSPs can host 2x to 3x more processing engines per megawatt of facility supply, accelerating the timeline to profitability for custom silicon initiatives (such as AWS Trainium or Google TPU projects).
Upstream Equipment Supply Chain Winners
The transition to sub-1nm silicon guarantees structural demand growth for specialized semiconductor manufacturing toolmakers:
- ASML Holding: Exclusive supplier of the High-NA EUV scanners required to achieve sub-angstrom edge placement accuracy without prohibitive yield degradation.
- Applied Materials & Lam Research: Critical suppliers for atomic layer deposition (ALD), selective epitaxy, and anisotropic etching tools capable of processing complex 3D-CFET architectures and backside power delivery layers.
- KLA Corporation: Demand for advanced optical and e-beam inspection equipment will surge as defect density management becomes sub-nanometer in critical dimension scales.
Frequently Asked Questions (People Also Ask)
What does "sub-1nm" mean in modern chip manufacturing?
Sub-1nm (sub-nanometer) refers to the next generation of semiconductor process technology featuring structural dimensions measured in angstroms (where 1nm equals 10 angstroms). Rather than signaling physical gate lengths alone, "sub-1nm" designates an integrated logic density standard exceeding 600 million transistors per square millimeter, enabled through 3D vertical stacking (CFET) and advanced material science.
How does IBM's sub-1nm node achieve a 50% performance boost?
The 50% performance surge stems from three core architectural changes: transitioning from horizontal Gate-All-Around (GAA) to stacked 3D Complementary FET (CFET) design; incorporating low-resistance 2D TMD materials in the channel; and integrating Backside Power Delivery (BSPDN). This layout dramatically reduces interconnect parasitic capacitance and resistive voltage loss, allowing the transistors to switch at significantly higher clock frequencies without thermal breakdown.
When will sub-1nm chips be available in consumer and enterprise devices?
Historically, IBM demonstrates fundamental process breakthroughs approximately 3 to 5 years ahead of commercial mass production. Following the 2026 announcement, high-volume merchant foundries are expected to adapt sub-1nm/angstrom designs into commercial production runs by late 2029 or early 2030, targeting enterprise AI datacenters first before trickling down to flagship mobile and personal computing chips.
How does this technological leap impact global enterprise CapEx strategies?
Sub-1nm technology changes the operational economics of enterprise datacenters. Because power availability—not floor space—is the primary bottleneck for hyperscale AI deployment, chips offering a 75% power reduction at static compute rates allow cloud operators to yield up to twice the effective compute output per gigawatt of power infrastructure, delivering vastly superior long-term ROI on server fleet investments.
Future Outlook & Key Milestones to Watch
The journey from IBM’s Albany Nanotech laboratory to high-yield, commercial wafer output involves several critical hurdles over the next 36 to 48 months. Investors and technology executives must monitor three major operational parameters:
- Commercial Yield Metrics (2027–2028): Transitioning 3D-CFET layouts from initial test-vehicle arrays to fully functional 300mm wafer yields exceeding 70-80% is the single largest hurdle for commercial foundries licensing or developing sub-1nm technologies.
- High-NA EUV Scanner Deployment: Track tool delivery volumes and uptime efficiency metrics for ASML’s EXE:5000 series systems across foundry pilot lines in Taiwan, South Korea, and the United States.
- Ecosystem Standard Alignment: Standardizing Backside Power Delivery and 3D design rule enablement (EDA) tools through key design software vendors like Synopsys and Cadence will determine how rapidly fabless chipmakers can adapt custom designs to sub-1nm topology.
IBM’s sub-1nm unveil reinforces the premise that silicon technology is far from its ultimate physical wall. Through structural evolution, spatial stacking, and novel material integration, the semiconductor sector has opened an entirely new frontier—the Angstrom Era—setting the structural backdrop for the next decade of artificial intelligence, high-performance computing, and enterprise infrastructure growth.