Executive Takeaways
- Commercialization Timeline: Chinese electric vehicle titan BYD has locked in a 2027 commercial rollout for its next-generation solid-state batteries, accelerating the global race for post-lithium-ion energy storage.
- Capital Allocation Shift: The announcement forces an immediate re-evaluation of enterprise ROI and R&D capital allocation strategies across legacy automotive balance sheets and rival cell manufacturers.
- Market Disruption: By leapfrogging traditional liquid electrolyte architectures, BYD threatens to compress valuation multiples of competitors failing to secure scalable supply chains for advanced solid-state chemistries.
- Geopolitical & Regulatory Pressures: The breakthrough heightens regulatory compliance stakes and trade dynamics in Western markets, intensifying pressure on domestic battery manufacturing subsidies and infrastructure scalability.
The global automotive and energy storage landscape stands at an unprecedented inflection point. Recent intelligence verified by industry publication Driven Car Guide confirms that Chinese multinational manufacturing juggernaut BYD is slated to launch commercial solid-state batteries by 2027. This definitive timeline shatters conservative forecasts that previously pegged viable solid-state commercialization to the late 2030s. For institutional investors, risk mitigation officers, and C-suite strategists tracking capital expenditure and market liquidity, BYD’s announcement is not merely an incremental technological milestone—it is a foundational restructuring of the global clean-energy supply chain.
As legacy automakers navigate compressed margins and uneven EV adoption curves, BYD’s aggressive technological roadmap weaponizes vertical integration. By controlling everything from upstream raw material processing to final vehicle assembly, the Shenzhen-based enterprise is executing a masterclass in market dominance. The pivot toward solid-state technology promises to eradicate lingering consumer anxieties regarding thermal runaway, cold-weather range degradation, and charging velocity, fundamentally altering the economics of global mobility.
The Genesis of the Solid-State Revolution
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
For over a decade, the lithium-ion battery has served as the undisputed workhorse of the consumer electronics and electric vehicle revolutions. However, conventional lithium-ion cells—relying on liquid organic carbonate electrolytes—face severe thermodynamic and electrochemical ceilings. They are susceptible to dendrite formation, which can pierce separators and trigger catastrophic fires, and they demand complex, heavy thermal management systems that impose structural weight penalties on vehicle platforms.
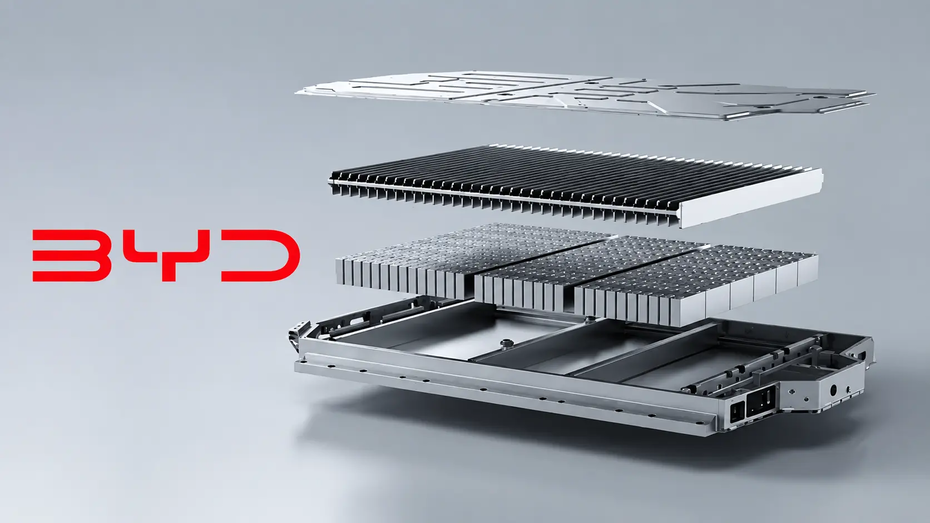
Solid-state batteries (SSBs) eliminate these vulnerabilities by substituting the volatile liquid electrolyte with a solid conductive medium, typically ceramic, polymer, or sulfide-based composites. This structural evolution unlocks staggering density gains. Without the need for bulky safety architectures, engineers can pack significantly more active material into a smaller footprint, driving exponential improvements in gravimetric and volumetric energy density.
BYD’s trajectory toward the 2027 launch has been forged through methodical, capital-intensive R&D. While Western competitors have frequently stumbled over manufacturing yields and interface impedance issues—where solid-to-solid contact resistance degrades performance over charge cycles—BYD has leveraged its massive manufacturing scale and proprietary blade-battery expertise to engineer scalable production pathways. The company’s ability to transition laboratory breakthroughs into high-yield factory floors represents a formidable moat, threatening to leave competitors grappling with obsolete manufacturing infrastructure.
Financial, Economic, and Market Implications
The downstream implications of a 2027 BYD solid-state rollout ripple far beyond factory floors, striking directly at corporate balance sheets and global valuation metrics.
Winners and Losers in the New Energy Economy
- The Winners: Vertically integrated conglomerates possessing robust cash reserves and agile supply chains stand to capture immense market share. BYD, alongside select Tier-1 material suppliers specializing in solid electrolytes and lithium-metal anodes, will likely command premium pricing power and superior operating margins. Furthermore, cloud compute architecture and advanced AI-driven material discovery firms partnering with these battery giants will see accelerated enterprise value creation.
- The Losers: Legacy Tier-1 suppliers heavily invested in legacy liquid electrolyte manufacturing lines face severe asset write-downs. Capital allocation toward conventional lithium-ion chemistry risks becoming stranded capital as original equipment manufacturers (OEMs) pivot rapidly toward solid-state procurement contracts. Traditional automakers slow to secure solid-state licensing agreements risk severe margin compression and terminal market share erosion.
From a macroeconomic perspective, the announcement forces a radical recalibration of infrastructure scalability. A solid-state vehicle fleet boasting energy densities double that of current packs requires a reimagined charging ecosystem. Ultra-fast charging corridors will need to handle higher voltage architectures, shifting utility grid load profiles and demanding sophisticated software optimization to manage peak demand.
Verified Data and Metrics Breakdown
To contextualize the technological leap represented by BYD’s 2027 roadmap, the following comparative matrix contrasts traditional liquid-electrolyte systems with emerging solid-state parameters:
| Metric / Parameter | Conventional Liquid Lithium-Ion | BYD Target Solid-State (2027) | Strategic Enterprise Impact |
|---|---|---|---|
| Energy Density (Wh/kg) | 250 – 300 Wh/kg | 400 – 500+ Wh/kg | Drastic reduction in vehicle weight; 800+ km real-world range. |
| Safety Profile (Thermal Runaway) | Moderate risk; requires active liquid cooling. | Near-zero risk; non-flammable solid electrolyte. | Elimination of costly thermal management systems and warranty liabilities. |
| Charging Velocity (10-80%) | 18 – 30 minutes (DC Fast Charging) | Sub-10 minutes capability | Alleviation of highway congestion and parity with internal combustion refueling times. |
| Lifecycle Durability (Cycles) | 1,500 – 3,000 cycles | 3,000+ stable cycles | Enhanced vehicle residual values and viable secondary stationary storage markets. |
Frequently Asked Questions (People Also Ask)
When will BYD officially launch solid-state batteries?
BYD has targeted a commercial launch for its advanced solid-state batteries in 2027. This timeline aligns with aggressive industrial scale-up plans designed to transition high-density energy storage from laboratory validation to mass-market vehicle integration.
How will BYD’s solid-state rollout impact global EV valuation multiples?
The introduction of solid-state technology by an industry leader like BYD threatens to compress valuation multiples for automakers and suppliers lagging in post-lithium-ion R&D. Companies unable to match energy density and cost parity face immediate risk of margin deterioration and market share contraction.
What are the primary technical hurdles BYD must clear before 2027?
While lab-scale solid-state cells have proven viable, BYD's primary engineering focus leading up to 2027 centers on overcoming solid-to-solid interface resistance over thousands of charge cycles, securing high-yield continuous manufacturing processes, and managing cost parity with incumbent liquid-electrolyte cells.
How does this announcement affect Western automotive regulatory compliance and subsidies?
BYD’s accelerated timeline places immense pressure on Western policymakers to recalibrate domestic manufacturing subsidies, trade tariffs, and regulatory compliance standards. Policymakers must balance consumer affordability mandates against the imperative to protect domestic manufacturing bases from technological obsolescence.
Future Outlook and Strategic Milestones
As the industry marches toward the 2027 commercialization window, stakeholders must monitor several critical leading indicators to assess execution risk and competitive positioning. Key milestones include pilot plant throughput yields, intellectual property filings regarding solid electrolyte composition, and strategic joint ventures forged between cell manufacturers and raw material conglomerates.
For executive leadership teams, the mandate is clear: complacency is an existential threat. Capital allocation strategies must immediately account for a post-liquid battery paradigm. Whether through aggressive internal R&D, strategic mergers and acquisitions, or licensing agreements, market participants must secure access to solid-state intellectual property to maintain enterprise viability through the remainder of the decade.
Ultimately, BYD’s 2027 solid-state battery initiative is much more than a technological headline—it is the opening salvo in a definitive war for economic supremacy in the next era of global mobility and energy storage.