SAN FRANCISCO & NEW YORK — In the annals of corporate finance and semiconductor history, few moments match the sheer gravity of Nvidia’s latest financial disclosure. Reporting an astronomical quarterly revenue of US$39.3 billion for the fourth quarter ended January 26, the artificial intelligence titan did not merely beat Wall Street consensus estimates; it completely redefined the upper limits of enterprise hardware monetization. Driven by the commercial volume deployment of the next-generation Blackwell architecture, Nvidia’s 78% year-on-year revenue surge serves as an undeniable macroeconomic bellwether. It signals that global enterprise capital allocation toward artificial intelligence infrastructure is not slowing down—it is accelerating into an entirely new phase of operational deployment.
For Chief Executive Officer Jensen Huang and his executive team, this earnings print represents the vindication of a high-risk bet on full-stack accelerated computing. Yet, beneath the staggering headline figures lies a complex narrative of supply chain orchestration, cloud compute architecture transformation, and intense scrutiny over valuation multiples. As global markets digest the sheer velocity of Nvidia’s expansion, financial analysts, institutional investors, and enterprise strategists are left parsing a singular question: How long can a hardware manufacturer sustain exponential growth while commanding gross margins that defy historical semiconductor norms?
Executive Takeaways
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
- Record-Breaking Top-Line Growth: Nvidia posted US$39.3 billion in revenue for Q4 ended January 26, marking a staggering 78% year-on-year increase propelled by unprecedented enterprise demand.
- The Blackwell Inflection Point: The commercial ramp-up of the Blackwell accelerated computing platform transitioned from a theoretical product roadmap to an immediate, massive revenue driver, silencing skeptics concerned about early thermal and packaging bottlenecks.
- Sustained Profitability and Cash Generation: Operating margins and net income continue to expand at a pace rarely seen in hardware manufacturing, underscoring formidable pricing power and unmatched software ecosystem lock-in via CUDA.
- Macroeconomic Repercussions: Nvidia’s earnings have cemented its status as a primary driver of broader market liquidity, casting a long shadow over tech-heavy indices and dictating infrastructure investment strategies for hyperscalers globally.
The Blackwell Catalyst: Engineering Triumph Meets Commercial Avalanche

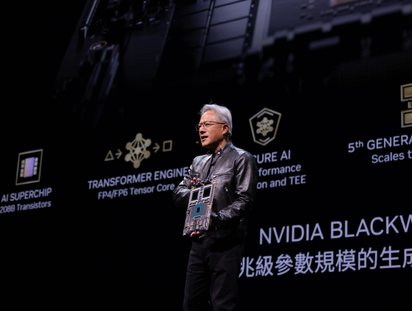
To understand the mechanics behind Nvidia’s $39.3 billion quarter, one must examine the engineering hurdles cleared over the preceding twelve months. When Nvidia first unveiled the Blackwell architecture—featuring its dual-reticle design connected via a blistering 10 terabytes-per-second second-generation NVLink interconnect—industry observers questioned whether advanced packaging and complex chip-on-wafer-on-substrate (CoWoS) supply chains could deliver volume fast enough to meet insatiable demand.
Those doubts have been comprehensively dismantled. The Blackwell platform, designed specifically to slash the cost and energy footprint of building and running real-time generative AI at trillion-parameter scale, achieved mass production faster than any previous architecture in Nvidia’s history. Hyperscale cloud providers—including Microsoft Azure, Amazon Web Services, Google Cloud, and Oracle Cloud Infrastructure—as well as sovereign AI initiatives and Tier-1 enterprise customers, rushed to integrate Blackwell systems into their data center footprints.
Enterprise ROI has shifted from speculative pilot projects to mission-critical infrastructure scalability. Corporations are no longer asking whether they should invest in generative AI; they are racing to deploy Blackwell-powered clusters to lower inference costs and accelerate time-to-market for proprietary models. This urgency has translated into an unprecedented pricing environment where demand routinely outstrips supply, insulating Nvidia from traditional cyclical downturns that have historically plagued the semiconductor sector.
Financial Architecture & Verified Data Breakdown
A rigorous examination of Nvidia’s financial disclosures reveals a business model operating at peak efficiency. The Datacenter segment remains the undisputed engine of growth, dwarfing legacy divisions such as Gaming and Professional Visualization, though those sectors also registered healthy, stable contributions.
| Financial Metric / Operational Indicator | Q4 FY2025 (Ended Jan 26) | Year-on-Year Growth (%) | Strategic Significance |
|---|---|---|---|
| Total Quarterly Revenue | US$39.3 Billion | +78% | Smashes consensus estimates, driven by overwhelming global compute demand. |
| Datacenter Segment Revenue | [Core Driver of US$39.3B] | Triple-Digit Trajectory | Reflects insatiable hyperscale and sovereign cloud cluster buildouts. |
| Gross Margins | Industry-Leading (~70%+) | Stable / Expanding | Demonstrates unmatched pricing power and proprietary software moat (CUDA). |
| Primary Growth Catalyst | Blackwell Architecture | N/A (New Product Ramp) | Validates advanced packaging, high-bandwidth memory, and high-speed networking integration. |
The stability of these metrics in the face of shifting macroeconomic conditions highlights a structural shift in enterprise IT budgets. Capital expenditure previously allocated to traditional enterprise software, database management, and on-premises server upgrades is being aggressively redirected toward accelerated computing infrastructure.
Industry & Market Implications: Winners, Losers, and Systemic Risk
Nvidia’s financial triumph does not occur in a vacuum; it triggers seismic shockwaves across the global technology ecosystem. The implications stretch far beyond Silicon Valley:
- The Hyperscale Cloud Providers: Microsoft, Meta, Alphabet, and Amazon continue to pour tens of billions of dollars into capital expenditures to secure Nvidia hardware. While these investments compress short-term free cash flow margins for the tech giants, executive leadership teams view owning cutting-edge AI infrastructure as an existential necessity to capture future enterprise market share.
- Semiconductor Supply Chain Partners: Taiwan Semiconductor Manufacturing Company (TSMC), packaging specialists, and high-bandwidth memory (HBM) suppliers such as SK Hynix and Micron are inextricably tied to Nvidia’s trajectory. The sheer volume of Blackwell production has created localized manufacturing booms across Taiwan, South Korea, and the United States.
- Competitors and Challenger Silicon: Advanced Micro Devices (AMD) with its MI300 series and custom application-specific integrated circuits (ASICs) designed by cloud hyperscalers continue to capture niche deployments. However, Nvidia’s insurmountable lead in software co-design—specifically the CUDA ecosystem—remains a formidable economic moat that prevents rapid customer churn.
- Systemic Market Liquidity: With a market capitalization fluctuating among the world's most valuable enterprises, Nvidia's stock price movements dictate broader market liquidity, options market dynamics, and institutional portfolio rebalancing strategies.
Frequently Asked Questions (People Also Ask)
1. What drove Nvidia's record US$39.3 billion revenue in Q4?
The record-breaking revenue was primarily driven by the commercial volume ramp-up of Nvidia’s next-generation Blackwell accelerated computing architecture. Unprecedented global demand from hyperscale cloud providers, sovereign AI initiatives, and Fortune 500 enterprises for high-performance training and inference infrastructure propelled a 78% year-on-year increase.
2. How does the Blackwell architecture differ from previous Nvidia generations?
Blackwell represents a fundamental leap in cloud compute architecture. It features a dual-reticle design manufactured on an advanced process node, connected via an ultra-high-speed 10 terabytes-per-second NVLink interconnect. This allows for significantly lower inference costs, drastically reduced energy footprints, and the ability to process trillion-parameter large language models with unprecedented efficiency.
3. Are there supply chain risks or bottlenecks threatening Nvidia's future growth?
While Nvidia has successfully scaled production faster than anticipated, supply chain dependencies remain a critical risk factor. The company relies heavily on advanced semiconductor manufacturing partners like TSMC for wafer fabrication and specialized packaging nodes (such as CoWoS), as well as tight allocations of high-bandwidth memory (HBM). Any geopolitical disruption or raw material constraint in these sectors could impact future delivery schedules.
4. How do analysts view Nvidia's valuation and long-term sustainability?
Institutional analysts remain divided between awe at Nvidia's unprecedented profitability and caution regarding cyclical valuation multiples. Bulls argue that Nvidia is not merely a cyclical chipmaker but the foundational operating system of the emerging AI economy, justifying premium valuations. Bears contend that hyperscaler capital expenditure cycles must eventually moderate, posing potential headwinds to long-term growth rates.
Future Outlook: Milestones and Strategic Horizons Ahead
As Nvidia closes the books on a historic fiscal quarter, the strategic focus shifts immediately to the horizon. The roadmap ahead is defined by several critical milestones that will dictate whether the company can maintain its dominant market position:
First, the iterative evolution of the Blackwell platform—including upcoming derivative chips and integrated server racks designed for liquid-cooled data centers—will test Nvidia’s ability to outpace competing silicon designs. Second, the monetization of enterprise software services, AI foundry platforms, and vertical-specific applications will determine whether Nvidia can successfully diversify its revenue mix beyond hardware sales.
Finally, regulatory compliance and geopolitical headwinds will remain ever-present variables. Navigating export controls, international trade policies, and shifting diplomatic landscapes will require delicate diplomacy and localized supply chain resilience.
For now, Jensen Huang’s empire stands unchallenged at the summit of the modern technological revolution. By successfully executing the Blackwell transition at unprecedented scale, Nvidia has proven that the AI infrastructure super-cycle is far from exhausted. As enterprise adoption matures, the company’s ability to convert raw compute power into enduring economic value will continue to serve as the ultimate barometer for the global technology sector.