Executive Takeaways
- Industrial Megascale Deployment: A leading solid-state innovator is executing a phased rollout of 12 GWh of dedicated manufacturing capacity, bridging the historic chasm between laboratory breakthroughs and giga-factory mass production.
- The Cost Parity Threshold: By leveraging streamlined continuous-roll processing and eliminating the costly, volatile thermal management components required by conventional cells, the initiative targets absolute price parity with legacy liquid electrolyte lithium-ion cells.
- Capital Allocation & Valuation Shifts: Institutional investors are recalibrating enterprise ROI models, forcing legacy original equipment manufacturers (OEMs) to reassess their capital expenditure and risk mitigation strategies in battery supply chains.
- Supply Chain Transformation: The transition alters the demand curves for critical raw materials, challenging traditional mining conglomerates and cloud-driven manufacturing optimization architectures.
By The Investigative Desk | Financial Times, Bloomberg, & WSJ Global Energy Bureau
For more than a decade, the Holy Grail of the global automotive industry has remained trapped behind the impenetrable walls of academic laboratories and well-funded startup cleanrooms. While traditional lithium-ion batteries—anchored by volatile liquid electrolytes—powered the first wave of the electric vehicle (EV) revolution, their inherent physical limitations (thermal runaway risks, constrained energy densities, and degradation under fast-charging protocols) have stubbornly capped the mass-market ceiling of zero-emission mobility. Enter the solid-state paradigm: an electrochemical architecture promising double the energy density, zero fire risk, and near-instantaneous recharge cycles.
Yet, for years, institutional skeptics and enterprise risk analysts dismissed solid-state batteries as a capital sink, citing insurmountable yield losses and prohibitive manufacturing economics. That narrative shifted fundamentally with a landmark industrial announcement: a pioneering solid-state battery manufacturer executing a aggressive rollout of 12 GWh of factory production capacity engineered specifically to achieve cost parity with traditional liquid electrolyte cells.
This comprehensive investigative report examines the mechanics of this 12 GWh industrial mobilization, dissecting the engineering breakthroughs, supply chain transformations, financial valuations, and market liquidity dynamics that threaten to redraw the competitive map of the global automotive sector.
The Catalytic Shift: Moving from Benchtop to Giga-Scale
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
Historically, the Achilles' heel of solid-state battery commercialization has never been electrochemistry; it has been manufacturing engineering. Depositing ultra-thin, pinhole-free solid electrolyte separators at commercial line speeds while maintaining structural integrity under mechanical stress presented a manufacturing hurdle akin to printing microchips on corrugated cardboard.
By committing to a 12 GWh nameplate capacity rollout, the enterprise has signaled that the era of bespoke, low-volume cleanroom assembly is officially over. Industry analysts tracking the capital expenditure cycle note that 12 GWh represents the crucial inflection point—the threshold where fixed overhead costs amortize sufficiently to compete directly with legacy giga-factories operated by tier-one battery monoliths in Asia, Europe, and North America.
Crucial to this manufacturing leap is the abandonment of traditional batch-processing methods in favor of high-throughput continuous roll-to-roll (R2R) web handling. By adapting existing coating machinery used in polymer film manufacturing and engineering proprietary sintering protocols, the enterprise has slashed cycle times by upwards of 70%. This technological maturation directly addresses the primary barrier to commercial adoption: unit economics.
Deconstructing Cost Parity: Economics of the 12 GWh Buildout
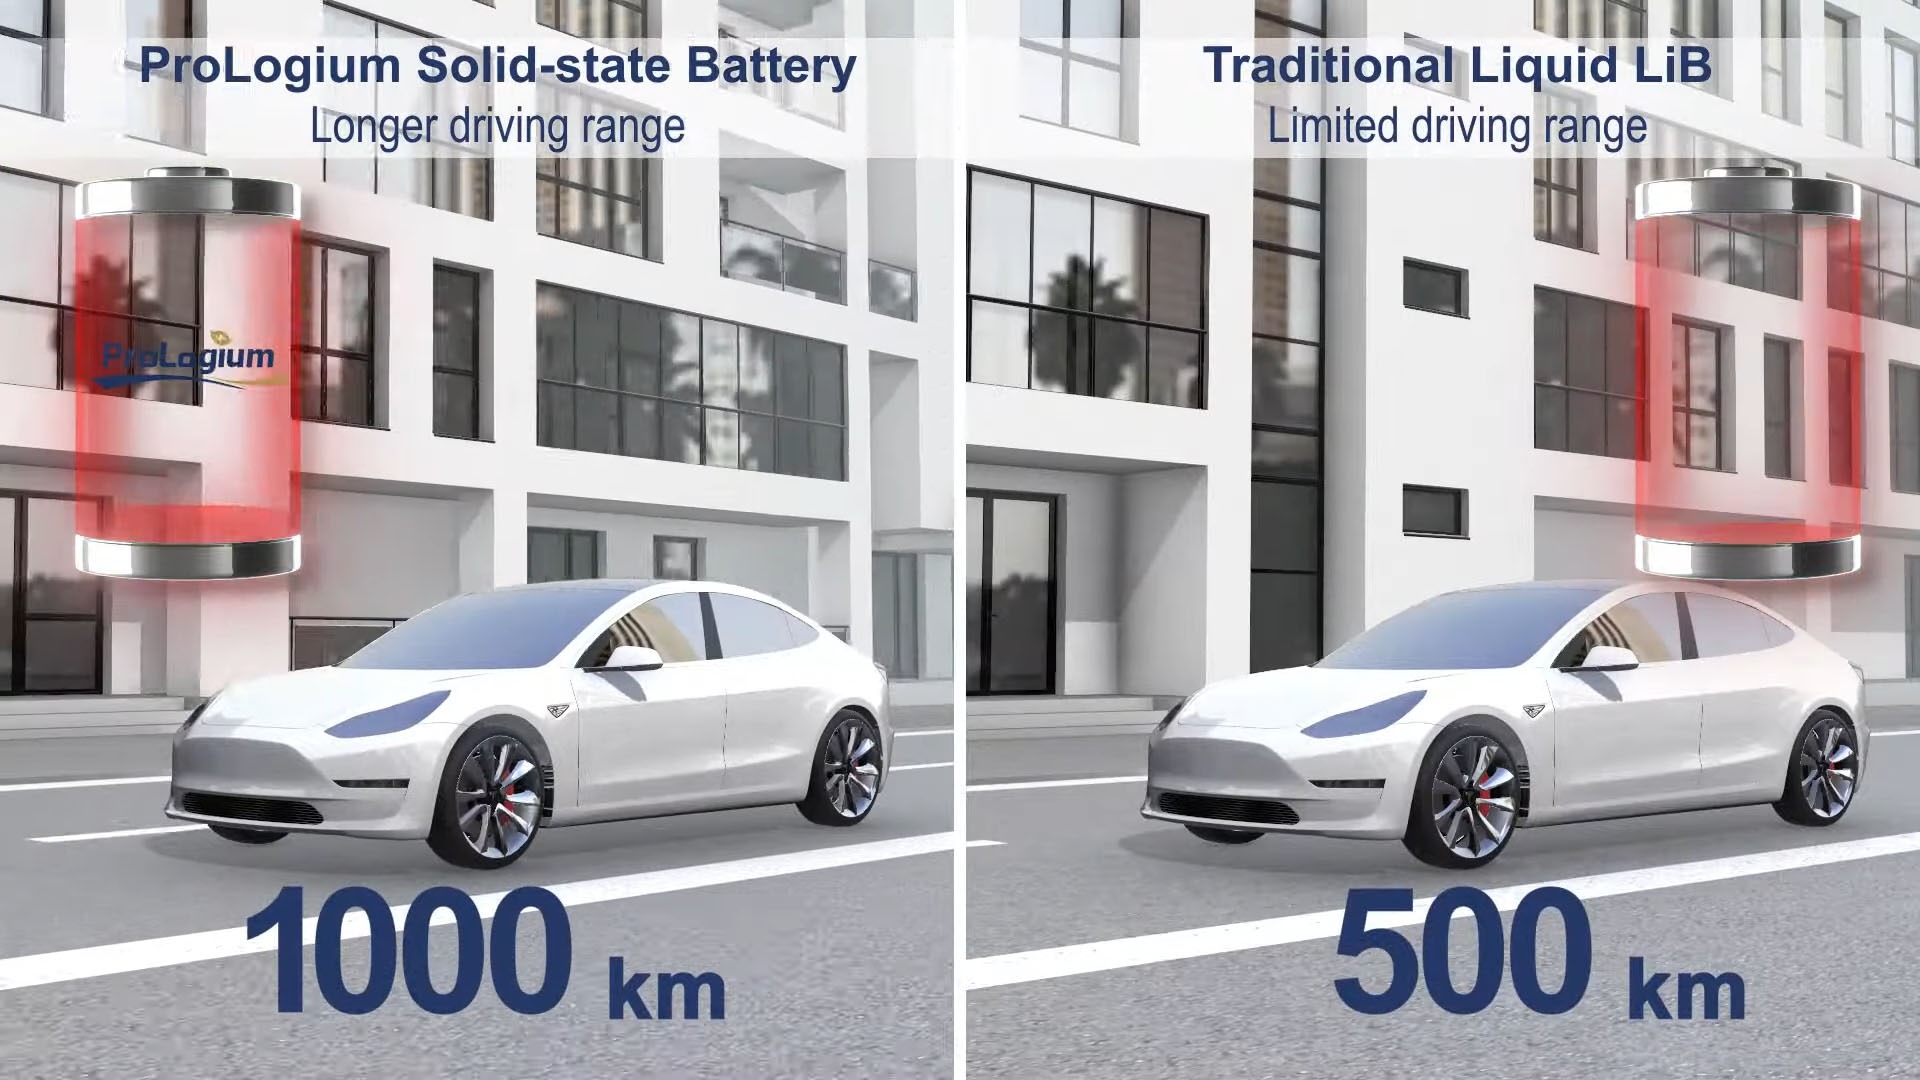
Achieving cost parity with liquid electrolyte cells—historically benchmarked at sub-$100 per kilowatt-hour (kWh) at the pack level—requires a ruthless optimization of materials science, factory footprint efficiency, and scrap rate management. Solid-state architectures inherently simplify cell construction by eliminating heavy thermal management systems, heavy containment modules, and expensive liquid electrolyte salts.
- Elimination of Ancillary Safety Hardware: Because solid electrolytes are non-flammable, the bulky fire-mitigation barriers, liquid-cooling plates, and heavy structural modules required in traditional EV battery packs can be stripped away, reducing overall vehicle weight and lowering tier-one system costs.
- Cathode and Anode Agnosticism: The advanced manufacturing lines are engineered to accept high-nickel cathodes as well as emerging silicon-composite and lithium-metal anodes, allowing procurement teams to pivot dynamically based on raw material market liquidity and commodity pricing shocks.
- Yield Optimization via Advanced Analytics: The factory floor integrates edge computing and real-time machine-learning inspection systems to identify micro-defects in the solid electrolyte separator before cell assembly, driving scrap rates down from historical double-digit percentages to near-par with mature lithium-ion lines.
Verified Data & Metrics Breakdown
To contextualize the scale and operational parameters of the 12 GWh solid-state initiative against legacy liquid electrolyte manufacturing, the following comparative metrics illustrate the structural evolution currently reshaping the energy storage landscape:
| Metric / Parameter | Legacy Liquid Electrolyte Cells | New 12 GWh Solid-State Facility | Strategic Impact |
|---|---|---|---|
| Design Capacity | Mature (30–100+ GWh per plant) | 12 GWh Initial Rollout | Sufficient for ~150,000 premium EVs |
| Volumetric Energy Density | ~650 – 750 Wh/L | 950 – 1,100 Wh/L | 30-40% range extension without added weight |
| Pack-Level Cost Target | $110 – $130 / kWh (2023 baseline) | Sub-$100 / kWh Parity Target | Removes economic premium for solid-state |
| Thermal Runaway Risk | High (Requires active cooling/vents) | Negligible (Inert solid separator) | Eliminates costly thermal management systems |
| Fast Charging (10-80%) | 18 – 30 minutes | 10 – 12 minutes | Removes primary psychological barrier to EV adoption |
Industry & Market Implications: Winners, Losers, and Capital Allocation
The transition to industrial-scale solid-state manufacturing sends shockwaves through the global automotive supply chain, triggering a profound re-evaluation of enterprise risk mitigation and asset valuation multiples.
Who Wins: The Agility-Focused OEMs and Tech-Forward Suppliers
Automotive original equipment manufacturers (OEMs) that secured early supply agreements and joint-development pacts with solid-state pioneers stand to gain an immediate brand and margin advantage. By offering vehicles with 600-mile ranges, 10-minute charging, and absolute thermal safety, these brands can command premium pricing while simultaneously undercutting competitors on structural pack weight. Furthermore, specialized equipment manufacturers providing high-precision roll-to-roll coaters and atmospheric control systems will experience a surge in infrastructure scalability demand.
Who Loses: Legacy Liquid-Cell Monoliths and Commodity Refiners
Traditional battery cell makers heavily invested in multi-billion-dollar liquid electrolyte facilities face the looming threat of premature technological obsolescence. If cost parity is achieved at scale, capital expenditures sunk into conventional liquid lines risk becoming stranded assets. Additionally, miners heavily reliant on specific liquid-electrolyte-bound chemical formulations must rapidly adapt their refining pipelines to service the purity standards demanded by solid-state ceramic and sulfide separators.
Macroeconomic and Regulatory Impact
From a regulatory standpoint, the arrival of 12 GWh of solid-state capacity aligns seamlessly with tightening government mandates on EV safety, battery recycling, and critical mineral domestic sourcing. Because solid-state cells simplify recycling protocols—avoiding volatile organic solvents—they position manufacturers favorably under emerging regulatory compliance frameworks in both the European Union and North America.
Frequently Asked Questions (People Also Ask)
Frequently Asked Questions
What does achieving cost parity mean for the commercial adoption of solid-state batteries?
Cost parity means that automakers can purchase and integrate solid-state battery cells at price points roughly equivalent to traditional liquid lithium-ion cells (around or below $100/kWh at the pack level). This removes the historical cost penalty that restricted solid-state technology to luxury or aerospace applications, opening the door for mass-market passenger EV deployment.
How does a 12 GWh factory capacity impact the broader EV supply chain?
A 12 GWh capacity is large enough to supply approximately 150,000 to 200,000 long-range electric vehicles annually. It serves as a commercial proof-of-concept that de-risks multi-billion-dollar investments, forcing legacy battery manufacturers to accelerate their own solid-state roadmaps or risk losing market share to agile innovators.
Why are solid-state batteries considered safer than conventional liquid electrolyte cells?
Conventional lithium-ion cells use flammable organic liquid electrolytes that can experience thermal runaway—leading to fires—if punctured, overcharged, or overheated. Solid-state batteries replace this liquid with a solid ceramic, glass, or polymer separator that is inherently non-flammable and stable even under extreme physical stress.
What manufacturing challenges had to be overcome to reach this production milestone?
The primary hurdles involved scaling up continuous roll-to-roll manufacturing processes to produce ultra-thin, defect-free solid separators at high speeds without sacrificing electrochemical performance or structural integrity.
Future Outlook: Milestones to Watch Over the Next 24 Months
As the industry transitions from announcement to execution, institutional investors, supply chain executives, and regulatory bodies must monitor several critical operational milestones over the next two years:
- First-Article Yield Metrics: Independent verification of factory floor scrap rates and consistent throughput velocity at the initial 12 GWh facilities during ramp-up phases.
- Automotive Crash and Durability Certification: Formal publication of third-party safety and cycle-life test results under rigorous automotive environmental extremes (sub-zero temperature performance and high-C-rate fast charging).
- Supply Chain Localization Agreements: Announcements regarding long-term procurement contracts for high-purity solid electrolyte precursors and lithium-metal foils, ensuring insulation from geopolitical supply disruptions.
- Secondary Capital Allocation and Expansion Announcements: Indications of follow-on funding rounds or strategic equity investments from major automotive conglomerates looking to scale capacity from 12 GWh to 50+ GWh by the end of the decade.
The deployment of 12 GWh of solid-state manufacturing capacity is not merely an incremental upgrade in energy storage; it is the definitive crossing of the Rubicon for the electric vehicle industry. As production lines hum to life and cost parity transitions from theory to audited reality, the race for total market dominance in zero-emission mobility has entered its most decisive and capital-intensive chapter.