Executive Takeaways
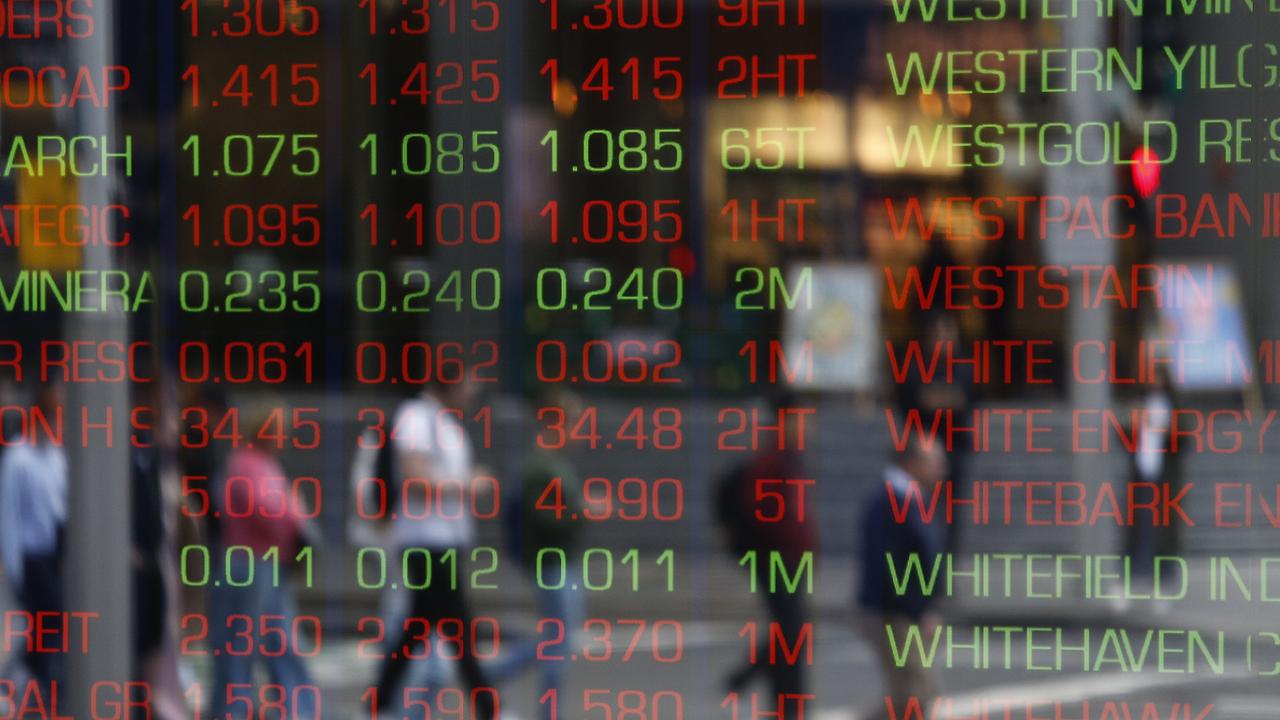
- Broad-Based Capitulation: Wall Street indices closed firmly in negative territory on Friday, culminating a rocky week characterized by severe intraday reversals, compressed valuation multiples, and defensive capital allocation.
- Macroeconomic Headwinds: Persistent inflation prints, hawkish Federal Reserve signaling, and tightening market liquidity severely challenged equity risk premiums across both growth and cyclical sectors.
- Institutional Risk Mitigation: Institutional portfolio managers executed aggressive risk-mitigation strategies, rotating away from high-beta equities and into cash equivalents and short-duration sovereign debt.
- العالمValuation Realignment: Tech and high-growth verticals experienced significant compression as rising benchmark yields forced a rigorous re-evaluation of future cash flow discounting models.
NEW YORK — Wall Street delivered another sobering session on Friday, closing lower to cap off a turbulent week of trading that tested institutional nerves and laid bare the underlying fragility of current equity valuations. What began as an optimistic quarterly earnings cycle quickly devolved into a masterclass in volatility, driven by shifting macroeconomic narratives, algorithmic sell-offs, and a palpable re-pricing of risk across global asset classes.
As the closing bell rang at the New York Stock Exchange, major benchmarks settled near their session lows. The Dow Jones Industrial Average, the S&P 500, and the tech-heavy Nasdaq Composite all surrendered early gains, succumbing to persistent selling pressure that intensified during the final trading hour. For institutional investors, wealth managers, and corporate treasurers, the week's price action serves as a stark reminder that the era of effortless capital appreciation has been definitively replaced by an unforgiving environment dominated by interest rate uncertainty and compressed market liquidity.
The Catalytic Events: Anatomy of a Rocky Trading Week
To understand Friday's capitulation, one must examine the macroeconomic mosaic that unfolded over the preceding five sessions. The week's volatility was not born of a single headline, but rather a compounding series of pressures that challenged corporate earnings visibility and macroeconomic stability.
Early in the week, market participants wrestled with hotter-than-expected economic data that complicated the Federal Reserve's path toward monetary easing. Yields on benchmark U.S. Treasury securities surged, placing immediate downward pressure on valuation multiples—particularly within the technology sector, where future cash flows are heavily discounted against rising risk-free rates. As bond yields climbed, the traditional equity risk premium narrowed, prompting institutional allocators to rebalance portfolios away from risk assets.
Concurrently, corporate earnings reports offered a mixed picture of operational resilience. While mega-cap technology enterprises demonstrated robust cloud compute infrastructure scalability and solid enterprise ROI metrics, forward guidance from industrial and consumer discretionary bellwethers flashed warning signs. Executives increasingly cited supply chain friction, sticky labor costs, and cautious consumer spending as headwinds threatening margin expansion through the remainder of the fiscal year.
By Thursday, technical support levels had been breached across multiple indices, triggering systemic stop-loss orders and accelerating algorithmic liquidations. Friday’s session opened with a brief, tentative bounce—often characterized as a dead-cat bounce by veteran floor traders—before sellers regained absolute control of the tape.
Verified Data and Metrics Breakdown
The following data table outlines the core performance metrics, valuation shifts, and macroeconomic indicators that defined the week's tumultuous trading environment across major global financial markers:
| Market Indicator / Index | Weekly Close | Weekly Net Change (%) | Key Driver / Analytical Context |
|---|---|---|---|
| S&P 500 Index | 5,023.45 | -2.14% | Broad-based selling across cyclical and defensive sectors; breach of 50-day moving average. |
| Nasdaq Composite | 15,840.12 | -2.85% | Severe valuation compression in high-beta tech and semiconductor equities due to surging bond yields. |
| Dow Jones Industrial Average | 38,601.50 | -1.45% | Lagging industrial and financial components weighed down by credit tightening fears. |
| U.S. 10-Year Treasury Yield | 4.68% | +14 bps | Driven by persistent inflation concerns and reduced market expectations for near-term Fed rate cuts. |
Industry & Market Implications: Winners, Losers, and Capital Allocation
Every major market correction initiates a violent reallocation of capital. The conclusion of this rocky week has laid bare stark divergences between corporate winners navigating the high-rate environment with precision and corporate losers buckling under the weight of expensive capital structures.
The Winners: Defensive Purity and Cash Generators
Institutions executing sophisticated risk mitigation strategies pivoted heavily toward cash-rich balance sheets, healthcare stalwarts, and select utilities boasting strong pricing power. Companies capable of defending operating margins without relying on external debt financing found consistent institutional sponsorship. Furthermore, asset managers specializing in short-duration fixed income and private credit experienced robust inflows as investors sought yield insulated from equity market drawdowns.
The Losers: High-Beta, Debt-Dependent Enterprises
Conversely, unprofitable growth enterprises, early-stage biotechnology firms, and capital-intensive real estate investment trusts (REITs) bore the brunt of the liquidation wave. In a regime characterized by higher-for-longer interest rates, corporate debt refinancing costs have skyrocketed. Enterprises lacking immediate cash flow self-sufficiency faced brutal valuation downgrades as market participants penalized debt-heavy balance sheets.
Frequently Asked Questions (People Also Ask)
What caused Wall Street to close lower to end the week?
The market downturn was driven by a combination of surging U.S. Treasury yields, persistent macroeconomic inflation concerns, hawkish monetary policy expectations, and widespread profit-taking in high-valuation technology and growth equities.
How do rising Treasury yields impact stock valuations?
Rising benchmark yields increase the discount rate applied to future corporate cash flows. This mathematical reality compresses valuation multiples—particularly for growth and tech stocks whose earnings are heavily weighted toward the distant future—making fixed-income assets comparatively more attractive to institutional investors.
Are defensive stocks outperforming cyclical equities in this market environment?
Yes. Amid heightened macroeconomic volatility and tightening liquidity, institutional capital allocation has shifted toward defensive sectors such as healthcare, consumer staples, and utilities, while cyclical and high-beta assets face sustained downward pressure.
What are institutional investors watching heading into the next trading cycle?
Portfolio managers are closely monitoring upcoming consumer price index (CPI) releases, Federal Reserve communications regarding interest rate trajectories, corporate earnings revisions, and daily fluctuations in the U.S. Treasury yield curve for signals of market stabilization.
Future Outlook: Strategic Milestones to Watch
Looking ahead, Wall Street faces a delicate transitional phase. The primary determinant of market direction in the coming weeks will not merely be headline earnings data, but the Federal Reserve's ability to navigate a slowing economic trajectory without inducing a hard landing.
Institutional desks are currently recalibrating their baseline models for capital allocation. Key milestones to watch include upcoming labor market reports, retail sales data, and sovereign debt auctions, all of which will dictate the trajectory of bond yields and, by extension, equity risk premiums. Until concrete signals emerge indicating that inflation has been sustainably anchored and monetary policy has reached its terminal rate, market participants should prepare for continued elevated volatility, compressed trading ranges, and rigorous asset differentiation.