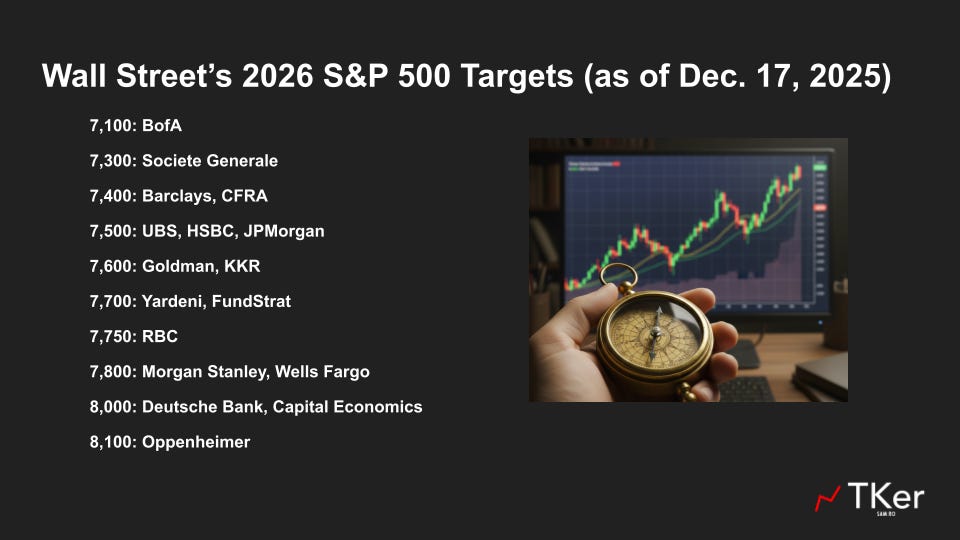
As trading desks across Lower Manhattan and the City of London finalize their year-end positioning for 2026, a striking dichotomy defines institutional sentiment. Quantitative models and chief investment officers are projecting another fundamentally sound year for global equities, buoyed by resilient corporate earnings and a broadening macroeconomic expansion. Yet, beneath the veneer of consensus optimism, senior risk officers, credit strategists, and investigative desks are tracking a compounding matrix of structural fragilities. From the hyper-capitalized infrastructure demands of generative artificial intelligence to impending fiscal cliffs and regulatory shifts, the market entering 2026 is walking a narrow path between historic highs and unprecedented systemic exposure.
Executive Takeaways
- Broadening Earnings Expansion: Wall Street consensus forecasts suggest that profit growth in 2026 will transition away from pure Mega-Cap tech monopolies into cyclical, industrial, and financial sectors.
- The Infrastructure Bottleneck: The continuation of the AI-driven market rally hinges entirely on enterprise ROI, capital expenditure sustainability, and the unyielding elasticity of cloud compute architecture.
- Fiscal and Regulatory Catalysts: Debates over the expiration and renewal of major tax legislation, coupled with evolving antitrust scrutiny, introduce significant volatility vectors for corporate cash flows.
- Risk Mitigation Imperative: As valuation multiples remain elevated relative to historical means, institutional portfolios are pivoting toward rigorous risk mitigation and dynamic capital allocation strategies.
The Macroeconomic Foundation: Why Wall Street Remains Bullish on 2026
To understand why institutional asset managers are maintaining a constructive stance on equities heading into 2026, one must first examine the resilience displayed by the broader economy through the mid-2020s. Despite aggressive monetary tightening cycles by global central banks, corporate balance sheets have largely adapted. Interest rate stabilization has allowed corporate treasurers to term out debt maturities, insulating firms from immediate refinancing shocks.
Furthermore, macroeconomic data points toward a "soft landing" narrative that has consistently defied bearish forecasters. Labor markets have cooled in an orderly fashion, consumer spending has proven remarkably sticky, and productivity gains—accelerated by early-stage enterprise automation—have kept corporate operating margins near historic peaks. Equity strategists at major wirehouses argue that these fundamentals create a durable floor for stock prices, preventing any severe valuation collapse even as monetary policy remains restrictive by historical standards.
However, this macro stability has bred a dangerous complacency. Asset prices are increasingly pricing in a flawless execution scenario where corporate America successfully navigates geopolitical friction, supply chain realignments, and shifting labor dynamics without suffering a compression in return on equity (ROE).
Can the AI Rally Last? The Capital Expenditure Reckoning
No single variable dictates the trajectory of the 2026 equity market more than the artificial intelligence trade. For the past three years, a handful of hyperscalers and semiconductor pioneers have driven the lion's share of market returns. As we cross into 2026, the foundational question facing portfolio managers is no longer whether AI is technologically viable, but whether the staggering capital expenditure (CapEx) required to sustain it can generate an acceptable enterprise ROI.
Infrastructure scalability has emerged as the ultimate bottleneck. Building, powering, and cooling next-generation data centers requires capital outlays that dwarf historical telecommunications and utility investments. Cloud compute architecture is pushing against physical limits, forcing technology conglomerates to secure proprietary energy sources, including nuclear and advanced renewables, just to keep pace with algorithmic training demands.
The ROI Imperative
Wall Street's tolerance for speculative infrastructure spending is wearing thin. Institutional investors are shifting from a growth-at-all-costs mindset to demanding rigorous proof of operational efficiency and revenue monetization. If enterprise software deployments and AI-driven productivity tools fail to demonstrate tangible bottom-line impact by mid-2026, a sharp rotation out of high-multiple technology assets could trigger a broader market drawdown.
Profit Growth: The Great Broadening vs. Margin Compression
A central pillar of the bull case for 2026 is the expected "broadening" of earnings growth. While the previous cycle was characterized by extreme concentration—where the top tier of mega-cap stocks accounted for the vast majority of S&P 500 earnings expansion—quantitative models indicate that earnings breadth is improving.
Sectors such as industrials, healthcare, financials, and materials are projected to capture larger shares of aggregate profit growth as supply chains normalize and industrial policy legislation takes full effect. This rotation is viewed by portfolio strategists as a healthy maturation of the bull market, reducing systemic vulnerability to a single-sector shock.
Yet, maintaining these profit margins will not be trivial. Wage pressures, persistent insurance and compliance costs, and the higher cost of capital compared to the ultra-low-interest-rate era are squeezing corporate operating models. Companies lacking genuine pricing power face severe earnings revisions if consumer demand softens even marginally.
Legislative Catalysts: Tax Policy and Regulatory Headwinds
As legislative calendars fill up in 2026, Washington D.C. remains a primary source of both potential tailwinds and severe headwinds. The ongoing debate surrounding the extension or restructuring of landmark tax legislation is commanding the attention of corporate tax directors and institutional equity research desks alike.
A favorable tax extension framework could provide an immediate boost to corporate cash flows, triggering accelerated share buyback programs and domestic capital investment. Conversely, any sudden shift toward higher corporate statutory rates, minimum book-tax rules, or targeted industry levies would necessitate an immediate downward recalibration of consensus price targets.
Simultaneously, regulatory compliance and antitrust enforcement are casting a long shadow over corporate deal-making. Mergers and acquisitions (M&A) activity, which traditionally serves as a vital catalyst for equity valuations, faces rigorous scrutiny from domestic and international competition authorities. Strategic buyers are being forced to navigate protracted legal reviews, delaying synergy realization and dampening animal spirits in the corporate suite.
Verified Data & Metrics Breakdown
To contextualize the macroeconomic and market dynamics shaping the 2026 financial landscape, the following comparative matrix outlines key institutional forecasts, valuation metrics, and risk factors:
| Metric / Indicator | Current Baseline (2025) | Wall Street Consensus (2026) | Underlying Risk Factor |
|---|---|---|---|
| S&P 500 Forward P/E Ratio | ~21.5x | Projected stable at 20x–22x | Vulnerable to multiple compression if bond yields spike. |
| AI Infrastructure CapEx | Record highs (~$200B+ hyperscale) | Expected 15-20% YoY growth | Declining marginal enterprise ROI. |
| Corporate Earnings Growth | ~9% YoY | Broadening to 11-13% YoY | Margin pressure from labor and financing costs. |
| Market Liquidity & Volatility | Subdued VIX (12-15 range) | Expected normalization toward 18-20 | Sudden macro shocks or geopolitical friction. |
Industry & Market Implications: Winners and Losers
As institutional capital is reallocated for the 2026 fiscal year, the divergence between market winners and losers is becoming sharper. Understanding these shifts is critical for asset allocators seeking alpha in an increasingly complex environment.
The Winners
- Energy & Utility Providers: The unquenchable power demands of data centers and artificial intelligence compute clusters position regulated utilities and alternative energy developers as indispensable infrastructure partners.
- Industrial Automation & Advanced Manufacturing: Companies providing hard-tech solutions, robotics, and supply chain reshoring technology are capturing robust enterprise spending as firms prioritize operational independence.
- Select Financial Institutions: Well-capitalized banks and alternative asset managers benefiting from a stabilization in credit markets and a gradual revival of advisory fees stand to gain from the earnings broadening trend.
The Losers
- Legacy Software Providers Lacking AI Integration: Software-as-a-Service (SaaS) businesses that fail to demonstrate proprietary AI integration face severe customer churn and pricing erosion.
- Over-Leveraged Real Estate & Entities: Commercial real estate sub-sectors still grappling with structural shifts in occupancy and higher debt refinancing rates will continue to experience asset write-downs.
- Low-Margin Consumer Discretionary Brands: Retailers and consumer brands lacking distinct pricing power will bear the brunt of wage inflation and discerning consumer spending habits.
Frequently Asked Questions (People Also Ask)
What are the primary catalysts driving Wall Street’s positive outlook for 2026 equities?
Institutional optimism for 2026 is primarily anchored in resilient corporate earnings, a broadening of profit growth beyond mega-cap technology into cyclicals and industrials, stabilizing interest rates, and ongoing productivity enhancements driven by enterprise automation and artificial intelligence.
Why are risk analysts warning that "risks are growing" despite strong market forecasts?
While headline equity indices remain near highs, risk desks point to elevated valuation multiples, astronomical and unproven capital expenditure in AI infrastructure, potential legislative and tax policy changes, and the persistent vulnerability of corporate profit margins to labor and financing costs.
How is the AI rally evolving as we head into 2026?
The AI market narrative is shifting from a speculative infrastructure build-out phase to a rigorous performance test focused on enterprise ROI. Investors are demanding concrete proof that massive cloud compute investments and data center expansions are translating directly into sustainable corporate revenue and operational efficiencies.
What role do tax legislation and regulatory policies play in 2026 stock market projections?
Legislative debates surrounding the extension of major tax provisions represent a major fork in the road for corporate cash flows and share buyback capacity. Simultaneously, heightened antitrust scrutiny and regulatory compliance requirements continue to complicate corporate mergers, acquisitions, and strategic capital allocation.
Future Outlook: Strategic Milestones to Watch in 2026
As the financial markets navigate the terrain of 2026, success for institutional investors and corporate executives alike will depend on maintaining a disciplined, risk-adjusted framework. The era of passive, indiscriminate buying is giving way to an environment where stock selection, balance sheet strength, and verifiable cash generation reign supreme.
Key milestones to monitor include quarterly corporate earnings calls regarding AI monetization metrics, legislative developments concerning federal tax renewals, and central bank liquidity adjustments in response to sticky inflation prints. While the foundational momentum for a solid market performance remains intact, the expanding margin of error demands constant vigilance, agile capital allocation, and rigorous risk mitigation.