Executive Takeaways
- Federal Reserve Stance: Chair Jerome Powell left benchmark interest rates steady while withholding definitive signals on future easing, triggering a wave of volatility across equities and fixed income.
- The Bessent Effect: Treasury Secretary Scott Bessent’s aggressive fiscal commentary and currency posture catalyzed an acute dollar advance, compressing profit margins for multinational corporations reliant on international revenue streams.
- Valuation Compression: Institutional investors are rapidly reassessing valuation multiples, shifting capital allocation strategies away from high-beta growth assets toward resilient, high-liquidity safe havens.
- Global Spillover: Emerging market currencies and foreign sovereign debt face renewed pressure as rising US yields and a dominant greenback alter global risk mitigation frameworks.
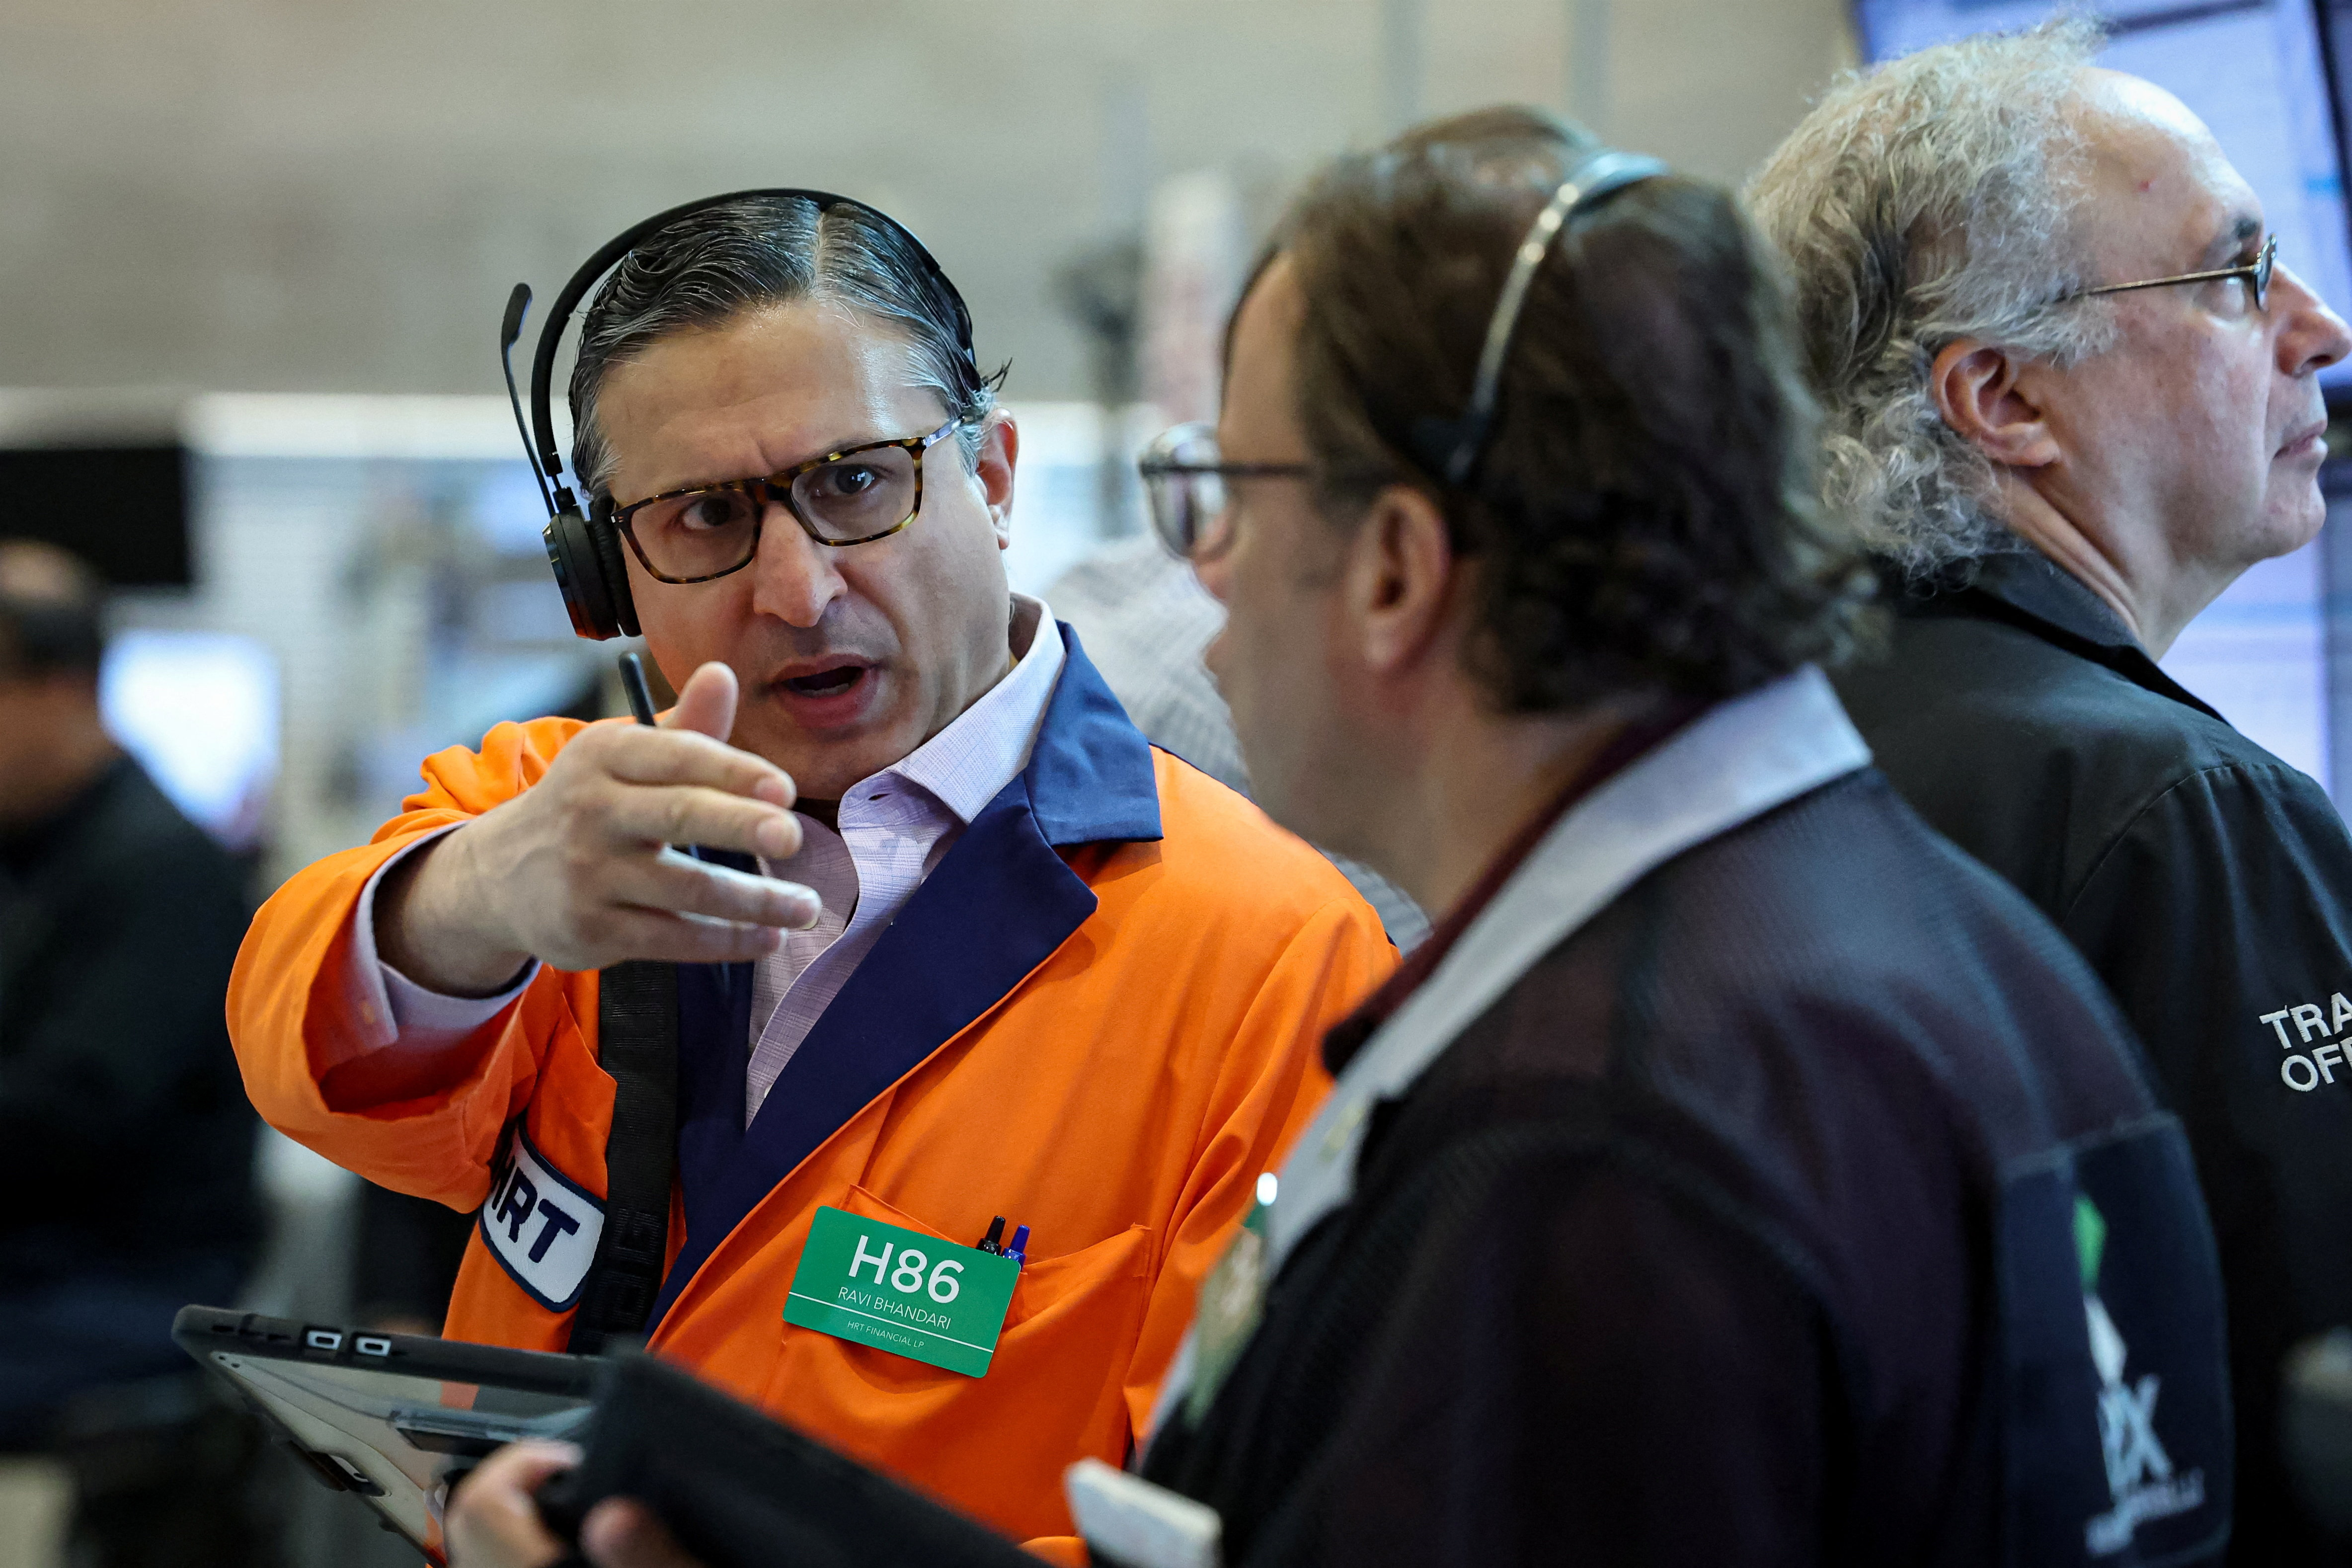
Global financial markets shifted into a defensive posture on January 28, 2026, as a powerful confluence of monetary policy stagnation and decisive fiscal maneuvering abruptly halted the protracted equity market rally. Wall Street trading desks labored under mounting pressure following the Federal Reserve’s widely anticipated decision to hold benchmark borrowing costs steady. Compounding the monetary backdrop, fresh policy signals from Treasury Secretary Scott Bessent ignited a violent upward trajectory for the US dollar, redefining risk parameters across asset classes.
For institutional asset managers, corporate treasurers, and algorithmic trading desks, the sudden evaporation of market momentum underscores a fragile macroeconomic ecosystem. As equity indices waver and currency volatility spikes, corporate leaders must urgently review their capital allocation frameworks, debt-servicing schedules, and currency hedging strategies to navigate an increasingly complex economic landscape.
The Monetary Impasse: Fed Holds Ground Amid Persistent Uncertainty
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
The Federal Open Market Committee’s (FOMC) consensus decision to maintain the federal funds rate within its established target range was largely priced into derivatives markets prior to the announcement. However, it was Federal Reserve Chair Jerome Powell’s recalcitrant press conference tone that ultimately broke the market's bullish stride. Refusing to hand institutional investors the dovish roadmap they coveted, Powell emphasized persistent economic resilience and a data-dependent trajectory that leaves open the possibility of prolonged restrictive monetary policy.
Bond yields reacted swiftly to the central bank's refusal to signal imminent rate cuts. Short-end Treasuries experienced renewed selling pressure as traders pushed back expectations for monetary easing. This policy stalemate directly impacts enterprise ROI calculations across capital-intensive sectors, where the cost of debt refinancing remains elevated. Chief financial officers are discovering that historical liquidity cushions are no longer sufficient to offset sustained high borrowing costs, forcing a widespread pivot toward aggressive operational risk mitigation.
Furthermore, fixed-income portfolios endured acute crosscurrents as the term premium expanded. Institutional asset allocators who had positioned themselves for a smooth descent in interest rates found themselves caught off guard, triggering an immediate portfolio rebalancing cycle that bled liquidity out of high-flying equity sectors.
The Bessent Catalyst: Fueling the Greenback’s Resurgence

While the Federal Reserve provided the baseline for market indecision, it was Treasury Secretary Scott Bessent’s recent policy directives that supplied the kinetic energy for the foreign exchange market. Bessent’s public framing of a pragmatic yet unapologetically strong-dollar framework caught international currency traders off guard, sparking a aggressive short-covering rally in the greenback against virtually all G10 and emerging-market counterparts.
A surging US dollar acts as a double-edged sword for the domestic and global economy. On one hand, it lowers import costs and helps anchor domestic price stability. On the other hand, it deals an immediate blow to the earnings power of US multinational corporations. Enterprises operating across technology, industrial manufacturing, and consumer staples rely heavily on foreign revenue translation. As the dollar strengthens, those overseas cash flows translate into fewer dollars, directly compressing earnings-per-share (EPS) projections and challenging lofty equity valuation multiples.
Moreover, the Bessent-fueled dollar advance created severe liquidity strains abroad. Foreign central banks are finding themselves forced to defend their local currencies against capital flight, raising domestic interest rates precisely when their economies require stimulus. This divergence in monetary policy pathways magnifies systemic vulnerabilities within global supply chains and sovereign debt markets alike.
Market Metrics & Valuation Shifts
The market's visceral reaction to the dual headwinds of Fed inaction and dollar strength is clearly documented in key asset performance metrics. Institutional desks are aggressively monitoring structural shifts across equity risk premiums and currency valuations.
| Asset Class / Metric | Pre-Announcement Position | Post-Announcement Reaction | Core Market Implication |
|---|---|---|---|
| S&P 500 Index | Testing record highs, bullish momentum | Wavering, sharp intraday reversal | Valuation multiple compression |
| US Dollar Index (DXY) | Consolidating in a tight range | Sharp upward breakout | Headwinds for multinational earnings |
| 2-Year Treasury Yield | Priced for near-term easing | Skewed higher on sticky rate outlook | Elevated corporate debt refinancing costs |
| Emerging Market Currencies | Stable against steady greenback | Broad-based depreciation pressure | Tightened international market liquidity |
Industry & Market Implications: Winners and Losers
The sudden stall in the stock rally is not impacting all sectors equally. Sophisticated investors are executing aggressive sector rotation strategies, distinguishing between enterprises vulnerable to currency headwinds and those positioned to capitalize on sustained macroeconomic tightness.
The Losers: Multinationals and High-Beta Growth
Large-cap technology conglomerates, industrial exporters, and consumer goods giants with heavy international exposure face immediate margin compression. As the dollar climbs under Bessent's policy framework, foreign revenues translate into lower domestic profits. Furthermore, unprofitable growth companies and speculative tech ventures that depend heavily on low-cost liquidity and aggressive multiple expansion are experiencing sharp capital outflows as investors favor cash-generative value stocks.
The Winners: Domestic Value and Financial Services
Conversely, domestically focused small-cap enterprises—proxied by the Russell 2000—stand to benefit from insulation against foreign currency volatility, provided their debt structures are insulated from high short-term rates. Major financial institutions and asset managers are also adapting successfully; higher-for-longer interest rate regimes continue to support net interest margins, offering robust cash generation despite broader market consolidation.
Frequently Asked Questions (People Also Answered)
Why did the Federal Reserve's decision to hold rates steady cause stocks to waver?
While a rate hold was largely expected, Federal Reserve Chair Jerome Powell refrained from offering dovish signals regarding future monetary easing. This dashed investor hopes for an imminent pivot toward lower borrowing costs, forcing markets to price in a "higher-for-longer" interest rate environment that dampens future corporate earnings projections and compresses equity valuation multiples.
How does Treasury Secretary Scott Bessent's policy impact the US dollar?
Treasury Secretary Scott Bessent’s fiscal commentary and economic positioning have signaled strong support for structural currency strength and fiscal discipline. This stance has driven aggressive institutional capital flows into greenback-denominated assets, sparking a sharp advance in the US Dollar Index (DXY) and altering global currency dynamics.
What are the primary risks of a surging US dollar for global corporations?
A rapidly appreciating dollar creates significant head winds for multinational corporations by reducing the dollar value of international revenues. It also tightens global financial conditions, increases debt-servicing costs for emerging market economies holding US dollar-denominated debt, and intensifies competitive pressures for international exporters.
How should institutional investors adjust their capital allocation strategies in this environment?
Institutional allocators are increasingly prioritizing risk mitigation by rotating out of high-beta growth stocks into cash-generative, domestically oriented value assets. Emphasizing robust balance sheets, manageable debt maturity profiles, and effective currency hedging programs is critical to navigating ongoing market volatility.
Future Outlook: Navigating the Next Macroeconomic Inflection Point
As the market digests the dual impact of the Fed's policy stance and the Bessent-driven dollar rally, the coming weeks will test the resilience of the broader economic expansion. Key milestones to monitor include upcoming labor market prints, inflation updates, and incoming fiscal policy proposals from Washington. If macroeconomic data continues to run hotter than anticipated, the Federal Reserve may be forced to keep policy restrictive well into the second half of the year, cementing a new paradigm for asset valuation.
For corporate executives and institutional investors, complacency is no longer an option. Success in this environment requires rigorous infrastructure scalability, disciplined capital allocation, and proactive regulatory and currency compliance frameworks. Navigating the current liquidity tightening will separate resilient market leaders from vulnerable enterprises as the global financial system adapts to a stronger dollar and persistent monetary discipline.