Executive Takeaways
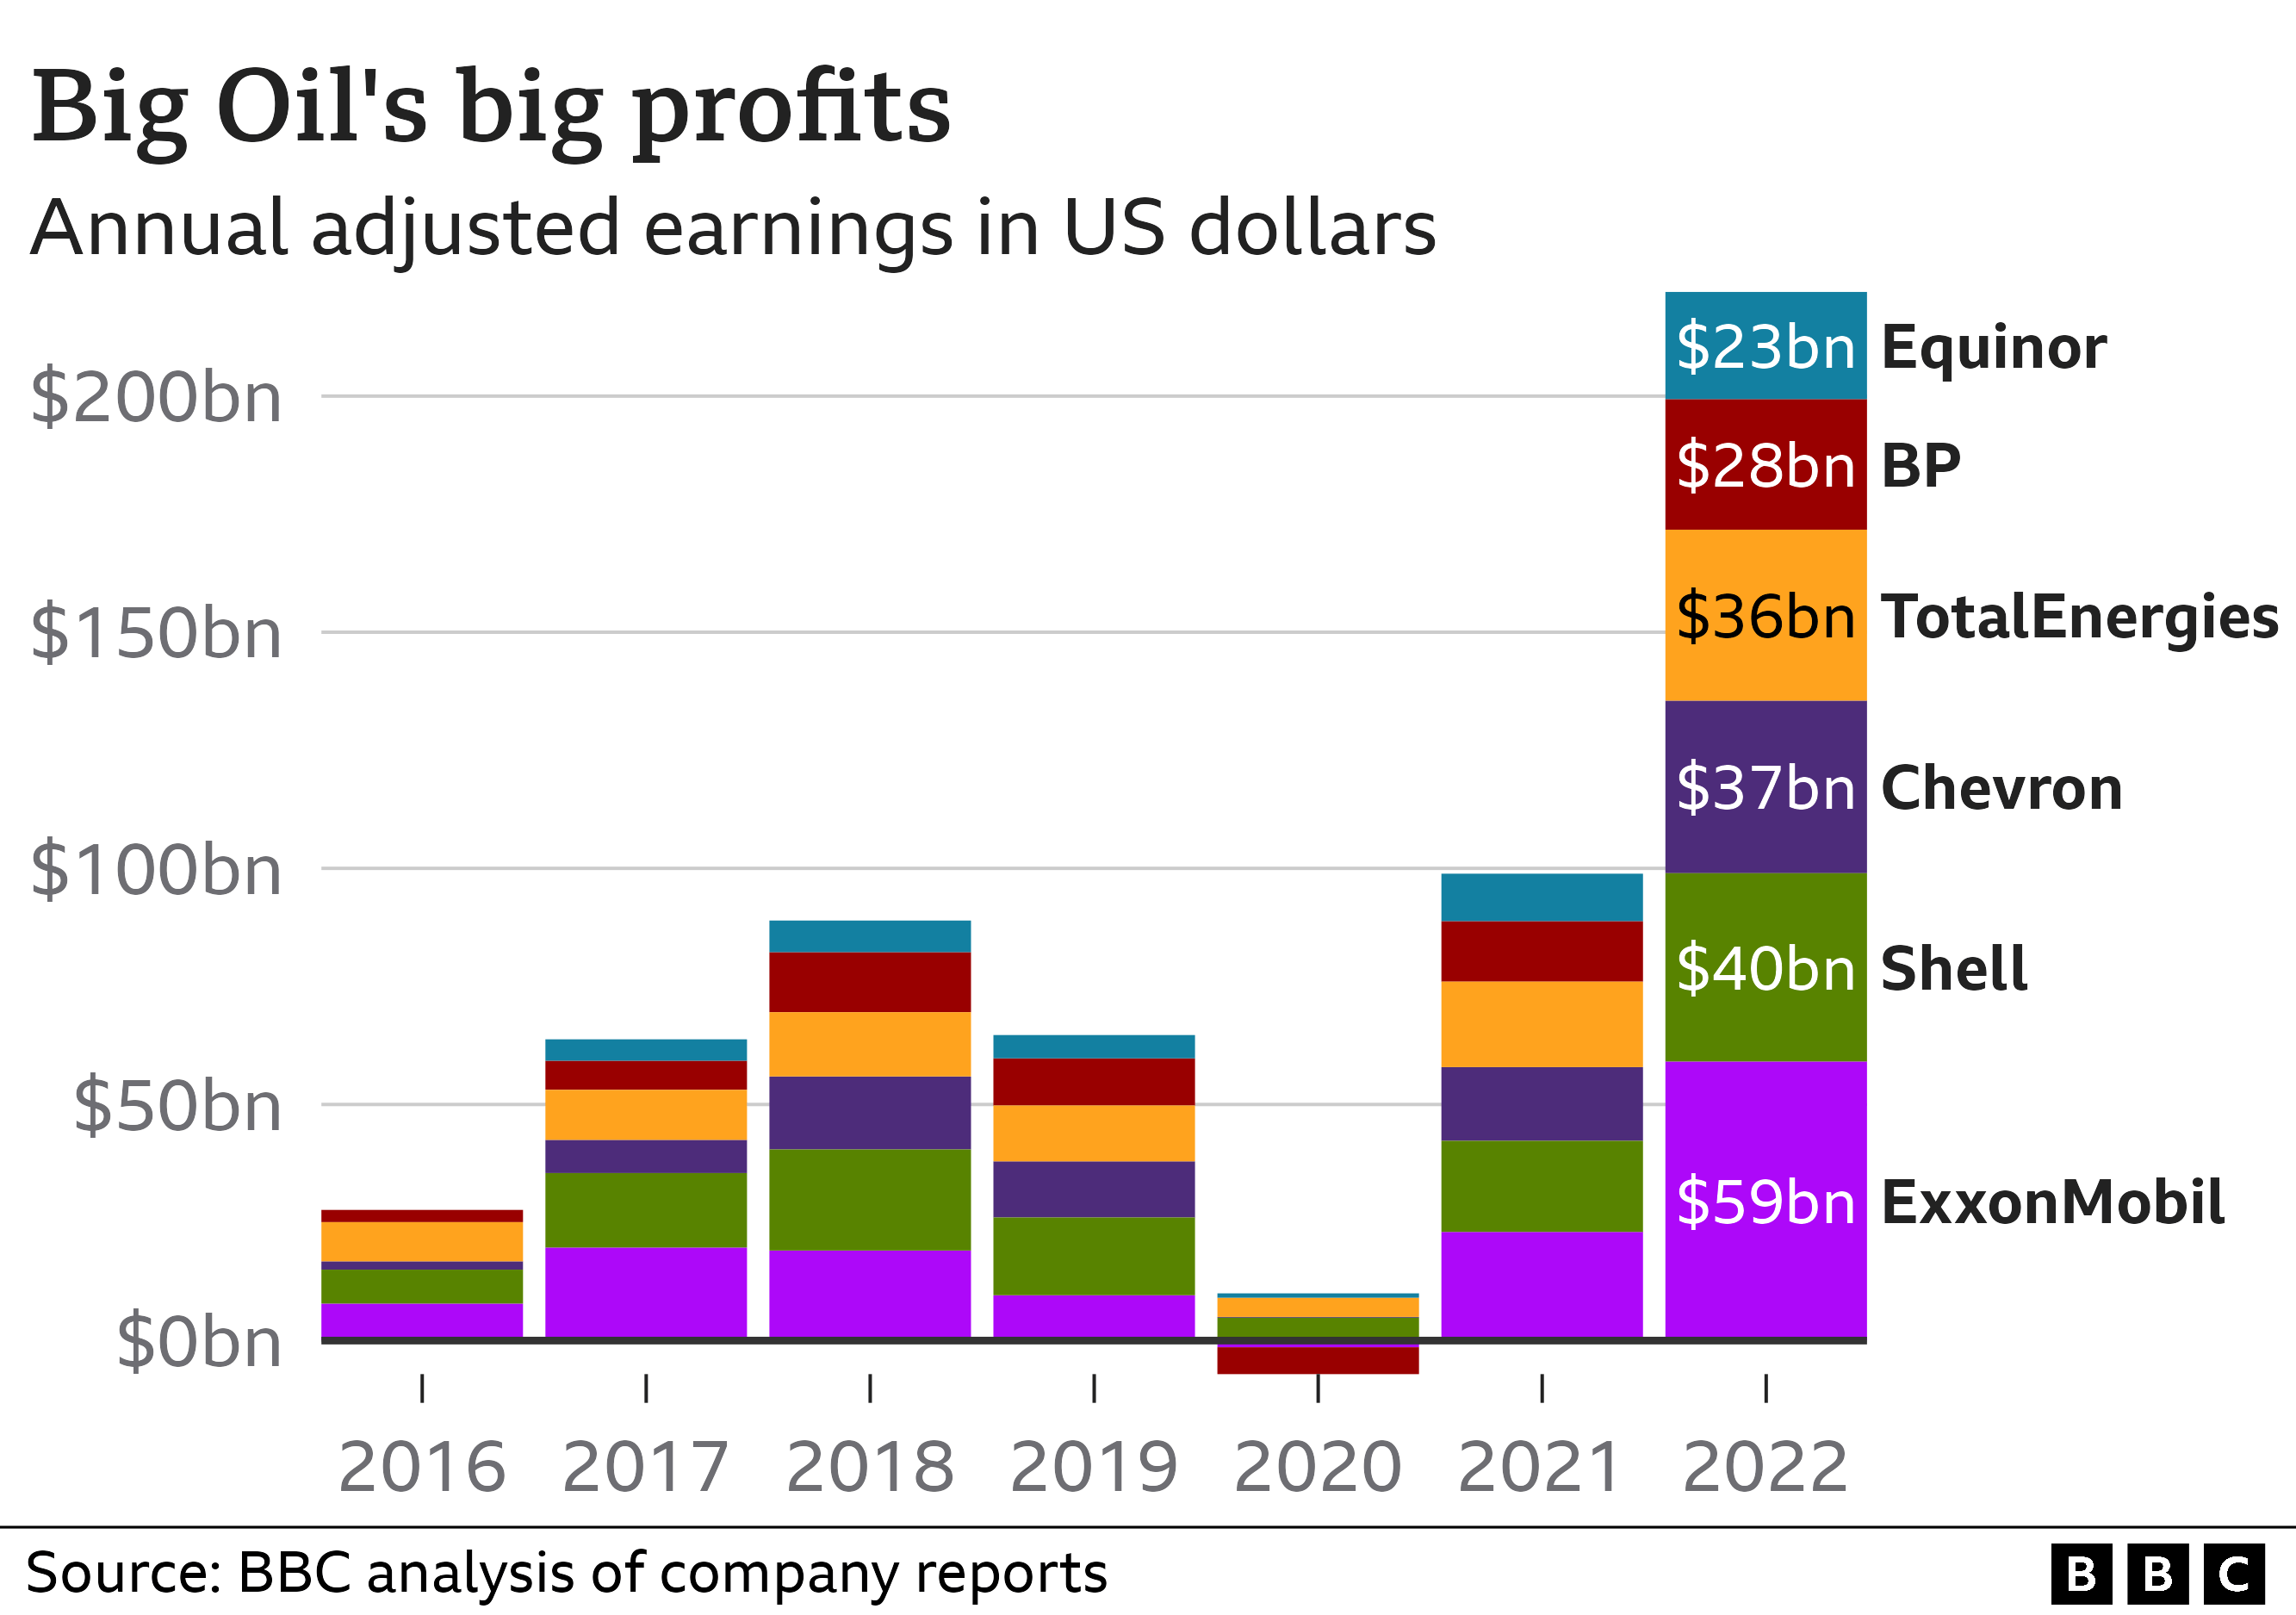
- The Refining Paradox: Despite public attacks from political figures like Donald Trump over soaring corporate profits, major integrated oil companies saw their downstream refining margins explode to historic highs due to a structural mismatch in global processing capacity.
- Capital Allocation Shifts: Rather than aggressively expanding domestic infrastructure scalability, major energy enterprises redirected windfall earnings toward aggressive share buybacks, enhanced enterprise ROI, and strategic risk mitigation.
- Valuation Multiples: Downstream assets transitioned from cash-draining regulatory liabilities into high-margin profit engines, fundamentally altering valuation multiples across the entire energy sector.
- Regulatory Compliance Pressures: Stricter environmental mandates and complex regulatory compliance paradoxically constrained new refinery construction, creating an artificial supply moat that protected incumbent profit margins.
For years, populist political rhetoric has targeted the sprawling balance sheets of the world’s largest oil conglomerates, framing record-shattering margins as an affront to consumers at the pump. Yet, a deep dive into corporate financial disclosures, regulatory filings, and real-time market data reveals a striking paradox: even as political pressure mounted and public scrutiny reached a boiling point, the financial architecture of Big Oil underwent a quiet, highly lucrative structural evolution. The real engine driving these unprecedented windfalls was not simply the spot price of Brent or West Texas Intermediate (WTI) crude, but a historic dislocation within downstream refining earnings.
To understand how refining margins surged to unprecedented heights in the wake of high-profile political interventions, one must examine the intersection of geopolitical shocks, post-pandemic demand elasticity, and deliberate capital allocation strategies. This investigative report breaks down the financial mechanics, market adjustments, and long-term economic implications of an energy sector transformation that reshaped corporate balance sheets worldwide.
The Catalytic Disconnect: Rhetoric Versus Refining Economics
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
When political leaders publicly upbraid energy executives for capitalizing on high energy prices, the public narrative typically focuses on upstream exploration and extraction—the raw crude pulled from the earth. However, the operational reality of multinational energy enterprises relies heavily on the downstream sector: the complex chemical conversion of raw hydrocarbons into gasoline, diesel, jet fuel, and petrochemical feedstocks.
The inflection point arrived during the post-pandemic economic reopening, compounded by the profound supply-chain realignments triggered by international sanctions on Russian petroleum exports. While upstream production faced political headwinds and calls for increased output, the global refining network experienced a historic bottleneck. Years of underinvestment, accelerated by ESG (Environmental, Social, and Governance) pressures and anticipated long-term demand destruction, had forced the permanent closure of millions of barrels per day of global refining capacity.
When demand roared back, the remaining operational refineries operated near maximum capacity utilization rates. This capacity crunch meant that every barrel of gasoline produced yielded exponentially higher crack spreads—the differential between crude oil prices and the refined products extracted from it. Big Oil’s downstream segments, historically viewed as cyclical, low-margin buffers, suddenly transformed into high-velocity cash generators.
Quantifying the Windfall: Financial Mechanics and Margin Expansion
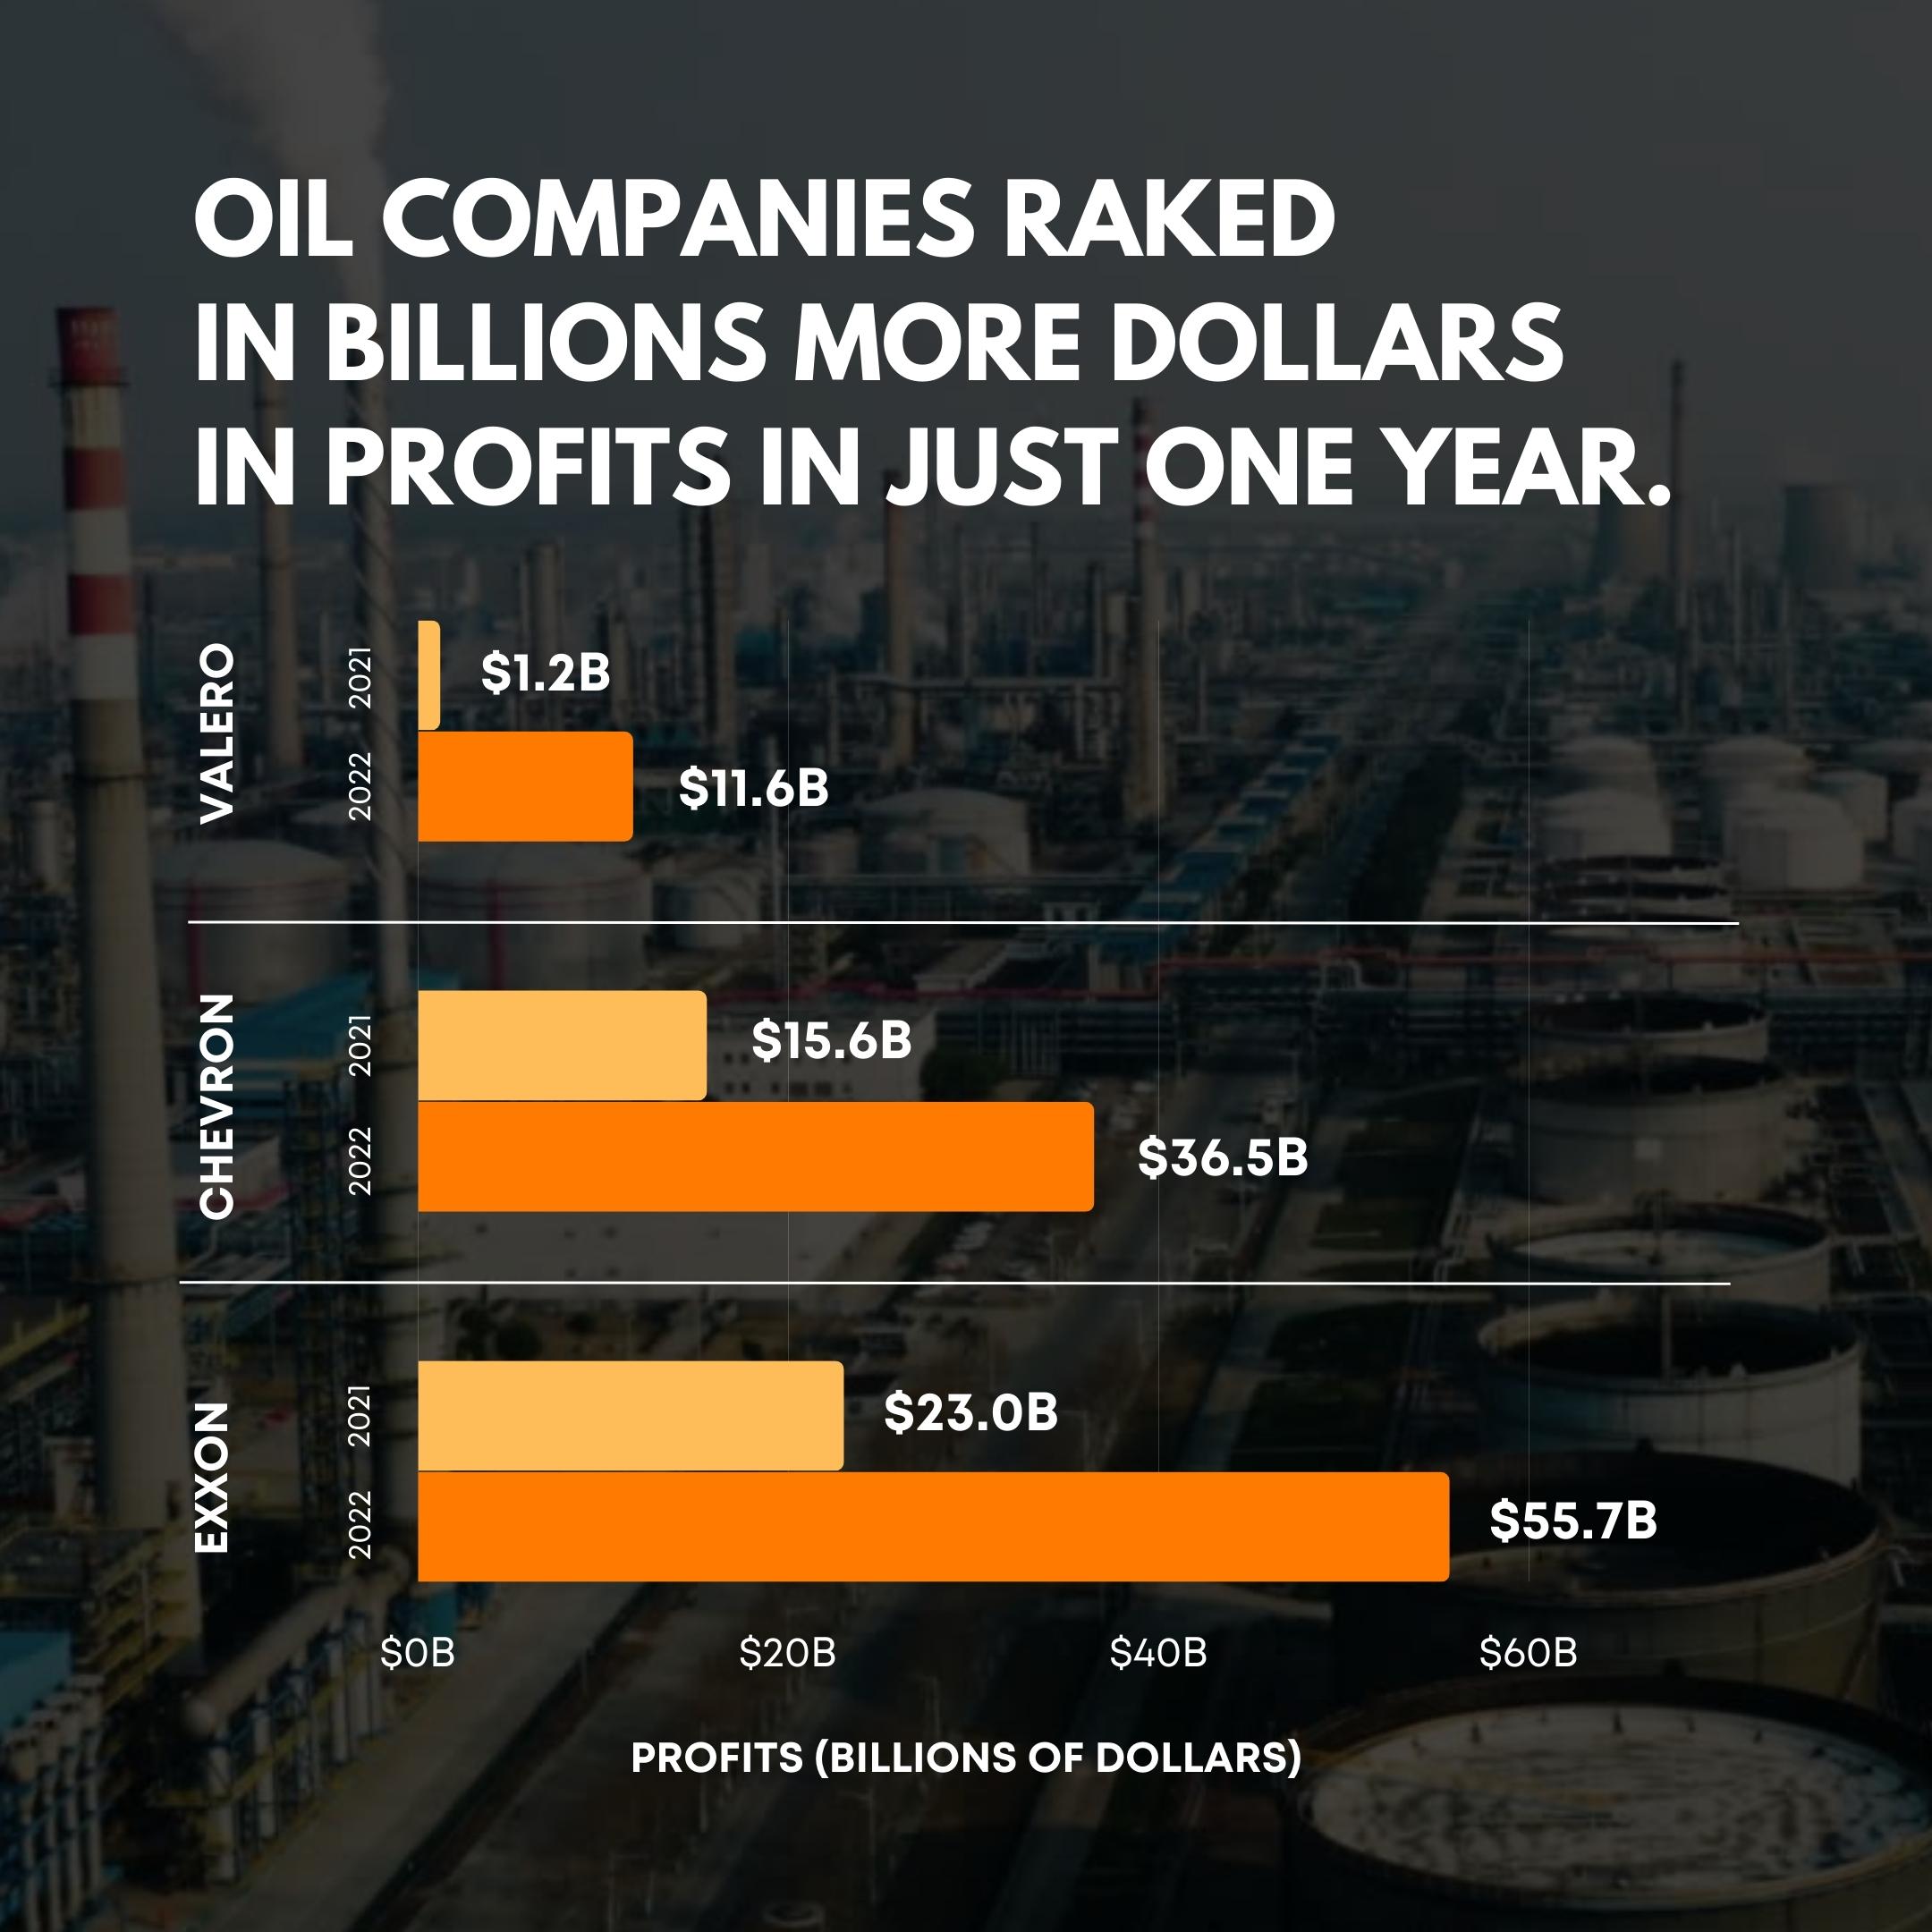
To grasp the sheer scale of the refining surge, financial analysts track the evolution of refining margins relative to historical baselines. Prior to the macroeconomic shifts of the early 2020s, a healthy benchmark crack spread hovered between $10 and $15 per barrel. During peak market dislocations, those same metrics skyrocketed past $30 to $40 per barrel across key regional hubs on the U.S. Gulf Coast and Northwest Europe.
Major integrated energy firms reported downstream operating income figures that routinely shattered previous multi-year records. This revenue surge fundamentally altered corporate liquidity positions, enabling firms to fortify their balance sheets against future macroeconomic volatility.
| Metric / Indicator | Pre-Disruption Baseline (2018–2019) | Peak Surge Period (2022–2023) | Current Market Equilibrium |
|---|---|---|---|
| Average Gulf Coast Crack Spread | $11.50 / barrel | $38.20 / barrel | $18.50 – $22.00 / barrel |
| Downstream Share of Total Operating Income | 15% – 22% | 45% – 58% | 30% – 38% |
| Global Refining Capacity Utilization | 81% – 83% | 93% – 96% | 88% – 91% |
| Capital Return to Shareholders (Buybacks & Dividends) | Moderate ($30B–$40B industry-wide) | Record High ($110B+ industry-wide) | Elevated & Stabilized |
As illustrated by the data, the structural shift was not merely a temporary blip but a profound recalibration of downstream profitability. Even as raw crude prices fluctuated in response to global monetary tightening and OPEC+ production quotas, the persistent tightness in refined product inventories maintained elevated profit floors for operators with sophisticated cracking assets.
Capital Allocation, Valuation Multiples, and Shareholder Yield
Faced with intense political scrutiny over these windfall profits, energy executives enacted precise capital allocation strategies designed to satisfy institutional investors rather than appease political critics. In past commodity cycles, high refining earnings frequently triggered speculative, capital-intensive expansion programs—building new mega-refineries that often oversupplied the market and destroyed long-term enterprise ROI.
This time, executives exercised capital discipline. Rather than deploying billions into greenfield refinery projects that face long-term risk of regulatory obsolescence, boards of directors prioritized:
- Aggressive Share Repurchases: Pumping excess downstream cash flow into equity buybacks to reduce share counts and elevate earnings per share (EPS).
- Dividend Growth and Special Distributions: Enhancing direct cash yields to appease institutional asset managers and pension funds demanding immediate value realization.
- Targeted Debottlenecking: Investing in incremental efficiency upgrades at existing facilities to maximize throughput without triggering massive environmental permitting reviews.
- Balance Sheet Deleveraging: Paying down long-term debt obligations to insulate corporate credit ratings against future macroeconomic downturns.
This disciplined approach transformed energy sector valuation multiples. Historically trading at a discount to broader technology and growth indices due to cyclical volatility, integrated oil equities achieved renewed favor among value investors seeking tangible cash flow generation and robust inflation hedges.
Regulatory Compliance and the Artificial Supply Moat
A critical, yet frequently underreported, driver of sustained high refining margins is the complex web of regulatory compliance mandates governing the energy sector. Environmental regulations, renewable fuel standard obligations, and permitting restrictions have combined to create an effective supply moat around incumbent refining assets.
Building a brand-new, complex refinery in the United States or Western Europe is practically untenable in the current regulatory environment. The timeline for environmental impact assessments, legal challenges, and capital expenditure payback periods extends decades into a policy landscape explicitly committed to fossil fuel phase-out. Consequently, existing refiners hold irreplaceable assets. They operate within a protected economic enclave where high barriers to entry guarantee that supply cannot easily expand to erode margins.
Furthermore, compliance costs associated with carbon reduction initiatives and clean-fuel transitions have disproportionately impacted smaller, independent refiners. Larger, well-capitalized integrated majors absorbed these regulatory compliance expenses more efficiently, consolidating market share and further cementing their pricing power.
Industry & Market Implications: Who Wins, Who Loses
The downstream refining surge generated clear winners and losers across the global economic landscape:
- Winners: Integrated oil majors with complex refining portfolios, institutional shareholders benefiting from record-breaking dividend yields and buybacks, and commodity trading houses adept at exploiting regional pricing arbitrage.
- Losers: Retail consumers facing persistently elevated fuel prices at the pump, energy-intensive manufacturing industries struggling with higher input costs, and independent airlines or logistics firms with limited capacity to hedge fuel price volatility.
From a macroeconomic perspective, the surge in refining earnings served as a powerful fiscal buffer for energy-producing nations and corporate balance sheets alike, though it contributed persistently to core inflationary pressures during the post-pandemic recovery cycle.
Frequently Asked Questions (People Also Ask)
Why did refining profits surge even when political leaders criticized oil companies?
Refining profits are driven by the "crack spread"—the difference between crude oil costs and the market price of finished products like gasoline and diesel. A combination of post-pandemic demand spikes, permanent refinery closures globally, and the loss of Russian product exports created a severe supply shortage of refined fuels. Because energy companies cannot easily or quickly build new refineries due to high capital costs and strict regulations, existing facilities operated at maximum capacity, capturing historic profit margins regardless of political rhetoric.
What is a crack spread, and why is it important for Big Oil earnings?
A crack spread represents the profit margin a refiner makes by cracking a barrel of crude oil into finished petroleum products. When crack spreads widen—as they did significantly during recent market disruptions—downstream segments of integrated energy companies experience exponential earnings growth, often offsetting flat or declining upstream extraction revenues.
How did oil companies spend their record refining windfalls?
Rather than investing heavily in new long-term refining infrastructure—which carries high regulatory and long-term energy transition risks—major energy enterprises focused on disciplined capital allocation. They prioritized massive share buybacks, increased dividend payouts to shareholders, debt reduction, and operational debottlenecking of existing facilities.
Will refining margins remain at these historic highs indefinitely?
While structural constraints and regulatory hurdles prevent rapid supply expansion, refining margins remain fundamentally cyclical. Over the medium to long term, slowing economic growth, fleet electrification, and incremental efficiency improvements are expected to normalize margins away from peak historical spikes, though structural floors are likely to remain higher than pre-2020 averages.
Future Outlook and Key Milestones to Watch
As the global energy landscape navigates the ongoing energy transition, the future of downstream refining hangs in a delicate balance. Corporate boards will face continuous pressure to reconcile short-term cash generation from traditional fossil fuel assets with long-term capital commitments toward low-carbon technologies, such as renewable diesel, green hydrogen, and carbon capture, utilization, and storage (CCUS).
Key milestones for market observers and investors to monitor include:
- Global Capacity Additions: Tracking upcoming refinery startups in the Middle East and Asia, which could rebalance international product flows and compress Western crack spreads.
- regulatory Shifts: Monitoring policy adjustments regarding environmental compliance, vehicle electrification mandates, and tax incentives for clean energy investments.
- Capital Return Sustainability: Evaluating whether energy enterprises maintain aggressive share buyback programs or pivot capital toward transition-related enterprise infrastructure scalability.
Ultimately, the story of Big Oil's refining surge is a masterclass in market economics over political friction. While public figures could command headlines, the unyielding laws of supply, demand, and structural capacity constraints ensured that downstream refiners commanded the ultimate financial reward.