Executive Takeaways
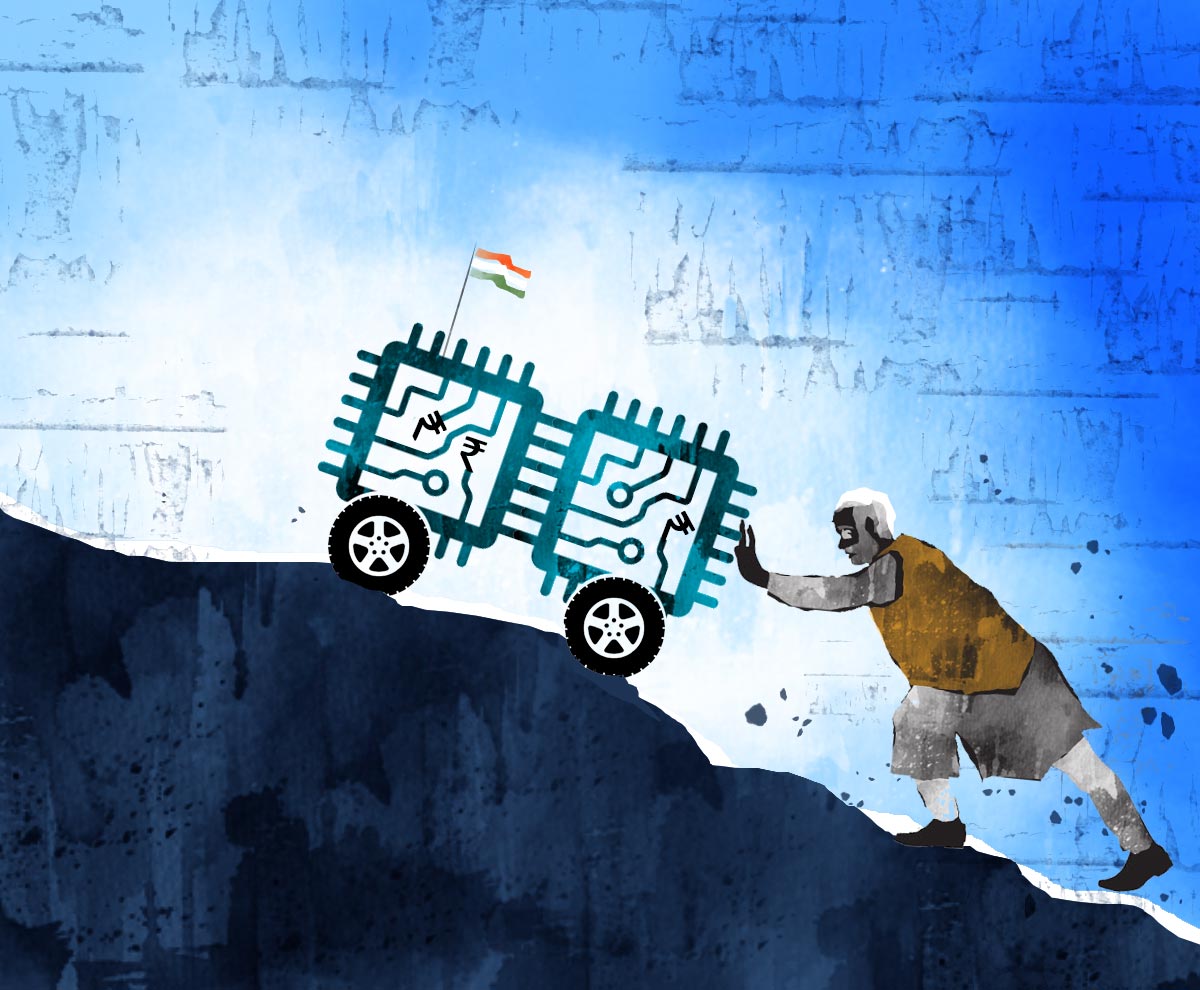
- Unprecedented Fiscal backing: The Indian government’s modified $10-billion India Semiconductor Mission (ISM) is underwriting up to 50% of capital expenditure on a pari-passu basis, paired with state-level top-up incentives that cover up to 70% of total project costs.
- Anchor Infrastructure Anchors: Major greenfield investments—led by Tata Electronics’ $11-billion joint venture with Taiwan’s PSMC in Dholera and Micron Technology’s $2.75-billion assembly and testing facility in Sanand—are moving from policy blueprints to physical cleanrooms.
- Strategic Geopolitical Positioning: As Western multinational enterprises accelerate their "China+1" supply chain diversification strategies, India is attempting to capture critical trailing-edge and compound semiconductor capacity to protect auto, industrial, and consumer hardware manufacturing.
- Operational Bottlenecks Remain: Success hinges on solving acute structural challenges: establishing ultra-pure water systems, uninterrupted green power corridors, advanced packaging talent pools, and achieving competitive wafer yield rates within tight commercial execution windows.
The Geopolitical Catalyst: Why SEMICON India 2026 Represents a Watershed Moment

For decades, the global semiconductor architecture relied on a tightly concentrated, hyper-efficient, but perilously fragile supply chain. Advanced photolithography technology flowed from Europe, EDA software and chip IP emanated from Silicon Valley, while physical wafer fabrication and advanced packaging concentrated in East Asia—primarily Taiwan, South Korea, China, and Japan. However, geopolitical friction across the Taiwan Strait, combined with post-pandemic supply disruptions, revealed the catastrophic vulnerability of this geographical concentration.
Against this backdrop, SEMICON India 2026 has emerged not merely as an industry trade show, but as a high-stakes diplomatic and corporate summit. Gathering chief executives from global equipment giants, foundry leaders, fabless design houses, and sovereign wealth managers, the event highlights New Delhi's transition from a long-time chip design services hub into an emerging silicon manufacturing power.
While India historically failed to convert its rich VLSI design talent into domestic fabrication capability—evidenced by the tragic destruction of the Semiconductor Complex Limited (SCL) facility in Mohali in 1989 and subsequent policy paralysis—the current mandate is built on institutional scale and state capital support. Prime Minister Narendra Modi's administration has elevated semiconductor sovereignty from a industrial objective to a core national security imperative.
Anatomy of a $10 Billion Fiscal Mechanism: Capital Allocation & Fab Economics
At the center of India’s semiconductor ambitions is the modified India Semiconductor Mission (ISM). Unlike previous policy frameworks that offered modest tax concessions or land grants, the current program is built around direct capital co-investment designed to compress enterprise pay-back periods and lower the high weighted average cost of capital (WACC) that traditionally discouraged foreign direct investment (FDI) in Indian manufacturing.
The economic architecture of the program operates on three main fronts:
1. Commercial Wafer Fabs (Silicon Node Fabrication)
The government offers 50% capital subsidy for setting up semiconductor fabs across all technology nodes—including legacy trailing-edge nodes (28nm, 40nm, 55nm, 90nm and above) as well as emerging mature technologies. By addressing trailing-edge chips first, New Delhi targets the massive structural demand from automotive, power electronics, IoT, and defense applications, where operational reliability and cost efficiency outweigh the need for bleeding-edge sub-3nm extreme ultraviolet (EUV) lithography.
2. Compound Semiconductors & Silicon Photonics
Recognizing the lower capital expenditure barriers and high growth trajectories of compound semiconductors (Gallium Nitride [GaN] and Silicon Carbide [SiC]), the program provides matched funding for sensor fabs, optoelectronics, and power discrete lines. These components are vital for electric vehicle (EV) powertrains, 5G/6G telecommunications infrastructure, and renewable energy grids.
3. OSAT & ATMP Infrastructure
Outsourced Semiconductor Assembly and Test (OSAT) and Assembly, Testing, Marking, and Packaging (ATMP) represent the quickest pathways to building a localized backend supply chain ecosystem. With advanced packaging techniques—such as 2.5D/3D integration and chiplet architectures—becoming crucial for computing performance, India’s financial incentives cover 50% of capital investments for backend infrastructure.
The Anchor Projects: Commercial Progress and Yield Optimization Realities
Capital incentives alone do not manufacture functional chips; execution discipline and high yield rates dictate long-term survival in the enterprise market. Current progress across flagship projects illustrates both the scale of execution and the operational risks involved.
The flagship project of the mission is the $11-billion semiconductor fabrication plant in Dholera, Gujarat, spearheaded by Tata Electronics in partnership with Taiwan's Powerchip Semiconductor Manufacturing Corporation (PSMC). Designed to process 300mm wafers across mature 28nm, 40nm, 55nm, and 110nm process nodes, the fab targets a total monthly capacity of up to 50,000 wafer starts. Tata’s capital expenditure strategy relies heavily on capturing domestic automotive demand from original equipment manufacturers (OEMs), defense contractors, and consumer electronics assemblers seeking locally sourced microcontrollers and power management ICs (PMICs).
Simultaneously, in Sanand, Gujarat, Micron Technology’s $2.75-billion ATMP facility represents the first major greenfield assembly and test investment backed by global capital. By leveraging advanced packaging technologies, Micron aims to process DRAM and NAND flash memory products into finished modules for enterprise data centers and mobile devices. This was quickly followed by joint ventures such as CG Power’s $900-million OSAT plant in partnership with Japan’s Renesas Electronics and Thailand’s Stars Microelectronics, alongside Tower Semiconductor's multi-billion dollar mega-fab proposal in Maharashtra.
Data Breakdown: India's Flagship Semiconductor Capital Projects
| Project / Corporate entity | Facility Type | Process Nodes / Tech Target | Total Estimated Capex | Key Technology Partners | Target Production Horizon |
|---|---|---|---|---|---|
| Tata Electronics / PSMC (Dholera, GJ) | 300mm Wafer Fab | 28nm, 40nm, 55nm, 110nm Legacy Nodes | $11.0 Billion | Powerchip Semiconductor (Taiwan) | Q4 2026 – Q1 2027 |
| Micron Technology (Sanand, GJ) | ATMP / OSAT Facility | High-Density Memory Packaging (DRAM/NAND) | $2.75 Billion | In-house Proprietary / Micron Global | Phase 1 Ramping 2025-2026 |
| CG Power / Renesas / Stars (Sanand, GJ) | OSAT Packaging Plant | Legacy & Advanced Discrete/Analog OSAT | $918 Million | Renesas (Japan) / Stars (Thailand) | Late 2026 |
| Kaynes Semicon (Sanand, GJ) | OSAT & Chiplet Packaging | Power Electronics & Microcontrollers | $395 Million | Global OSAT Technology Providers | 2026 Operational Target |
| Tower Semiconductor JV (Panvel, MH) | Commercial Wafer Fab | 65nm & 180nm Analog/RF Mixed-Signal | $10.0 Billion (Proposed) | Tower Semiconductor (Israel) | Under Final Regulatory Review |
Industry & Market Implications: Winners, Losers, and Macroeconomic Re-Balancing
The aggressive influx of capital into India's semiconductor landscape creates key winners and operational losers across the tech value chain:
Market Winners
- Upstream Equipment and Materials Suppliers: Companies like Applied Materials, Lam Research, KLA Corporation, and ASML stand to capture high-margin purchase orders as new cleanrooms require tool installations, metrology systems, and gas distribution units.
- Automotive and Industrial OEMs: Indian vehicle manufacturers (e.g., Tata Motors, Mahindra & Mahindra) and global industrial automation firms gain domestic access to critical trailing-edge chips, reducing supply risks and lowering working capital overhead.
- Domestic EDA and Chip Design Ecosystems: India already houses over 20% of the world's semiconductor design workforce. Local access to fabrication lines lowers the cost of prototyping for homegrown fabless startups, accelerating domestic IP creation.
Market Risk Profiles & Losers
- Unprepared Local Municipal Infrastructure: Semiconductor manufacturing requires massive scale: a modern fab consumes millions of gallons of ultra-pure water (UPW) daily alongside uninterrupted electrical power. Municipalities that fail to deliver 99.9999% power reliability risk severe yield losses for resident fabs.
- Legacy Overseas Backend Hubs: Standard low-margin packaging operations in traditional non-integrated regions face margin pressure as India links backend ATMP plants directly to its vast consumer electronics manufacturing market.
Frequently Asked Questions (People Also Ask)
What is the total value of India's semiconductor incentive program, and how does it function?
The government launched the India Semiconductor Mission (ISM) with an initial outlay of $10 billion. The policy offers direct fiscal support covering up to 50% of the total capital expenditures (capex) on a pari-passu basis for silicon wafer fabs, packaging facilities (OSAT/ATMP), and compound semiconductor plants. State governments often match these funds with an additional 15% to 20% in subsidies, tax rebates, discounted land, and power concessions.
Why is India focusing on mature/legacy trailing-edge nodes (e.g., 28nm, 40nm) instead of advanced 2nm or 3nm chips?
Leading-edge sub-5nm nodes require hundreds of billions of dollars in capital expenditure, highly specialized extreme ultraviolet (EUV) lithography tools, and decade-long yield curves, making them commercially risky for a new industry player. Conversely, trailing-edge nodes (28nm to 110nm) account for over 60% of total global volume demand, powering automotive electronics, industrial robotics, power grids, smart appliances, and mobile microcontrollers. Focusing on mature nodes provides immediate revenue stability, lowers initial capex risk, and builds baseline operational experience.
How does SEMICON India 2026 impact global supply chain resilience for Western enterprises?
By establishing a commercial fabrication and packaging hub in South Asia, global enterprises gain a critical geopolitical hedge against potential supply disruptions in East Asia. Multinationals can diversify their supply chains through a "China+1" or "Taiwan+1" footprint, reducing enterprise counterparty risk while placing backend assembly closer to India's growing electronics manufacturing industry.
What are the primary operational risks facing semiconductor facilities in India?
The primary execution risks involve technical yield management, supply chain integration for specialized raw materials (such as electronic-grade gases, ultra-pure chemicals, and silicon wafers), and municipal infrastructure performance. Fabs require continuous electricity without micro-fluctuations, immense volumes of ultra-pure water, and an expanded pool of skilled process engineers to maintain commercial yield targets.
Future Outlook: Strategic Milestones to Watch (2026-2030)
As the initial phase of the India Semiconductor Mission moves from construction to functional wafer output, the next strategic window will determine whether India can establish a self-sustaining ecosystem or remain dependent on imported sub-components.
Over the next 24 to 36 months, financial analysts and semiconductor executives will closely monitor three core operational metrics: first-pass commercial wafer yields at the Dholera fab complex, successful validation of Micron’s domestic packaging pipelines by tier-1 global hardware OEMs, and the announcement of "ISM Phase II." The second phase of policy incentives is expected to target chemical refinement clusters, specialty gas production, photolithography mask houses, and silicon wafer manufacturing—building out the upstream supply chain required to anchor true semiconductor sovereignty.
If executed successfully, India's multi-billion-dollar initiative will do more than simply diversify geographic risk for global chipmakers. It will permanently reconfigure global high-tech supply chains, establishing South Asia as a crucial pillar in the world's silicon economy.